Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Refund of Accumulated Input Tax Credit on Packing Materials under Section 54(3)(ii) of the CGST Act
    Detention of Goods in Transit: Consequences of Delay in Notice under Section 129(3)
    Case Laws Income Tax
    Section 192 TDS on Leave Travel Concession and the Effect of Subsisting Judicial Restraint
    Cross-Segment Price Manipulation in Stock Derivatives under the SEBI Act and PFUTP Regulations
    Case Laws Income Tax
    Enhanced Rate of Tax u/s 115BBE: Survey Surrenders of Excess Stock and Cash: Business Income, Deemed...
    Retention of Seized Mobile Phones and Bank Debit Cards Beyond the Section 67(7) Period
    Case Laws Customs
    Classification of Disposable Analytical Cartridges under Chapter 90 and Heading 3926
    Reasoned and Speaking Appellate Orders u/s 107 of the CGST Act: Duty to Decide Material Grounds of A...
    Pre-Movement E-Way Bill Compliance and Section 129 Detention for Undocumented Goods in Transit
    Case Laws Income Tax
    Faceless Reassessment Jurisdiction: Retrospective Validation under Section 147A and Automated Alloca...
    Doctrine of Merger: Effect of Non-Speaking and Speaking Dismissal of Special Leave Petitions on Merg...
    Case Laws Indian Laws
    Section 37 of the NDPS Act: Twin Conditions for Grant of Bail in Commercial Quantity Cases
    Case Laws Customs
    Pilferage of Imported Goods: Approval, Custody and Duty Liability under the Customs Act, 1962
    Case Laws Indian Laws
    Condonation of Delay in Statutory Appeals under Section 5 of the Limitation Act, 1963
    Case Laws Income Tax
    Condonation of Delay for Filing Revised Returns under Section 119(2)(b): Genuine Hardship and Merits...
    Case Laws Income Tax
    TDS Credit Where the Deductor Defaults: Proof of Deduction Without Form 16 or Form 16A
    Case Laws Indian Laws
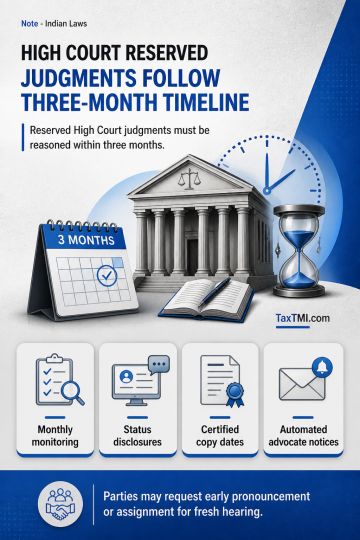
    Reserved High Court Judgments: Constitutional Timelines, Accountability and Litigant Remedies
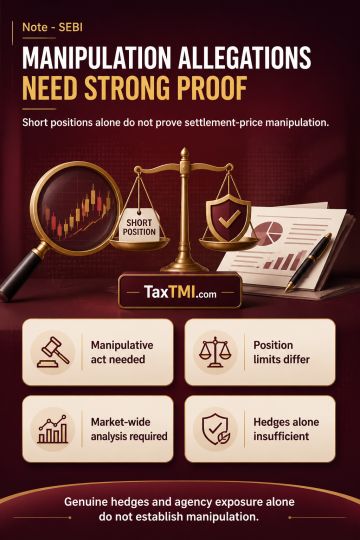
    Price Depression in Securities Markets: Evidentiary Requirements under the PFUTP Regulations
    Case Laws Income Tax
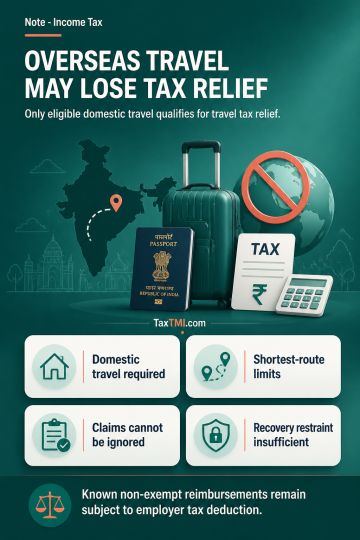
    Foreign Leave Travel Concession and Tax Deduction at Source under Sections 10(5), 192 and 201
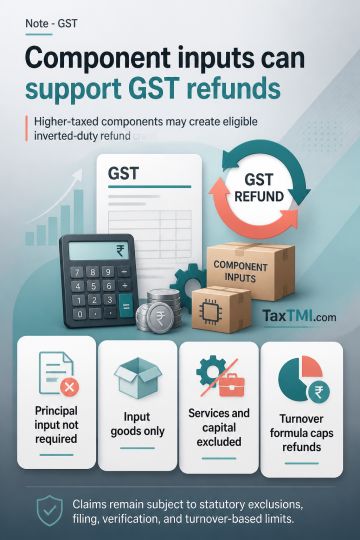
    Refund of Accumulated Input Tax Credit under Inverted Duty Structure: Section 54(3)(ii) and Rule 89(...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
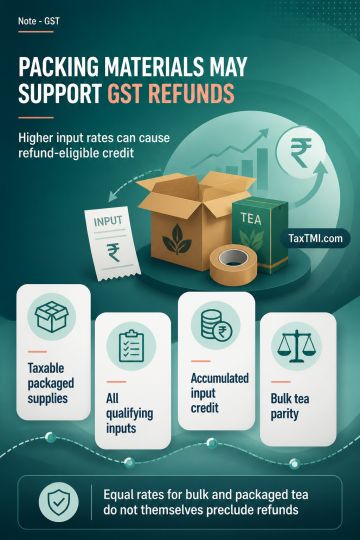
Packing-material input tax credit may support inverted-duty refunds when higher-rated inputs cause accumulation for taxable packaged supplies.
Refund of accumulated input tax credit under Section 54(3)(ii) may arise where packing materials used to make taxable packaged outward supplies bear a higher tax rate than the outward supply and generate the accumulation. The inquiry extends to all qualifying inputs and is not limited to a principal raw material. Parity between the rate on bulk tea and packaged tea does not itself preclude refund if higher-taxed packing materials used for the packaged supply are the cause of unutilised credit.
Case Laws GST
Show AI Summary
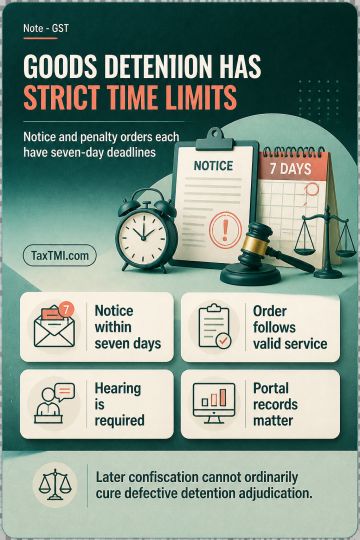
Mandatory detention timelines require timely notice, hearing and penalty order, preventing prolonged restraint of goods in transit.
Section 129(3) establishes a mandatory two-stage timeline: issuance of the penalty notice within seven days of formal detention or seizure, followed by a penalty order within seven days of legally effective service. The periods are independent, and compliance at one stage cannot cure delay at the other. Service, portal timestamps and the electronic records required under Rule 142 are material to chronology. Penalty requires a hearing, while payment under protest may still require a reasoned order to preserve appellate access. Later confiscation action cannot ordinarily cure a defective detention adjudication.
Case Laws Income Tax
Show AI Summary
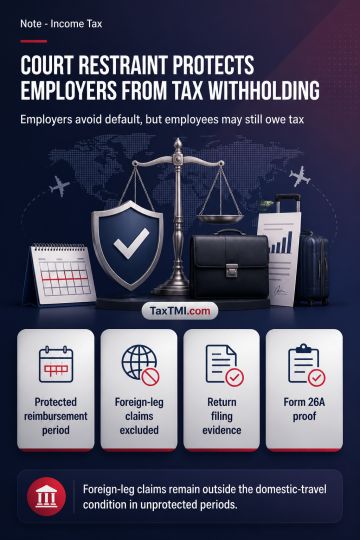
Subsisting judicial restraint on leave travel concession withholding prevents employer default while preserving employees' underlying tax liability.
A subsisting judicial restraint expressly prohibiting deduction from leave travel concession reimbursements governs the employer's withholding conduct for the covered period. Non-deduction in compliance with that restraint cannot constitute failure to discharge an enforceable duty under Sections 192 and 201, even if the underlying exemption claim is later found substantively unavailable. The restraint does not eliminate employee-level tax liability. For unprotected periods, foreign-leg or circuitous travel claims remain outside the domestic-travel condition, and payer protection may depend on proving employee return filing, income inclusion and tax payment through Form 26A.
Case Laws SEBI
Show AI Summary
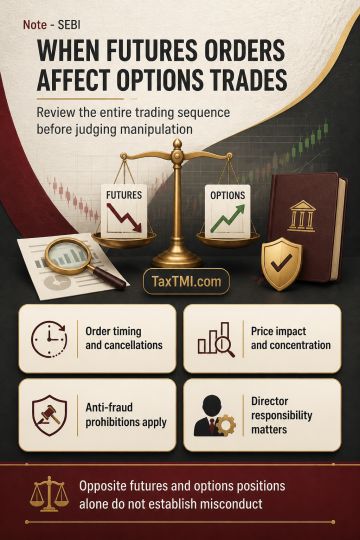
Cross-segment price manipulation examines whether futures orders artificially influence option executions, engaging anti-fraud rules, director responsibility, and interim safeguards.
Cross-segment price manipulation may arise where aggressive futures orders alter the last traded price or visible order-book conditions so that larger, sentimentally opposite options orders obtain favourable execution. The relevant inquiry considers the integrated sequence of resting orders, aggressive executions, cancellations, timing, concentration, price impact and delta-adjusted exposure. Anti-fraud prohibitions cover manipulative devices, false appearances of trading and price manipulation, while opposite futures and options positions alone do not establish misconduct. Director liability requires responsibility for business conduct, or consent, connivance or neglect.
Case Laws Income Tax
Show AI Summary
Survey surrender characterisation determines whether excess stock and cash are taxed as business income or under special deemed-income provisions.
The special regime in Section 115BBE is consequential: it applies only after the amount is properly brought within a specified deeming provision, and a survey surrender, book entry or return description cannot itself create that character. Mixed stock forming part of ordinary business inventory and credibly explained through business records may be assessed as business income at normal rates. Similarly, excess cash may be treated as business income where a commercial source is satisfactorily established and no separate or non-business source is shown.
Case Laws GST
Show AI Summary
Statutory limits on GST seizure require return of retained mobile phones and debit cards without a valid extension.
Section 67(7) establishes a six-month return rule where no notice in respect of seized goods is issued. Any further period requires sufficient cause, action by the proper officer, and a maximum further period of six months; ongoing investigation cannot replace an actual extension order. Although Section 67(7) uses "goods" while Section 67(2) also covers documents, books and things, its application to seized mobile phones and bank debit cards indicates that classification cannot be used to avoid the temporal restriction where articles are held under statutory seizure.
Case Laws Customs
Show AI Summary
Analytical cartridge classification follows functional integration and sole-use suitability, not plastic composition, disposability, or general consumable character.
STA micro-cuvettes containing an enclosed steel ball are assessed as complete functional components of a blood-coagulation analyser, rather than merely as plastic laboratory articles. Classification turns on their objective design, analytical role, exclusive or principal suitability and absence of practical general use. Chapter 90 Note 2 requires consideration of an independent specific heading first and then classification of other dedicated parts or accessories with the relevant instrument. Disposable or single-use status and plastic composition do not by themselves establish classification as residual plastic articles.
Case Laws GST
Show AI Summary
Speaking appellate orders require findings on material GST appeal grounds, ensuring fair hearings and meaningful higher review.
Section 107(12) requires a written appellate order identifying material points for determination, deciding them, and giving reasons. Formulaic confirmation of original assessment does not establish independent appellate consideration, particularly where jurisdiction, notice, evidence, quantification, taxability, section 74 conditions, interest, or penalty are contested. Sections 74 and 75 require a defined notice, disclosure of relied-upon material, effective hearing, and reasoned determination within the notice's scope. Where procedural defects arise at the original stage as well as on appeal, reconsideration must occur at the level capable of curing the foundational defect without expanding the show-cause case.
Case Laws GST
Show AI Summary
Pre-movement e-way bill compliance requires invoices and transport records before dispatch, while later documents cannot cure undocumented transit.
Pre-movement e-way bill compliance requires issuance of an invoice at or before removal, generation of the e-way bill before road movement, and carriage of both records during transit. Where goods are intercepted without either record, the contravention arises upon commencement of undocumented movement; documents generated only after interception cannot retrospectively establish compliance. Such documents may still be considered with other contemporaneous evidence when assessing bona fides or alleged intent to evade tax. Section 129 detention proceedings remain subject to notice, hearing, electronic-summary and statutory-timeline requirements.
Case Laws Income Tax
Show AI Summary
Automated allocation in reassessment determines officer jurisdiction, while retrospective validation cannot bypass continuing faceless-scheme requirements.
Section 151A and the e-Assessment of Income Escaping Assessment Scheme, 2022 require covered reassessment functions and section 148 notice issuance through automated allocation. Risk-based selection of cases is distinct from randomised allocation of the officer authorised to act. Sections 148A and 148 form an integrated reassessment sequence, so general concurrent jurisdiction, administrative instructions or digital service cannot substitute for the prescribed faceless allocation. Section 147A did not amend the continuing statutory and scheme-based allocation requirements and is treated as constitutionally invalid.
Case Laws GST
Show AI Summary
Doctrine of merger distinguishes refusal of special leave from appellate disposal, preserving review subject to independent procedural limits.
Under Article 136, a refusal of special leave remains a discretionary leave-stage determination. A non-speaking dismissal does not merge the challenged lower-court decision into a Supreme Court order, affirm its reasoning, or automatically create res judicata. A speaking refusal may bind only as to legal propositions expressly declared under Article 141, without producing merger. Merger arises when leave is granted and appellate jurisdiction is exercised. Review, writ, and remanded proceedings remain subject to independent procedural requirements, including limitation and safeguards against abuse.
Case Laws Indian Laws
Show AI Summary
NDPS commercial-quantity bail requires independent proof of non-guilt and low reoffending risk alongside proportionate safeguards.
Section 37 of the NDPS Act imposes cumulative bail conditions in commercial-quantity cases: the court must find reasonable grounds to believe the accused is not guilty and unlikely to reoffend while on bail. These requirements supplement ordinary bail factors and demand a genuine, provisional assessment of credible material. Personal liberty and trial delay remain relevant, but must be reconciled with the statutory threshold. Bail conditions, including verification safeguards for foreign nationals, must be proportionate, genuine and capable of enforcement.
Case Laws Customs
Show AI Summary
Approved customs custodians bear duty for proven pilferage during custody, but not for losses before their approval takes effect.
Customs-duty liability for pilfered imported goods arises only where pilferage occurs after unloading in a customs area while goods are held by an approved custodian. Approval is indispensable; factual control or statutory custody alone does not impose this liability for a period before approval. Importer duty exemption for pre-clearance pilferage operates alongside the custodian's revenue liability. Pilferage must be proved through contemporaneous records and cannot be presumed from every cargo discrepancy, shortage, or loss.
Case Laws Indian Laws
Show AI Summary
Condonation of delay under Section 5 remains available in special statutory appeals unless the governing scheme clearly excludes it.
Section 5 of the Limitation Act, 1963 applies to a special statutory appeal through Section 29(2) unless the governing enactment excludes it expressly or by necessary implication. A special limitation period alone is insufficient to exclude condonation. Restrictive language, a defined maximum condonable period, or a complete statutory limitation code may create a non-extendable outer limit. Section 9 of the Chhattisgarh Rajya Suraksha Adhiniyam contains a 30-day appeal period and excludes certified-copy time, but lacks an express bar or outer condonation ceiling; delay may therefore be considered upon proof of sufficient cause.
Case Laws Income Tax
Show AI Summary
Genuine hardship in delayed revised-return claims requires prima facie verification without converting condonation into final tax adjudication.
Section 119(2)(b) may permit admission of a delayed revised-return claim where expiry of the Section 139(5) period causes genuine hardship. Condonation removes only the procedural bar and does not establish exemption, refund, or interest entitlement. Genuine hardship requires assessment of bona fides, the nature of the omission, promptness after discovery, legal plausibility, and the consequence of refusal. Circular No. 9/2015 permits prima facie verification and inquiry, but substantive taxability and refund entitlement remain for merits examination.
Case Laws Income Tax
Show AI Summary
TDS credit after verified deduction protects taxpayers from demands and refund adjustments caused by deductor default.
TDS credit in domestic deductor-default cases depends on verified actual deduction from the taxpayer's income, not solely on deposit, TDS statements, Form 16 or Form 16A, or Form 26AS reflection. Section 205 bars direct or indirect recovery, including refund adjustment, to the extent tax was deducted. The taxpayer must provide reliable payment-specific evidence, and the Assessing Officer must verify the claim while the Department proceeds against the defaulting deductor.
Case Laws Indian Laws
Show AI Summary
Timely reserved judgments: a three-month framework, transparency, and staged remedies protect liberty and require reasoned decisions.
Reserved High Court judgments are subject to a three-month framework for a reasoned pronouncement, supported by monthly monitoring, status disclosures, date-recorded certified copies, and automated notice to advocates. Urgent matters may receive an operative-part pronouncement, but reasons must be uploaded within seven days or, where practical difficulties exist, within fifteen days. Parties may seek early pronouncement after the specified period and, after further delay, request withdrawal and assignment for a fresh hearing.
Case Laws SEBI
Show AI Summary
Settlement-price depression allegations require cogent proof of manipulation, not merely short exposure, closing sales, or position-limit non-disclosure.
Settlement-price depression under the PFUTP framework requires cogent proof of a manipulative act, device, scheme or artifice, not merely a substantial short derivative position, closing-window sales, or an incentive to benefit from a lower settlement price. Position concentration and position-limit non-disclosure are distinct from PFUTP fraud. Sales below the last traded price require market-wide causal analysis of other trading activity, execution mechanics, benchmark methodology, commercial rationale, and actual price impact. A genuine hedge and agency-attributed exposure do not, without further proof, establish manipulation.
Case Laws Income Tax
Show AI Summary
Foreign LTC tax exemption requires domestic travel; employers must deduct tax on known non-exempt travel reimbursements.
Foreign LTC/LFC payments for itineraries containing an overseas leg are outside the Section 10(5) exemption, which is confined to actual eligible domestic travel subject to Rule 2B shortest-route and fare conditions. Under Section 192, employers must include known non-exempt payments in estimated salary and deduct tax; they cannot disregard available claim records showing foreign or circuitous travel. A recovery restraint does not automatically suspend the deduction obligation. Section 201 recipient-compliance conditions, interest, and penalty based on reasonable cause require separate analysis.
Case Laws GST
Show AI Summary
Inverted-duty GST refunds remain available where higher-taxed component inputs, rather than only principal inputs, cause accumulated eligible credit.
Refund of accumulated unutilised ITC under an inverted-duty structure depends on a causal link between higher-taxed input goods and lower-taxed output supplies. The test is not restricted to the principal raw material; higher-rated component inputs may support a claim despite parity between the principal input and output. Refund remains confined to credit on input goods, excluding input services and capital goods. Rule 89(5) separately determines the maximum refundable amount through its turnover-based formula, subject to statutory exclusions and prescribed filing and verification requirements.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Intermediary Services Under Section 2(13) of the IGST Act and Export of Services Under Section 2(6): Treatment of Education Consultancy Commissions

31 January, 2026

Contents
Circulars
Acts
Plus +
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

This note presents a concise research digest of the judicial decision, summarising the key issues, findings, and outcome. The judgment is analysed in the context of its factual background, issues framed, and conclusions reached by the Court.

2025 (10) TMI 371 - DELHI HIGH COURT

Case Snapshot

A writ petition was filed by the revenue authority challenging appellate orders that directed grant of GST refund to a taxpayer engaged in education consultancy services connected with admissions to foreign educational institutions. The central controversy was whether the taxpayer's commission-based services amounted to "export of services" or were "intermediary services", which would alter the place of supply and, consequently, the refund entitlement. The High Court declined to interfere, upheld the appellate approach that treated the supplies as export of services, and directed processing of refund with applicable statutory interest within a stipulated timeline.

Material Facts

The taxpayer carried on education consultancy activities for Indian students intending to pursue higher education abroad. The taxpayer entered into agreements with foreign educational institutions under which it provided counselling/consulting and related support, leading to student applications and possible admissions in the concerned institutions.

Upon admission of students, the foreign educational institutions paid commission to the taxpayer in terms of the agreements. The taxpayer filed multiple refund applications for tax paid on the premise that the underlying supplies constituted export of services. Several refund claims were rejected by the proper officer on grounds that included: (i) the taxpayer being an "intermediary" under Section 2(13) of the Integrated Goods and Services Tax Act, 2017 (IGST Act) read with Section 13(8) of the IGST Act; (ii) time bar under Section 54(1) of the Central Goods and Services Tax Act, 2017 (CGST Act); and (iii) an asserted mismatch in the refund category selected in the application.

The taxpayer appealed. The appellate authority set aside the refund rejection orders and held that the taxpayer was not an intermediary; that the relationship with foreign educational institutions was on a principal-to-principal basis; and that the taxpayer's services were in the nature of marketing services qualifying as export of services under Section 2(6) of the IGST Act. The revenue authority challenged the appellate orders in writ proceedings under Articles 226 and 227 of the Constitution of India.

The revenue authority's position was that contractual clauses described the taxpayer as an "agent", and therefore the taxpayer should be treated as an intermediary. Reliance was also placed on Circular No. 159/15/2021-GST and on an order-in-original (details not reproduced here due to anonymisation requirements) alleging non-discharge of tax liability and imposition of penalties.

The taxpayer contended that the controversy was covered by prior judicial reasoning on the meaning of "intermediary" and the determination of the service "recipient" and "place of supply", and that its services were supplied on its own account to foreign entities, with consideration received in foreign exchange. The petition sought interference with the refund grant. The High Court considered whether refund entitlement had been correctly determined on the intermediary/export axis.

Issue Involved

(i) Whether education consultancy/marketing services provided by the taxpayer to foreign educational institutions, resulting in commission, qualify as "export of services" under Section 2(6) of the IGST Act.

(ii) Whether the taxpayer is an "intermediary" within the meaning of Section 2(13) of the IGST Act, so as to attract the place of supply deeming rule in Section 13(8)(b) of the IGST Act (as it then stood), thereby negating export status.

(iii) Whether the appellate authority's refund-granting orders warranted interference in writ jurisdiction under Articles 226 and 227 of the Constitution of India.

Decision

The High Court dismissed the writ petition and declined to entertain the revenue authority's challenge to the appellate orders. It held, in substance, that the taxpayer's services rendered to foreign educational institutions, with earnings in foreign exchange, would not constitute "intermediary services".

The Court consequently sustained the appellate authority's conclusion that the supplies qualified as export of services and that refunds were liable to be granted. It directed that the refund be processed in terms of the appellate orders and granted along with applicable statutory interest in accordance with law, within two months. Other reliefs, if any, were disposed of. Further procedural particulars are not stated in the document.

Key Observations

1. Intermediary concept hinges on "arranging or facilitating", not on supplying on own account. Section 2(13) of the IGST Act defines "intermediary" as a broker/agent or any person who arranges or facilitates the supply of goods or services between two or more persons, but excludes a person who supplies such goods or services on his own account. The Court treated the exclusionary limb as decisive in cases where the taxpayer itself supplies services to the foreign entity, rather than arranging a supply from a third party.

2. Recipient identification is contract-and-consideration driven. The reasoning proceeds on an established principle that the "recipient" of a service is determined by the contractual relationship and by identifying who has the right to receive the service and who bears the obligation to pay consideration. The Court accepted that Indian students might be "users" or beneficiaries of the activity, but that does not automatically make them "recipients" for place-of-supply/export analysis where the contract and consideration flow point to the foreign educational institution.

3. Principal-to-principal characterisation supported export treatment. The appellate authority's finding-accepted by the High Court-that foreign educational institutions retained the right of admission and that the taxpayer did not act as their agent was treated as consistent with a principal-to-principal relationship. On that footing, the taxpayer's activity was treated as marketing/consultancy supplied to the foreign institution.

4. Section 13 architecture: default rule versus intermediary exception. The statutory scheme discussed by the Court contrasts Section 13(2) of the IGST Act (default rule: place of supply is the location of the recipient, where either supplier or recipient is outside India) with Section 13(8)(b) (intermediary services: place of supply is the location of the supplier). The revenue authority's case depended on successfully classifying the taxpayer as an intermediary to trigger Section 13(8)(b) and thereby deny export status under Section 2(6)(iii) (place of supply outside India). The Court rejected the intermediary classification on the facts as appreciated.

5. The "agent" label in agreements is not, by itself, determinative. While the revenue authority highlighted that some agreement clauses referred to the taxpayer as an "agent", the Court's approach indicates that substance prevails over nomenclature: the operative test remains whether the taxpayer is merely arranging/facilitating a supply between two persons, or whether it supplies services on its own account to the foreign entity.

6. Treatment of the CBIC circular. Circular No. 159/15/2021-GST was relied upon by the revenue authority to assert taxability in intermediary situations. The Court, however, decided the controversy by applying the statutory definition in Section 2(13) and the place-of-supply framework in Section 13, read with the export definition in Section 2(6), and by following judicial reasoning on the intermediary/export distinction. Any further granular interpretive content of the circular, beyond its general invocation, is not stated in the document.

7. Refund adjudication must address merits coherently. The appellate authority had criticised the rejection orders as arbitrary and without proper application of mind to agreements/records, and had indicated that the proper officer ought to have examined the merits of the claim rather than rejecting it in the manner done. The High Court's refusal to interfere implicitly affirms that the appellate authority's reasoning on intermediary status and export eligibility was sustainable in law on the material considered.

8. Legislative-policy movement noted (recommendation regarding Section 13(8)(b)). The Court noted that the GST Council, in its 56th meeting, recommended omission of clause (b) of Section 13(8) of the IGST Act, with the stated intent that place of supply for intermediary services would then be determined under Section 13(2) (location of recipient), helping exporters claim export benefits. The document records this as a recommendation and describes the intended consequence "after the said law amendment"; the factum of enactment and its effective date are not stated in the document.

Practical Relevance

1. Classification discipline for cross-border service suppliers. The decision reinforces that education consultancy/marketing arrangements with foreign institutions may qualify as export of services where the foreign institution is the service recipient, the supply is on the taxpayer's own account, and the taxpayer is not merely arranging a supply between the foreign institution and Indian students. For practitioners, the drafting and implementation of agreements must align with the Section 2(13) exclusion (supply on own account) rather than presenting an arrangement that is purely facilitative/agent-like in substance.

2. Documentary alignment with export of services conditions under Section 2(6). Even where Section 2(6) is invoked, refund eligibility typically depends on demonstrating each statutory ingredient, including recipient located outside India and payment in convertible foreign exchange (or in Indian rupees wherever permitted by the Reserve Bank of India, as reflected in Section 2(6)(iv)). The present decision turned substantially on recipient/intermediary characterisation; other evidentiary aspects, and how they were proved in the specific proceedings, are not stated in the document.

3. Place of supply disputes remain central to refund litigation. The case exemplifies the recurring litigation pattern: the revenue authority may deny refund by invoking intermediary status to apply Section 13(8)(b) (supplier-location place of supply), thereby failing Section 2(6)(iii). Tax teams should expect adjudication to focus on whether the taxpayer "arranges or facilitates" a supply between two persons or supplies services directly to a foreign recipient.

4. Writ interference with refund appellate orders is not routine. The dismissal indicates judicial reluctance to reopen the factual and contractual appreciation already undertaken by the appellate authority where the legal test is correctly applied. While writ jurisdiction under Articles 226 and 227 is broad, it is generally exercised to correct jurisdictional error or patent illegality rather than to reappreciate contractual facts, particularly when the appellate authority has considered agreements and records.

5. Treatment of time bar and procedural objections. The refund rejection orders had also invoked Section 54(1) of the CGST Act (limitation) and procedural grounds (refund category). The High Court's analysis, as captured, focuses on intermediary/export qualification and refund entitlement; the final determination on limitation/procedural aspects on independent reasoning is not stated in the document. Practitioners should nonetheless anticipate that such objections may arise alongside intermediary arguments and should be addressed comprehensively in refund documentation and appeals.


Full Text:

2025 (10) TMI 371 - DELHI HIGH COURT

Topics

Acts Income Tax