Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Consolidated Show Cause Notices under Sections 73 and 74 and Taxability of School Affiliation Servic...
    Fraudulent Input Tax Credit from Non-Existent Suppliers: Application of Sections 16, 74 and 155 of t...
    Case Laws Money Laundering
    Prolonged Pre-Trial Incarceration and Bail under Section 45 of the Prevention of Money-Laundering Ac...
    Case Laws Income Tax
    Prospective Operation of Section 56(2)(x)(b) in Stamp-Value Difference Cases Involving Immovable Pro...
    Seizure of Cash under Section 67 of the CGST Act and Interest on Illegal Retention
    Case Laws Income Tax
    Disallowance of Salary Expenditure for Allegedly Non-Genuine Services under Section 37
    Case Laws Income Tax
    Fair Market Value of Unquoted Equity Shares Under Section 56(2)(viib) and Rule 11UA
    Refund of Excess IGST Paid on Exports Following Clerical Error in FORM GSTR-3B
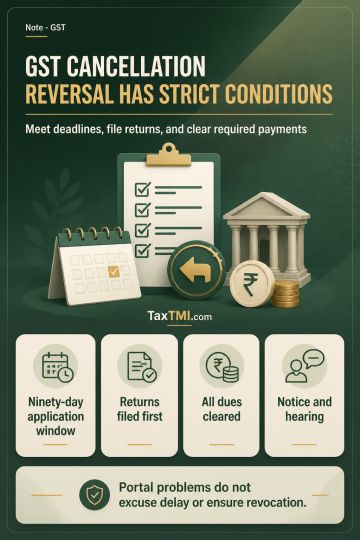
    Revocation of Cancellation of GST Registration for Non-Filing of Returns under Section 30 and Rule 2...
    Case Laws Income Tax
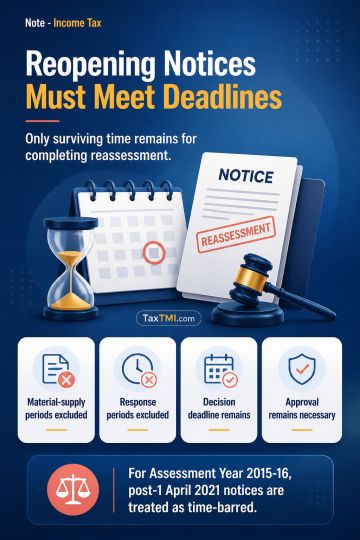
    TOLA, Section 149 and the Surviving-Time Test for Reassessment Proceedings
    Case Laws Customs
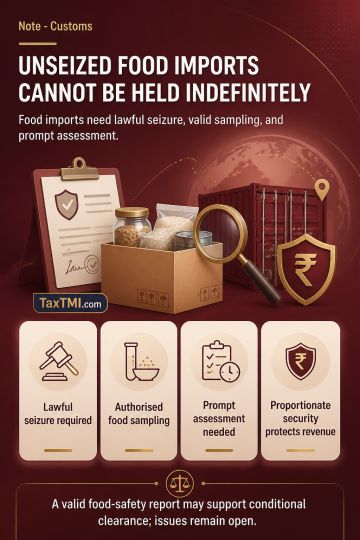
    Provisional Release of Unseized Imported Food Consignments under the Customs Act, 1962
    Case Laws Customs
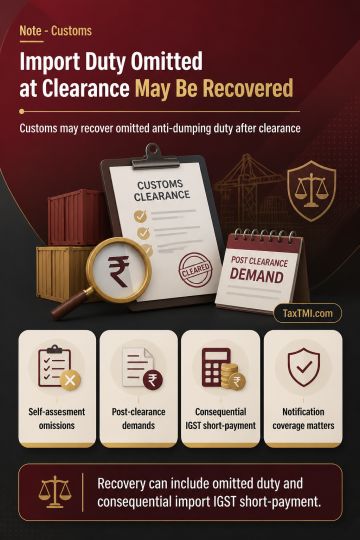
    Recovery of Unpaid Anti-Dumping Duty After Self-Assessment Under Section 28 of the Customs Act, 1962
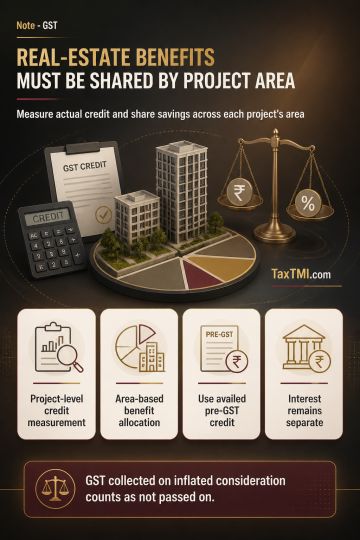
    Project-Wise Anti-Profiteering Methodology in Real Estate under Section 171 of the Central Goods and...
    Case Laws Income Tax
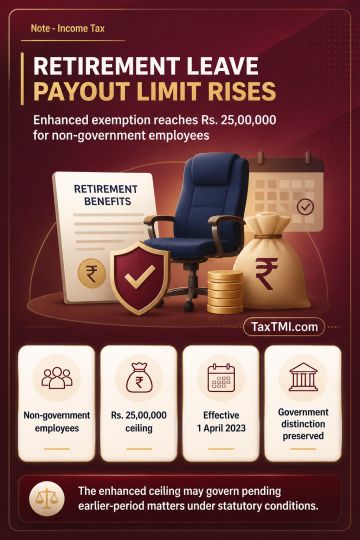
    Retirement Leave Encashment Exemption under Section 10(10AA)(ii) and Retrospective Application of No...
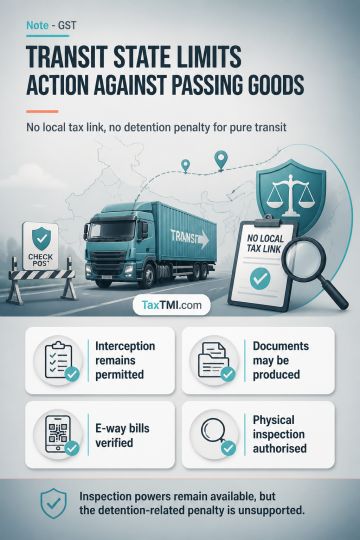
    Transit-State Jurisdiction under GST: Limits on Detention and Penalty in External Inter-State Suppli...
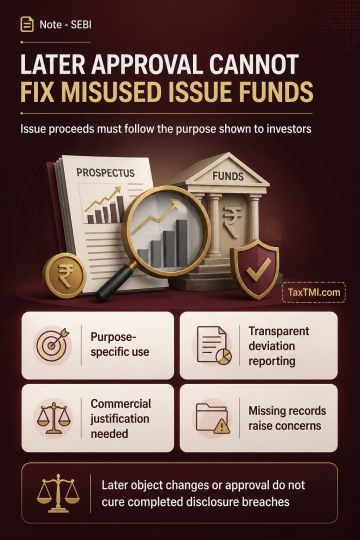
    Post-Facto Shareholder Ratification of Diversion of Preferential Issue Proceeds under the PFUTP Regu...
    Case Laws Income Tax
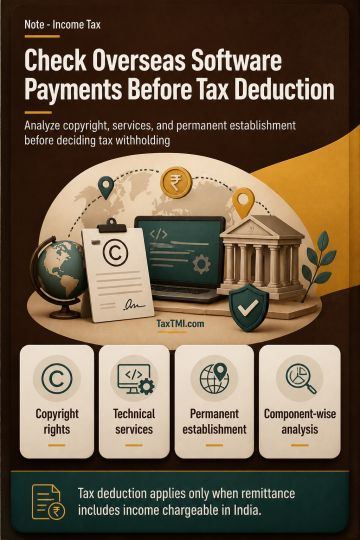
    Section 195 Withholding on Payments to Non-Residents: Royalty, Fees for Technical Services and Busin...
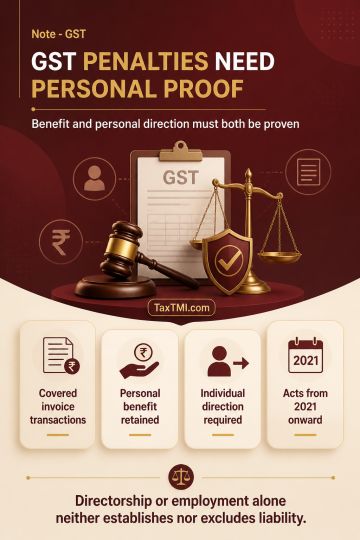
    Penalty: Scope of "Any Person" under Section 122(1A) of the Central Goods and Services Tax Act, 2017
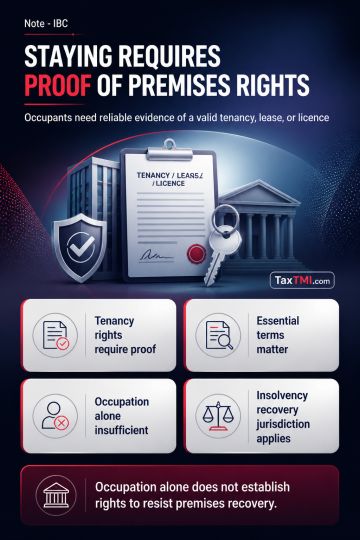
    Recovery of Corporate Debtor Premises and Proof of Tenancy, Lease or Licence Rights under the Insolv...
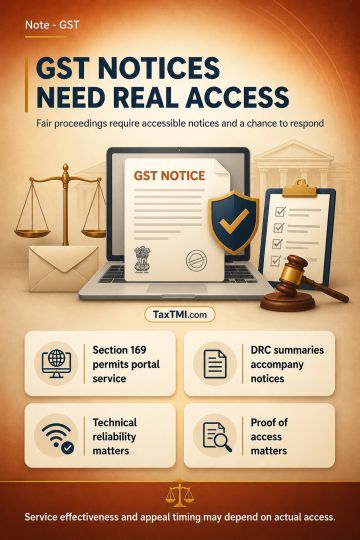
    Service of GST Notices through the Common Portal: Statutory Validity and Practical Accessibility
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
School affiliation services fall outside educational exemption without a direct nexus to admissions or examination conduct.
Consolidated show cause notices may combine financial years governed by Sections 73 and 74 where liabilities are segregated period-wise, each component independently meets limitation and notice requirements, the additional ingredients for fraud-based proceedings are satisfied, and no actual prejudice arises. School affiliation and affiliation-form processing charges are independent taxable supplies where they concern institutional eligibility and compliance, rather than directly and immediately relating to student admission or the conduct of examinations. A broad connection with education does not satisfy the educational-services exemption.
Case Laws GST
Show AI Summary
Fraudulent input tax credit requires proof of fictitious supplies, absent goods receipt, and fraud-linked self-assessment, not cancellation alone.
Input tax credit from allegedly non-existent suppliers depends on proof of genuine supply and actual receipt of goods or services, not merely invoices, accounting entries, or banking-channel payments. Section 155 places the burden of establishing ITC eligibility on the claimant. Section 74 requires more than ineligible credit: the wrongful availment must be linked to fraud, wilful misstatement, or suppression to evade tax. Retrospective supplier-registration cancellation is relevant evidence but is not conclusive. A fraud-based notice must disclose facts showing fictitious suppliers, absence of supply, and a basis for inferring the recipient's knowledge or participation.
Case Laws Money Laundering
Show AI Summary
Prolonged pre-trial incarceration may justify conditional PMLA bail when delayed trials make continued detention constitutionally disproportionate.
Section 45 of the Prevention of Money-Laundering Act remains the stringent ordinary bail threshold, requiring prosecutorial opportunity and, on opposition, reasonable grounds to believe that the accused is not guilty and unlikely to offend while on bail. Article 21 nevertheless requires a separate, fact-sensitive inquiry where prolonged pre-trial detention and an unrealistic trial timetable make custody disproportionate. Relevant factors include custody length, trial progress, remaining witnesses, secured documentary evidence, source of delay, predicate-case status, and risks of absconding or witness interference. Conditions such as passport surrender, attendance, non-contact directions, and residence disclosure may safeguard the trial.
Case Laws Income Tax
Show AI Summary
Prospective operation of stamp-value taxation prevents retrospective application where property agreements and substantial payments predate the charging provision.
Section 56(2)(x)(b) applies to immovable property received for inadequate consideration only where its temporal and valuation conditions are satisfied. A stamp-value difference alone does not establish taxability. Where consideration was fixed and substantial payments or contractual performance occurred before the charging provision commenced, later conveyance or registration does not by itself attract the later charge. Agreement-date valuation is available only for covered transactions where consideration was fixed and paid, wholly or partly, through prescribed banking or electronic modes on or before the agreement date. The tax authority must identify the correct statutory basis and provide a meaningful opportunity to respond.
Case Laws GST
Show AI Summary
GST cash seizure limits require statutory relevance and restitutionary interest for unlawfully retained currency following searches.
GST seizure powers cannot be used to take cash as a general investigative measure or security for a possible tax demand. Currency is excluded from goods, and "things" is confined contextually to articles useful or relevant as evidence in GST proceedings. Valid seizure and retention require recorded statutory reasons, procedural compliance and observance of return timelines. Unauthorised retention engages property protections; later return does not cure the deprivation, and accrued interest is restitutionary rather than delayed-refund interest.
Case Laws Income Tax
Show AI Summary
Salary expense genuineness requires proof of actual services, business purpose, and fair testing of adverse third-party statements.
Under Section 37(1), salary expenditure is deductible only where it is actually incurred wholly and exclusively for business purposes and is supported by proof of genuine employment, services rendered, business nexus, and payment. Bank transfers and accounting entries alone are not conclusive. Where a third-party statement is central to an allegation of non-genuine salary, the taxpayer should receive disclosure and a meaningful opportunity to rebut it, including cross-examination where appropriate. A retracted and uncorroborated statement is vulnerable as the sole basis for disallowance.
Case Laws Income Tax
Show AI Summary
Discounted cash flow valuation remains taxpayer-selected under prescribed rules, while tax scrutiny must identify specific valuation-date defects.
The taxpayer may elect a prescribed DCF valuation for unquoted equity shares, and scrutiny of that method does not permit substitution with Net Asset Value merely because it produces a lower fair market value. The Assessing Officer may examine projections, discount rates, terminal assumptions, computations and source data, but rejection requires demonstrably wrong facts, material errors, a wholly erroneous basis or objectively unsupported assumptions. Subsequent financial performance cannot alone invalidate a bona fide DCF valuation; the relevant inquiry remains the reasonableness of valuation-date information.
Case Laws GST
Show AI Summary
Excess IGST on exports remains refundable when later correction triggers automated refund and reconciliation proves duplicate payment.
Refund of excess IGST paid on zero-rated exports may arise where turnover and tax are mistakenly entered under non-zero-rated supplies in FORM GSTR-3B while export invoices and shipping bills are correctly reported in FORM GSTR-1. If the exporter then pays the same IGST in the correct zero-rated field and the automated refund is credited against that later payment, the earlier payment remains a separately identifiable potential excess; its claim is not a repeat request for the same export-tax refund.
Case Laws GST
Show AI Summary
GST registration revocation requires timely application, return compliance, payment of dues, and a reasoned statutory decision.
GST registration revocation after cancellation for return default is a conditional, time-bound process. An application under Section 30 and Rule 23 must ordinarily be filed within ninety days, subject to prescribed extension, and cannot be made until pending returns are filed and tax, interest, penalty and late fee are paid. Portal non-acceptance may permit online or physical submission where technically unavailable, but does not condone delay or ensure revocation. The competent authority must assess statutory eligibility, sufficient grounds and compliance while following notice and hearing requirements before rejection.
Case Laws Income Tax
Show AI Summary
Reassessment limitation under TOLA requires final notices to issue within surviving time and satisfy statutory safeguards.
Reassessment limitation under TOLA is a jurisdictional restraint. Transitional notices issued between 1 April 2021 and 30 June 2021 are treated as Section 148A(b) show-cause notices, but only the surviving time remaining until 30 June 2021 is available for completing the reassessment process. Periods for supply of material and the assessee's response are excluded, but the Section 148A(d) decision, statutory approval and final Section 148 notice must issue within the remaining period. For Assessment Year 2015-16, post-1 April 2021 notices are treated as time-barred.
Case Laws Customs
Show AI Summary
Unseized food consignments cannot face indefinite detention without lawful seizure, valid sampling, and prompt assessment.
Provisional release of an unseized imported food consignment is not mechanically governed by Section 110A, which applies to goods seized under Section 110. Customs may examine, test, verify and reassess imports, but indefinite retention without a seizure memorandum or disclosed reasons connecting the goods with confiscation is not justified. Food sampling should follow the specialised food-safety process through an authorised officer. A valid food-safety report may support conditional clearance, while classification, duty liability, confiscation and adjudication remain open. Revenue may be protected through proportionate security.
Case Laws Customs
Show AI Summary
Anti-dumping duty recovery permits post-clearance demands and consequential import IGST where self-assessment omitted an applicable levy.
Unpaid anti-dumping duty omitted during self-assessment may be pursued through the customs recovery procedure without prior appellate modification of the self-assessment. The recovery framework applies to anti-dumping duty through statutory incorporation of provisions concerning assessment, non-levy, short-levy, interest and recovery. Where anti-dumping duty is chargeable, it forms part of the aggregate value used to compute IGST on imports, potentially creating a consequential IGST short-payment. Recovery requires accurate assessment of notification coverage, product, origin, rate, valuation, limitation and procedural safeguards.
Case Laws GST
Show AI Summary
Project-wise anti-profiteering requires actual input tax credit measurement and area-based allocation of benefits to real-estate purchasers.
Real-estate anti-profiteering under Section 171 requires project-level identification of additional input tax credit and allocation of the saving across total project area on a per-square-foot basis. Purchase value may quantify credit attributable to project expenditure, but turnover or collections cannot serve as the allocation basis. The comparison must use pre-GST credit actually availed rather than merely available credit. GST collected on consideration inflated by an undistributed benefit forms part of the amount not passed on and remains distinct from statutory interest.
Case Laws Income Tax
Show AI Summary
Retirement leave encashment exemption applies under the enhanced notified ceiling while preserving non-government employee classification and statutory conditions.
Section 10(10AA)(ii) governs retirement leave-encashment exemption for non-Government employees, subject to the ten-month earned-leave measure, average-salary computation, and the notified monetary ceiling. Notification No. 31/2023 specifies an enhanced ceiling of Rs. 25,00,000, is deemed effective from 1 April 2023, and certifies that retrospective effect causes no adverse effect. The enhanced ceiling is treated as a remedial rationalisation of an existing exemption and may govern pending earlier-period matters, while preserving the distinction between Government and non-Government employees.
Case Laws GST
Show AI Summary
Transit GST jurisdiction limits detention penalties for documented inter-State supplies lacking a local taxable nexus.
Transit-State jurisdiction under GST permits interception, document production, e-way bill verification and authorised physical inspection of goods moving through an intermediate State. It does not, in a pure transit movement, support detention-related penalty for an external inter-State supply where origin and destination lie outside the intercepting State, no tax is payable there, and there is no evidence of diversion, local supply, fictitious or mismatched documents, or mismatch of goods. Cross-empowerment is administrative and does not create an independent territorial taxable nexus.
Case Laws SEBI
Show AI Summary
Shareholder ratification cannot cure preferential-issue fund diversion when disclosed objectives are abandoned, triggering securities-market fraud and disclosure concerns.
Post-facto shareholder approval cannot retrospectively validate diversion of preferential-issue proceeds contrary to issue-specific objects disclosed to shareholders and the market. A special resolution authorises the issue but does not permit unrestricted use of proceeds. Periodic deviation reporting, audit-committee review and utilisation disclosures promote transparency; they do not enable diversion followed by later regularisation. Immediate diversion, inadequate commercial justification and missing documentation may indicate that disclosed objects were not genuinely intended to be performed. Later amendment of corporate objects or shareholder ratification cannot cure a completed securities-market disclosure breach.
Case Laws Income Tax
Show AI Summary
Cross-border software payments require copyright-right, technical-service, and permanent-establishment analysis before withholding obligations are determined under applicable treaties.
Section 195 requires withholding only from a remittance to a non-resident that includes income chargeable in India. For software, royalty depends on transfer of copyright rights, not merely the right to install, access, use, or distribute a copyrighted article under restrictive terms. Where a DTAA is more beneficial, its royalty and FTS definitions control; treaty FTS may require technology to be made available. Amounts that are neither royalty nor FTS require consideration as business profits, ordinarily taxable only where profits are attributable to a permanent establishment. Composite payments require component-wise allocation and analysis.
Case Laws GST
Show AI Summary
Personal GST penalty requires proof that the beneficiary retained benefit and directed a covered invoice or credit transaction.
Section 122(1A) may impose personal GST penalty on a registered or unregistered person only for a covered invoice or input tax credit transaction. Liability requires cumulative proof that the individual retained an identifiable personal benefit and that the transaction was conducted at that person's instance. Directorship, employment, registration, signature authority, or association with the taxable entity neither independently establishes nor excludes liability. Proceedings require transaction-specific and person-specific allegations and findings. The provision operates prospectively for underlying acts or transactions occurring on or after 01.01.2021.
Case Laws IBC
Show AI Summary
Proof of tenancy rights governs insolvency recovery of corporate-debtor premises from occupants lacking enforceable possessory interests.
Where premises form part of the corporate debtor's assets, Sections 18 and 25 of the Insolvency and Bankruptcy Code, 2016 require the resolution professional to take custody, control, preservation and protection measures. An occupant resisting recovery must prove a subsisting tenancy, leasehold interest or enforceable licence through reliable evidence of the parties' intended relationship and its essential terms. Permission to stock goods or conduct limited business activity, prolonged occupation, and business or utility records do not independently create rights in the premises. Section 60(5)(c) supports insolvency jurisdiction over asset-recovery measures connected with the insolvency estate.
Case Laws GST
Show AI Summary
GST portal service requires statutory validity and practical accessibility before ex parte adjudication can fairly proceed.
GST portal service is a statutory method under Section 169, but its use in an ex parte demand proceeding depends on effective accessibility and a meaningful opportunity to reply and be heard. Rule 142 requires electronic DRC-01 and DRC-07 summaries to operate alongside the underlying show-cause notice and reasoned order. Portal placement, complete communication, e-mail transmission, technical reliability and proof of actual access may determine whether service is effective, whether waiver applies, and whether appellate limitation begins.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Comparison of section 423 "Interest for defaults in furnishing return of income." between the Income-Tax Act, 2025 (as passed) and the Income-Tax Bill, 2025 (as originally introduced)

15 September, 2025

Contents
Acts
Rules & Regulations
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Section 423 Interest for defaults in furnishing return of income.

Income-tax Act, 2025

At a Glance

Document compared: Section 423 of the Income-tax Act, 2025 (as appearing in the enacted Act) and Clause 423 of the Income Tax Bill, 2025 (Old Version) (the Bill text supplied). Both texts deal with interest for defaults in furnishing return of income. The provisions affect taxpayers required to furnish returns, and the income-tax department in calculating and demanding interest. Effective date or decision date: Not stated in the document.

Background & Scope

Statutory hook: Clause 423 in the Income Tax Bill, 2025 - Old Version (hereinafter "Clause 423 (Bill)"). Subject matter: interest chargeable for defaults in furnishing return of income. Coverage: outlines when simple interest at the rate implicit in the formula I = 1% x A x T becomes payable, defines the starting and ending dates for computation across specified circumstances, prescribes treatment where post-assessment orders alter tax, and defines components included in "tax paid". Definitions or explanations provided in the text: limited to the formula and the Table; the Bill supplies a definition of "tax paid" in sub-section (4)(d) with enumerated items (i)-(vii). No separate definitions section is provided.

Statutory Provision Mode

Text & Scope

Clause 423 imposes simple interest for defaults in furnishing a return of income. The interest is computed by the formula I = 1% x A x T, where A is the "amount of tax on which interest is payable" (as specified in sub-section (2)) and T is the number of months comprised in the period commencing on the day after the "starting date" and ending on the "ending date" specified in the Table. Sub-section (2) contains a Table that maps specific circumstances to starting date, ending date and the tax base (A) for interest computation. The Table covers four scenarios: (1) return furnished u/s 263(1), (4) or (6) or in response to a notice u/s 268(1) after the due date; (2) no return furnished under the said sections; (3) return required by a notice under an unspecified section issued after certain determinations and furnished late; and (4) where such a notice requires a return and no return is furnished. Sub-section (3) deals with the consequence of orders (under a list of sections) that increase or reduce the tax base for interest, prescribing issuance of notice of demand in prescribed form where interest increases, and refund of excess interest where interest is reduced. Sub-section (4) contains qualifying notes, including exclusions of additional income-tax u/s 267 from the tax bases, reduction of interest payable by amounts of interest paid u/s 266, and the detailed meaning of "tax paid". Sub-section (5) treats an assessment made for the first time u/s 279 as a "regular assessment" for purposes of the section.

Interpretation

Legislative intent as indicated by the Bill text: to provide a simple, uniform interest formula for late or non-furnishing of returns and to tie the interest computation periods to concrete events (due date, date of furnishing, date of completion of assessment, dates specified in notices). The Table-driven approach indicates an intent to vary the tax base (A) and the start/end dates according to factual circumstances of how and when returns are filed or not filed. The inclusion of a detailed "tax paid" definition shows an intent to net off various prepayments and credits from the tax base when computing interest. The provision for adjustment upon post-assessment orders (sub-section (3)) manifests an intent to align interest levies with the final assessed tax position.

Exceptions/Provisos

Carve-outs or qualifications present in the Bill include:

  • Exclusion of additional income-tax u/s 267 from the tax base (4)(a)-(b).
  • Reduction of interest payable by interest already paid u/s 266 (4)(c).
  • Specific items constituting "tax paid" (4)(d)(i)-(vii), which serve as offsets against the tax base for interest calculation.
  • Where an assessment is made for the first time u/s 279, it is to be regarded as a regular assessment (5).

Illustrations

  • Example 1: A return filed late in response to a notice u/s 268(1). Starting date is the due date u/s 263(1); ending date is date of furnishing; A is tax on total income as determined u/s 270(1) (if regular assessment not made) or tax determined under regular assessment, reduced by "tax paid". (All other specifics of amounts and dates Not stated in the document.)
  • Example 2: No return furnished in response to a notice u/s 268(1). Starting date is due date u/s 263(1); ending date is date of completion of assessment u/s 271; A is tax on total income determined under regular assessment reduced by "tax paid". (Concrete amounts and computation Not stated in the document.)
  • Example 3: Return required by a notice (serial number 3) but furnished after expiry of time allowed under such notice. Starting date is the date immediately following the last date of time allowed under such notice (Bill text); ending date is date of furnishing; A is amount by which reassessed tax exceeds earlier tax. (The Bill text contains an omission in the cross-reference to the notice section; specifics Not stated in the document.)

Interplay

The Bill text expressly references multiple other provisions (sections 263, 268, 270, 271, 279, 280, 266, 267, 287, 288, 289, 359, 363, 365(10), 368, 377, 378, 206). Interplay with those provisions is central to determining starting/ending dates, the tax base (A), and credits. The Bill, as supplied, contains at least one omitted cross-reference (a missing section number in the Table at serial number 3) and a differing cross-reference for the tax credit clause (206(13) vs the multi-paragraph references in the Act). These differences create potential interpretive issues and could require reconciliation with the substantive provisions of the referenced sections; however, the content of those referenced sections is Not stated in the document.

Differences between the two provisions and practical impact

  • Starting date for notice-required returns (serial numbers 3 and 4): The enacted Section 423 (Act) uses "The last date of time allowed under such notice" as the starting date for serial numbers 3 and 4. The Clause 423 of Bill (Old Version) uses "Date immediately following the last date of time allowed under such notice" (for both serial numbers 3 and 4 in the Bill).
    • Practical impact: shifting the stated starting date by one day will change the counted months (T) in the formula I = 1% x A x T in some cases; whether the difference produces a material change depends on the method of counting months under the section (not further specified in the documents). It can lead to one additional month being counted in some interpretations, thereby increasing interest liability slightly in some cases.
  • Row 3 starting date wording: In the Act text, for serial number 3 the Starting date is "The last date of time allowed under such notice." The Bill text, for serial number 3, states "Date immediately following the last date of time allowed under such notice."
    • Practical impact: same as above; potential to alter the period used for interest computation.
  • Omissions/typographical differences affecting clarity: The Bill's Table entry for serial number 3 contains an apparent omission - "Where return of income is required by a notice u/s issued after..." (the section number is missing). The Act provides the relevant contextual references (Act shows section 280 in related contexts).
  • Practical impact: omission creates ambiguity in the Bill text about which notice provision is referred to; this could cause interpretive uncertainty unless corrected. The Act text does not exhibit that omission in the supplied extract.
  • "Tax paid" definition - tax credit cross-references: The Act's clause (4)(d)(vii) defines "tax paid" to include "any tax credit allowed to be set off as per sections 206(1)(m) to (p) and 206(2)(e) to (h)." The Bill (Old Version) substitutes "(vii) any tax credit allowed to be set off as per section 206(13)."
    • Practical impact: this is a substantive difference in cross-references. If the Bill's singular reference is intended to capture the same set of credits, the drafting does not make that clear. Depending on the actual content of section 206 in the statute (not stated in the document), taxpayers may lose (or gain) certain credits being treated as "tax paid" for interest computation. As the document supplied does not state the content of section 206, the practical effect cannot be fully determined from the text alone.
  • Form of notice of demand: Sub-section (3)(a) in the Act reads "in such form as may be prescribed"; the Bill reads "in the form as prescribed."
    • Practical impact: stylistic/minor drafting difference; both phrases point to prescribed form, but "such form as may be prescribed" is the more conventional legislative formulation. No clear substantive impact in isolation.
  • Other structural/wording differences: Minor variations in punctuation, paragraphing and referential phrases occur across the two texts (for example, use of "the Assessing Officer shall serve on the assessee a notice of demand in such form as may be prescribed specifying the sum payable" vs "shall serve on the assessee a notice of demand in the form as prescribed specifying the sum payable").
    • Practical impact: primarily drafting and clarity; no express substantive change beyond the items noted above based on the supplied texts.

Practical Implications

  • Compliance and risk areas: The precise starting date language (whether the last date of time allowed or the day after that date) will affect calculation of months (T) - which could increase or decrease interest by the formula provided. Taxpayers filing in response to notices should be alert to how the start date is to be computed. Where the Bill's cross-references differ (notably to section 206), taxpayers should verify which tax credits count as "tax paid" for interest computations - the Bill text introduces uncertainty. The omission of a section number in serial number 3 may create avoidable disputes until corrected.
  • Record-keeping/evidence points: The text makes clear that dates of notices, dates of furnishing of returns, dates of completion of assessments and amounts of tax determined at various stages are determinative items. Parties should maintain contemporaneous records showing notice dates, time allowed under notices, dates of filing, assessments and any payments or credits claimed (details of records to be kept Not stated in the document).

Key Takeaways

  • Clause 423 (Bill) applies a simple interest formula I = 1% x A x T for defaults in furnishing returns, tying the interest period to specific starting and ending events listed in a Table.
  • There are material drafting differences between the Bill and the enacted Section 423: notably in the exact stated starting dates for notice-driven cases and in the cross-references used to define tax credits included as "tax paid".
  • Shifts in starting date wording (last date vs date immediately following) can alter interest months counted and thus interest liability; the Bill language tends to state the day after, potentially increasing periods in some views.
  • The Bill text contains an omission (missing section reference in serial number 3 of the Table) creating interpretive ambiguity that requires correction or legislative clarification.
  • The Bill lists prescribed mechanisms for adjustment where post-assessment orders alter tax and requires notice of demand or refund accordingly.
  • The provision for reduction of interest by interest already paid u/s 266 and the detailed enumeration of items constituting "tax paid" show an intent to prevent double charging and to net prepayments and credits.

Full Text:

Section 423 Interest for defaults in furnishing return of income.

Topics

Acts Income Tax