Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Wrong-Head GST Payment and the Distinction Between Appropriation and Refund Under Sections 19 and 77
    Condonation of Delay in GST Appeals under Section 107: Statutory Limits and Writ Jurisdiction
    Case Laws Income Tax
    Validity of Scrutiny Notice under Section 143(2) and Non-Conformity with CBDT-Prescribed Formats
    Case Laws Income Tax
    Article 8 of the India-UK DTAA and Taxability of Ground Handling and Engineering Service Receipts
    Cancellation of GST Registration for Continuous Non-Filing of Returns under Section 29 and Rule 22
    Finality of Approved Resolution Plans and Extinguishment of Pending Operational-Creditor Claims unde...
    Case Laws Customs
    Interest on Refund of Amounts Deposited under Protest during Customs Investigation
    Case Laws Indian Laws
    Admitted Cheque Signature and Presumption of Legally Enforceable Debt under Sections 118 and 139 of ...
    Case Laws Customs
    Principal Function, Network Capability and Customs Classification of Composite Electronic Devices (G...
    Case Laws Income Tax
    Enhanced Tax Rate Under Section 115BBE for Financial Year 2016-17: Classification of Unexplained Inc...
    Case Laws Income Tax
    Retrenchment Compensation under Section 10(10B) and Leave Encashment Exemption under Section 10(10AA...
    Case Laws Income Tax
    Renewal of Registration under Section 12AB for Charitable Hospitals Engaged in Medical Relief: Retro...
    Contractual Reimbursement of Incremental GST on Works Contracts and the Statutory-Contractual Divide
    Case Laws Customs
    Waiver of Late Fee on Supplementary Bills of Entry under Section 46(3) of the Customs Act, 1962: Exc...
    Detention and Confiscation of Inter-State Consignments: Territorial Limits on State GST Officers - J...
    Common Show Cause Notices across Multiple Financial Years: Scope of Sections 73 and 74 and Limitatio...
    Input Tax Credit Eligibility under the CGST Act: Supplier Tax Non-Payment and Recipient ITC Claims: ...
    Actionable Claims, Contingent Winnings and Gross Valuation in GST on Gaming Transactions
    Invocation of Extended Limitation under Section 74 of the CGST Act: Foundational Facts, Prima Facie ...
    Assignment of Leasehold Rights in Industrial Plots under the CGST Act: Distinguishing Lease Services...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
Wrong-head GST payments require appropriation of timely discharged liability, while supply-characterisation errors follow the statutory refund framework.
Wrong-head GST payment must be distinguished from a substantive error in classifying a supply as inter-State or intra-State. Sections 19 and 77 address supplies subsequently held to have a different character and do not automatically govern a mere allocation error where the supply classification and aggregate tax liability are undisputed. Where the full aggregate liability was remitted within time under an incorrect tax head, correction may occur through appropriation against the correct heads rather than a second payment followed by a refund claim.
Case Laws GST
Show AI Summary
GST appeal limitation strictly confines statutory condonation; exceptional writ review may address defective communication and lost merits hearings.
Section 107 requires a GST appeal within three months from communication of the order and permits condonation only for a further one-month period on sufficient cause. This is a statutory outer limit on the Appellate Authority, which cannot be enlarged through Section 5 of the Limitation Act. Communication through the portal, post or other recognised modes may require factual scrutiny where effective access to the complete order is disputed. Article 226 may exceptionally examine manifest injustice arising from defective communication, prompt action after knowledge, absence of merits adjudication and other credible circumstances, without enlarging the Appellate Authority's statutory jurisdiction.
Case Laws Income Tax
Show AI Summary
Scrutiny notice validity turns on statutory compliance and prejudice, not omission of an administrative scrutiny classification.
Validity of a scrutiny notice under section 143(2) depends on statutory compliance, not merely on use of a prescribed administrative format. A notice remains effective where it is issued by a competent authority, timely served, identifies the taxpayer and assessment year, conveys scrutiny, and affords an opportunity to support the return. Section 292B may cure formal defects where the notice substantively conforms to the Act and no actual prejudice is established. This issue is distinct from the restriction that limited-scrutiny inquiries cannot be expanded without prescribed conversion safeguards.
Case Laws Income Tax
Show AI Summary
Article 8 treaty protection excludes independent third-party ground handling and engineering receipts lacking a direct transportation nexus.
Article 8 of the India-UK DTAA confines protection to profits derived from treaty-defined international aircraft operations and qualifying participation in air-transport pools. Engineering and ground-handling services supplied to other airlines are independently organised commercial services where they lack a direct nexus to the enterprise's own international transportation. A qualifying pool requires substantive evidence of its legal and commercial structure, including reciprocal arrangements and settlement mechanisms; industry arrangements or aviation-sector relevance alone are insufficient.
Case Laws GST
Show AI Summary
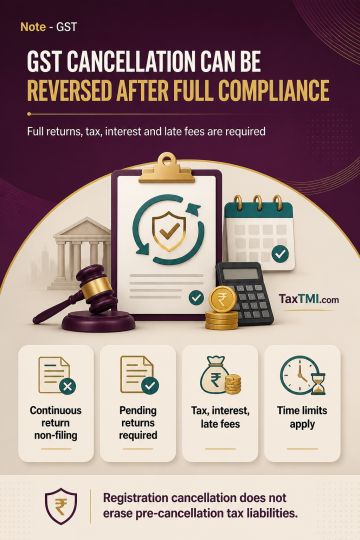
GST registration cancellation for return default remains reversible only through complete, time-bound filing and payment compliance.
GST registration may be cancelled for continuous non-filing of returns, but cancellation does not discharge pre-cancellation tax liabilities. Before cancellation, Rule 22(4) requires proceedings to be dropped where the taxpayer files all pending returns and pays tax, interest and late fee. Post-cancellation revocation under Rule 23 is a separate mechanism requiring complete filing and payment compliance within the applicable time limits. Conditional restoration may be appropriate where liabilities are fully regularised, while absence of fraud does not excuse default or replace statutory compliance.
Case Laws IBC
Show AI Summary
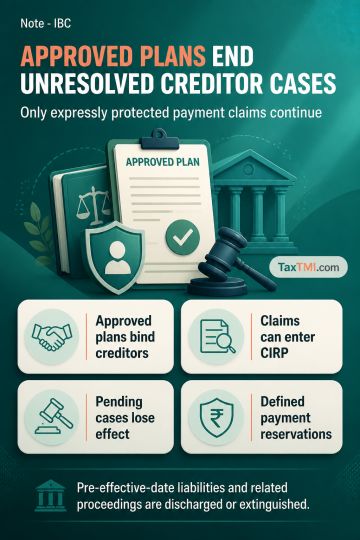
Resolution-plan finality extinguishes unresolved operational-creditor proceedings unless the plan expressly preserves liability and payment rights.
Finality of an approved resolution plan fixes the treatment of corporate-debtor liabilities and binds creditors within the corporate insolvency resolution process. A disputed or unadjudicated right to payment may be submitted as a claim during CIRP, but does not independently preserve civil or arbitral proceedings after plan approval. Where the final claims list and the plan provide for discharge of pre-effective-date liabilities and extinguishment of related proceedings, unresolved operational-creditor claims survive only if the plan expressly preserves them through a defined payment or reservation mechanism.
Case Laws Customs
Show AI Summary
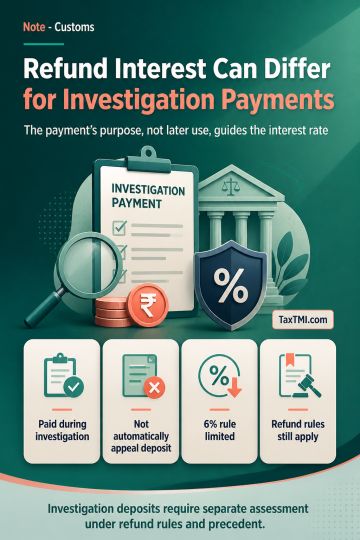
Investigation deposits: refund interest may differ from statutory appellate pre-deposit interest when the underlying demand fails.
Interest on the refund of amounts deposited under protest during a customs investigation depends on the legal character of the payment, rather than its later appropriation towards a differential-duty demand. An amount paid pending investigation does not become a statutory appellate pre-deposit merely because part of the overall payment is treated as a pre-deposit for appeal purposes. The rate fixed at 6% for Section 129EE is confined to amounts deposited under Section 129E, while an investigation deposit requires assessment under the applicable refund framework and binding jurisdictional precedent.
Case Laws Indian Laws
Show AI Summary
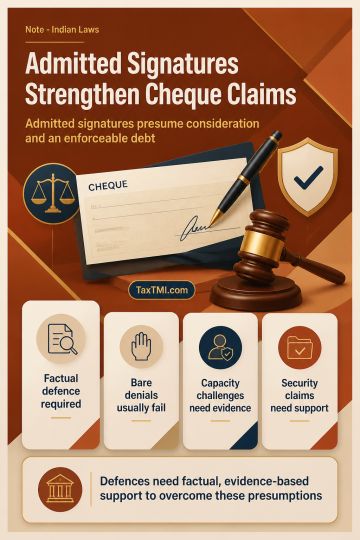
Admitted cheque signatures trigger presumptions of consideration and enforceable debt, requiring evidence-based probable defences in dishonour proceedings.
Once execution of a cheque is admitted or proved, consideration must be presumed and the holder must be presumed to have received the cheque towards discharge, wholly or partly, of a legally enforceable debt or other liability. The drawer may rebut these presumptions on a preponderance of probabilities, but the defence must have a factual foundation. Bare denials, unsupported misuse allegations, and blank-cheque or security-cheque assertions ordinarily do not displace the presumptions. Financial capacity becomes material only upon a credible, specific, and evidence-based challenge.
Case Laws Customs
Show AI Summary
Bluetooth headset classification turns on active wireless network communication, not audio form, when determining principal function and essential character.
Bluetooth-enabled personal audio devices are classified by objective technical function rather than wearable form, product label, audio output or microphone. Heading 8517 applies where Bluetooth capability makes the device an active wireless-network apparatus that receives, converts and transmits voice or data; heading 8518 covers ordinary headphones or earphones carrying only audio signals. Classification begins with the heading terms and relevant notes, with essential character and principal function applied only through the sequential General Rules where competing headings remain.
Case Laws Income Tax
Show AI Summary
Unexplained-income taxation requires valid deeming classification, while enhanced special rates apply prospectively under the stated effective-date framework.
Section 115BBE applies only where income is validly assessed under the deeming provisions for unexplained income; a surrender, disclosure or addition alone is insufficient. The assessing authority must identify the relevant provision and reject the explanation of nature and source where required. The special computation denies deductions, allowances and loss set-off against qualifying income. The Rajasthan High Court treated the enhanced rate introduced with effect from 1 April 2017 as prospective, preserving the earlier rate for financial year 2016-17. Penalty under section 271AAC depends on a valid section 115BBE determination.
Case Laws Income Tax
Show AI Summary
Substance-over-form treatment of VRS compensation can place retrenchment-linked payments within the distinct full-exemption framework for approved workforce reduction schemes.
Tax treatment of VRS-labelled separation payments depends on their substantive character. Payments connected with Government-supported workforce restructuring may qualify as retrenchment compensation under section 10(10B), rather than as voluntary-retirement compensation under section 10(10C), where the special-protection requirements are satisfied. Leave encashment must be examined separately under section 10(10AA), according to employee status and the applicable conditions or notified limit. Settlement components should be segregated and supported by scheme documents, approvals, computations, and tax records.
Case Laws Income Tax
Show AI Summary
Charitable hospital renewal depends on genuine medical relief, charitable application of income, and material regulatory compliance.
Renewal of section 12AB registration for a charitable hospital depends on genuine activities in furtherance of medical relief, application of income and assets to charitable objects, and compliance with other laws only where material to those objects. Receipts, premium facilities, tariff differentials, sophisticated infrastructure and professional management do not alone negate charitable status. Other-law non-compliance requires attention to the specified-violation framework and competent regulatory determinations. Retrospective cancellation is distinct from refusing renewal and requires an independent statutory and factual foundation, with reasonable opportunity of hearing.
Case Laws GST
Show AI Summary
Contractual GST reimbursement in works contracts depends on tax-risk clauses and cannot alter statutory compliance obligations.
GST liability for a works contractor is governed by statute, while reimbursement of incremental GST from an employer depends on the contract's allocation of tax risk. An inclusive-tax clause must be read with change-in-law, price-adjustment, tender and amendment terms. Contract-wise reconciliation of pre-transition and post-transition work may support a supplementary agreement and revised GST-inclusive value where contractual entitlement exists. It cannot alter statutory valuation, return, limitation, interest or penalty requirements, which remain governed by GST law.
Case Laws Customs
Show AI Summary
Sufficient cause for delayed supplementary Bills of Entry requires a reasoned waiver assessment, not automatic system-generated late charges.
Late-presentation charges under Section 46(3) require the proper officer to be satisfied that no sufficient cause existed for delayed filing. Regulation 4(3) prescribes the late-charge framework and permits waiver where the reasons for delay are satisfactory. A delayed supplementary Bill of Entry for excess cargo is not automatically liable or automatically exempt; the assessment depends on timely original filing, linkage of the excess cargo to the same consignment, prompt amendment efforts, absence of importer fault, bona fides and duty compliance. Electronic calculation cannot substitute for a reasoned determination on sufficient cause.
Case Laws GST
Show AI Summary
Territorial GST jurisdiction limits detention and confiscation of inter-State consignments when the intercepting State lacks fiscal nexus.
Physical presence of goods in an intermediate State therefore does not alone create authority to detain, seize, penalise or confiscate. Cross-empowerment is functional and taxpayer-linked, preserving the single-interface administrative structure without creating geographically unlimited enforcement power. Where verification establishes that both origin and destination lie outside the intercepting State, the officer may verify documents, identify and record apparent discrepancies, and communicate them to the proper officers of the consignor and consignee, but lacks coercive jurisdiction over a pure transit supply.
Case Laws GST
Show AI Summary
Consolidated GST show cause notices may cover multiple financial years, while each demand component remains independently subject to limitation.
Sections 73 and 74 do not expressly bar a common show cause notice covering multiple tax periods or financial years. The expressions "for any period" and "such periods" support consolidation, while financial-year references in the limitation provisions govern the deadline for adjudication orders rather than the scope of notice issuance. Each component demand must independently satisfy applicable limitation requirements. Section 74 requires disclosed material supporting fraud, wilful misstatement, or suppression of facts to evade tax; its extended limitation is not automatic.
Case Laws GST
Show AI Summary
Supplier tax payment remains a substantive input tax credit condition, requiring reversal and allowing re-availment after compliance.
Section 16(2)(c) of the CGST Act makes actual payment of tax to the Government a substantive condition for input tax credit. The conditions under Section 16(2) operate cumulatively, and invoice reflection, receipt of supplies, or supplier return filing do not independently establish tax payment. Section 41 requires reversal of credit where the supplier has not paid tax, with re-availment allowed after payment. Rule 37A prescribes reversal and re-availment where the supplier fails to furnish the corresponding GSTR-3B within the prescribed period.
Case Laws GST
Show AI Summary
GST valuation of stake-based gaming treats committed stakes as consideration for taxable actionable claims, irrespective of skill.
GST on stake-based gaming applies to the supply of actionable claims where money or money's worth is committed to an uncertain outcome in an organised betting or gambling arrangement. Skill in the underlying game does not remove the stake-based character of the transaction. Participants acquire contingent beneficial interests in pooled movable property, and committed stakes become consideration for participation. The platform is the supplier where it controls pooling, participation, gameplay and payouts. Gross stake valuation applies unless a statutory deduction is authorised, with specialised valuation mechanisms governing online gaming and casinos.
Case Laws GST
Show AI Summary
Extended GST limitation requires disclosed prima facie material linking tax shortfall to fraud, wilful misstatement, or suppression.
Section 74 permits extended GST limitation only where available material supports a rational prima facie view that a tax shortfall, erroneous refund or wrongful credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. Final proof is not required at initiation, but suspicion or bare statutory labels are insufficient. Prior scrutiny, audit, inspection or pre-notice communications may provide the factual foundation if actually communicated and linked to the notice. The notice and final order must preserve fair opportunity, disclose the material basis, and remain within the grounds stated.
Case Laws GST
Show AI Summary
Complete assignment of industrial leasehold rights can fall outside GST when it transfers the entire proprietary estate.
A complete assignment of an industrial lessee's entire leasehold interest, together with the building on the plot, is distinguished from leasing, renting, or sub-leasing. Where the assignor retains no reversionary interest or continuing right to earn rent, the consideration is for transfer of proprietary rights constituting benefits arising out of land. Schedule II classification of an original lease as a service does not govern the subsequent absolute assignment. Section 7(2), read with Schedule III, excludes a qualifying transfer of immovable-property benefits from the scope of supply.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Comparison of section 341 "Application of income." between the Income-Tax Act, 2025 (as passed) and the Income-Tax Bill, 2025 (as originally introduced)

11 September, 2025

Contents
Acts
Rules & Regulations
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Section 341 Application of income

Income-tax Act, 2025

At a Glance

Clause 341 of the Income Tax Bill, 2025 (Old Version) sets out what constitutes permissible application of income by registered non-profit organisations. It matters to charitable/religious trusts and registered non-profit organisations, and to tax authorities monitoring compliance with application-of-income conditions. Effective date/decision date: Not stated in the document.

Background & Scope

Statutory hook: Clause 341 of the Income Tax Bill, 2025 (Old Version) addressing "Application of income" of a registered non-profit organisation. Context: governs what sums may be treated as application of income for non-profit organisations to ascertain compliance with conditions for tax treatment. Coverage: sums applied for charitable/religious purposes in India, donations to other registered non-profits, corpus donations, reinvestment of corpus in permitted modes u/s 350, repayment of loans/borrowings, and exclusions. Definitions or further explanations: Not stated in the document beyond references to sections 35(b)(i), 36(4)-(7), and section 350.

Statutory Provision Mode

Text & Scope

Clause 341, Income Tax Bill, 2025 (Old Version) sets out what sums are to be allowed as "application of income" to a registered non-profit organisation. The provision identifies three categories in sub-section (1): (a) sums applied for charitable or religious purposes in India for which the organisation is registered (subject to payment during the tax year and allowability under specified sections), (b) 85% of donations made to other registered non-profit organisations, and (c) nil with respect to corpus donations to other registered non-profit organisations. Sub-section (2) includes reinvestments into permitted corpus modes and repayments of loans/borrowings within five years (subject to conditions including no prior violation and application post 31 March 2021) as application of income. Sub-section (3) excludes from application: depreciation/allowances claimed in respect of an asset acquisition already treated as application of income and set off/allowance of excess application from prior years. Sub-section (4) states that application from corpus, loan/borrowing, accumulated income, specified income or deemed accumulated income shall not be considered as application for the purpose of sub-sections (1) and (2).

Interpretation

The text links the concept of "application of income" to both timing (payment during the tax year) and substantive allowability u/ss 36(4)-(7) and 35(b)(i). Legislative intent apparent from the text is to restrict qualifying applications to sums that are both paid and allowable under income tax rules, and to avoid treating corpus transfers as qualifying applications. The Bill articulates a cross-reference approach whereby existing tax-law tests (sections 35 and 36 provisions) determine allowability. The inclusion of a prescribed percentage treatment for donations to other registered organisations (85%) indicates a legislative policy to permit a substantial portion of inter-charity donations to count as application while retaining a residual disallowance (15%).

Exceptions/Provisos

Explicit exceptions in the Bill text: corpus donations to other registered non-profit organisations are treated as nil for application purposes. Sub-section (3) excludes depreciation/allowances already claimed and set off of earlier excess applications. Sub-section (4) excludes application from corpus, loan/borrowing, accumulated income, specified income or deemed accumulated income for the purposes of sub-sections (1) and (2). There are conditional provisos in sub-section (2) requiring reinvestment or repayment within five years and that the original application from corpus or loan/borrowing be post-31 March 2021 and compliant with the Part.

Illustrations

  • Example 1 - Direct application: A registered trust pays Rs. 1,000,000 during the tax year for a charitable program for which it is registered, and the payment is allowable u/ss 36(4)-(7) and 35(b)(i). That sum would qualify as application of income under sub-section (1)(a).
  • Example 2 - Donation to another registered organisation: A registered society donates Rs. 100,000 to another registered society. Under sub-section (1)(b), 85% (i.e. Rs. 85,000) would count as application of income; under sub-section (1)(c) corpus components would count as nil if the payment is a corpus donation.
  • Example 3 - Reinvestment from corpus: Not stated in the document whether a trust that re-invests corpus within five years will satisfy other procedural prerequisites beyond those listed; the Bill requires reinvestment within five years and that the original corpus application be after 31-03-2021 with no violations. Specific permitted modes are referred to section 350 (modes) but details of those modes are Not stated in the document.

Interplay

The clause expressly refers to and depends upon sections 35(b)(i), 36(4)-(7) and section 350 for determining allowable payments and permitted modes of investment. It also cross-refers to "this Part" and corresponding provisions of the Income-tax Act, 1961 for compliance history. Specific rules, notifications or circulars beyond these textual cross-references are Not stated in the document.

Differences between the two provisions and practical impact

  • Explicit treatment of corpus donations paid to other organisations:

    • Bill (Clause 341, Document 2): sub-clause (1)(c) expressly states "nil, with respect to any sum paid as a corpus donation to any other registered non-profit organisation."
    • Act (Section 341, Document 1): sub-section (3)(c) provides that "any sum paid as a corpus donation to any other registered non-profit organisation" shall not be allowed as application of income (i.e., it is listed among claims not allowed).
    Practical impact: Both texts in effect disallow treating corpus donations to other registered entities as application of income, but the Bill states the position as a component of what is allowed (explicitly allowing "nil"), while the Act lists it among exclusions. Substance is similar; the Bill's expression is potentially clearer as a standalone rule, whereas the Act's placement in exclusions may be read as reinforcing general illegibility for application treatment.
  • Order and wording of paid sums qualifying as application:

    • Bill (Document 2): sub-section (1)(a) requires the sum be "paid during such tax year" and "such payment is allowable u/ss 36(4), (5), (6) and (7) and 35(b)(i)."
    • Act (Document 1): sub-section (1)(a) provides similar requirements but phrases them as "where such sum is paid during the tax year provided that the provisions of section 35(b)(i) and section 36(4), (5), (6), and (7) shall apply in respect of such sum."
    Practical impact: No substantive difference in the qualifying conditions; the Act's language places emphasis on the applicability of the identified sections, while the Bill is more prescriptive that payment during the year and allowability under those sections are required. Both link allowability u/ss 35/36 to qualification as application.
  • Deemed application (85% rule and deemed application mechanics):

    • Bill (Document 2): does not contain provisions comparable to Section 341(5)-(8) of the Act concerning the 85% of regular income requirement, shortfall treatment as deemed application, timing for application of deemed application, and exercise of option.
    • Act (Document 1): contains sub-sections (5)-(8) establishing an 85% regular income normative target, permitting registered organisations to elect to treat shortfall as deemed application, specifying timing rules for application, and prescribing exercise of option on or before the due date u/s 263(1) for furnishing return of income.
    Practical impact: The Act introduces a compliance mechanism (85% of regular income) and a deemed application regime with procedural timings. The Bill version lacks this constructive mechanism; therefore, under the Bill an organisation's failure to apply regular income to the extent of 85% would not be remedied by deeming (unless other provisions exist elsewhere). The Act increases formal compliance burdens and provides a remedy (option) to treat shortfall as application within specific timelines; omission from the Bill means those procedural obligations/benefits are not present in the Bill text as reproduced.
  • Capital gains treated as application:

    • Bill (Document 2): contains no counterpart to the Act's sub-sections (9) and (10) dealing with capital gains from transfer of capital assets held for charitable or religious purposes and definitions such as "appropriate fraction," "cost of transferred asset," and "net consideration."
    • Act (Document 1): specifies when capital gains on transfers of trust property are deemed application (full or fractional amounts) and provides definitions for key terms used in that analysis.
    Practical impact: The Act creates a clear statutory rule treating certain capital gains as application of income when proceeds are reinvested in qualifying capital assets; the Bill lacks such rules, leaving potential ambiguity regarding tax treatment of capital gains arising to trusts. The Act's rules may aid in tax neutrality for reinvestment of trust assets; absent that, the Bill would leave organisations reliant on other provisions or administrative guidance.
  • Express exclusions and structuring differences:

    • Bill (Document 2): The exclusions list in sub-section (3) comprises clauses (a) and (b) (depreciation/allowance previously claimed as application; set off of excess application), but does not include clause (c) of the Act (which there is included in Act sub-section (3)(c)).
    • Act (Document 1): explicitly includes three exclusions (a), (b), (c) in sub-section (3), making the treatment of corpus donations as excluded clearer within the exclusions list.
    Practical impact: The Act's exclusions list is more exhaustive. The Bill's omission (as presented) could cause interpretive uncertainty until clarified by other provisions or parliamentary amendments.

Practical Implications

  • Compliance and risk areas: The requirement that payments be "paid during such tax year" and be allowable under the cross-referenced sections imposes evidentiary and timing burdens on registered non-profit organisations to substantiate payments and their tax allowability. The 85% rule for donations to other registered entities creates a mathematical step for accounting and tax reporting; organisations must track whether payments are corpus or non-corpus to determine whether 85% or nil applies.
  • Record-keeping/evidence: Organisations will need contemporaneous payment evidence (ledgers, bank payment instruments), documentation demonstrating allowability u/ss 35/36, clear characterisation of donations as corpus or revenue, and records of repayments or reinvestments into permitted modes (section 350) within five-year periods where applicable. The Bill's five-year windows and post-31-03-2021 condition require maintenance of historical compliance records showing no violations.

Key Takeaways

  • Clause 341 defines what counts as application of income for registered non-profit organisations, linking allowability to sections 35 and 36 and to timing of payment.
  • Donations to other registered organisations are partly recognised (85%) except corpus donations which are expressly treated as nil.
  • Reinvestment into permitted corpus modes and repayment of loans may be treated as application if made within five years and subject to compliance conditions and post-31-03-2021 applicability.
  • Certain claims (depreciation/allowances already claimed as application; set off of earlier excess application) are excluded from being treated as application.
  • The clause depends on other provisions (sections 35, 36 and 350) for definitions and modalities; practical compliance requires careful recordkeeping.
  • Compared with the enacted Section 341, the Bill (old version) omits the deemed-application (85% regular income) mechanism and capital-gains-deemed-application rules present in the Act.

Full Text:

Section 341 Application of income

Topics

Acts Income Tax