Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Case Laws Income Tax
    TNMM Comparability: Operating Items, Search Matrix and Functional Analysis under Rule 10B
    Case Laws Customs
    Validity of Gold Seizure under Section 110 and the Conditional Reverse Burden under Section 123 of t...
    Case Laws Income Tax
    Deduction under Section 80GGC: Genuineness of Political Contributions and Evidentiary Burden
    Post-Death Determination of GST Liability and Estate-Limited Recovery from Legal Heirs
    Non-Confirmation of Seizure under Section 37A of FEMA and the Requirement of Recorded Reasons to Bel...
    Case Laws Companies Law
    Oppression and Mismanagement Proceedings under Sections 241 and 242: Corporate Authority During Pend...
    Case Laws Benami Property
    Benami Claims in Self-Acquired Property: Rejection of Plaint and the Limits of the Fiduciary-Capacit...
    Case Laws Income Tax
    Reopening of Assessment under Sections 147 and 148: Reason to Believe, Tangible Material and Change ...
    Case Laws Income Tax
    Penalty under Section 270A on Disallowance of Political Donation Deduction under Section 80GGC
    Case Laws Income Tax
    Conditional Registration under Section 12AB and the Limits of Commissioner's Statutory Powers
    Case Laws Customs
    Transaction Value, Rule 12 and Enhancement Based on Consent Letters in Customs Valuation: Limits of ...
    GST on Assignment of Leasehold Rights: Distinguishing Transfer of Immovable Property from Supply of ...
    Case Laws Income Tax
    Leave Encashment Exemption for Non-Government Employees under Section 10(10AA)(ii) and the Enhanced ...
    Case Laws Income Tax
    Dependent Agent Permanent Establishment under Article 5(5) of the India-Switzerland DTAA: Authority,...
    Case Laws Customs
    Proper Officer Jurisdiction for Customs Show Cause Notices under Sections 2(34), 17, 28 and 124
    Case Laws Money Laundering
    Provisional Attachment of Pre-Offence Property as Proceeds of Crime or Equivalent Value under the PM...
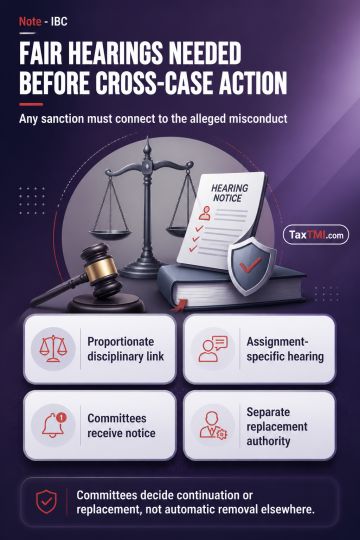
    Disciplinary Suspension of Resolution Professionals Across Ongoing CIRPs: Proportionality, Hearing a...
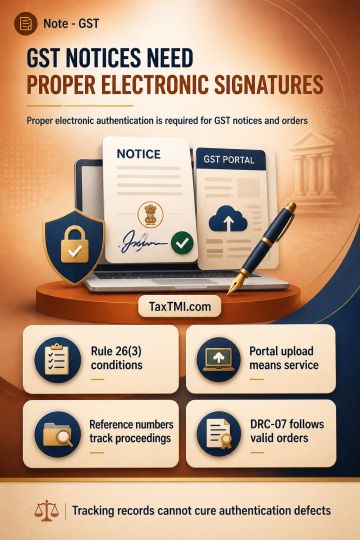
    Electronic Authentication of GST Demand Proceedings: Rule 26(3), Sections 75, 160 and 169
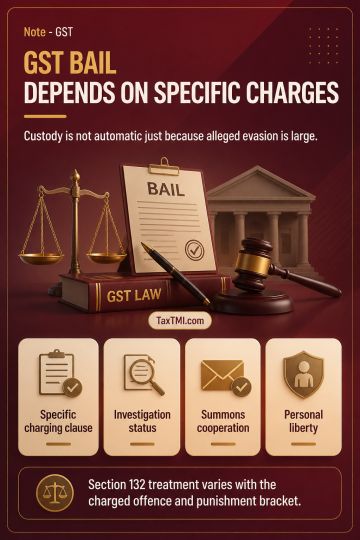
    Large-Scale GST Evasion Prosecutions: Cognizable and Non-Bailable Classification under Section 132 a...
    Case Laws Customs
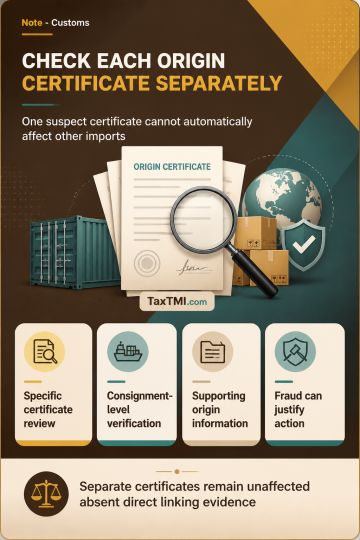
    Country of Origin Certificates and Preferential Customs Duty under Notification No. 46/2011-Customs ...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws Income Tax
Show AI Summary
TNMM comparability requires consistent operating-cost treatment and FAR-based selection, while search matrices cannot replace evidence-led functional analysis.
TNMM requires consistent computation of operating profit and operating cost for the tested party and comparables. A provision for doubtful debts connected with sales and trade receivables may be an operating expense, as may routine business levies; income-tax on profits remains excluded. A search matrix is a disciplined evidentiary tool, not a statutory bar to an out-of-matrix comparable. Inclusion requires proof of functional fit, filter satisfaction and reasons for its absence, while rejection cannot rest solely on matrix absence. FAR analysis, segmental reliability and material scale differences govern comparability.
Case Laws Customs
Show AI Summary
Reasonable belief in gold seizure requires recorded objective grounds before the reverse burden for smuggling can arise.
Gold seizure under Section 110 requires the proper officer to hold, before seizure, objectively supportable reasons to believe that goods are liable to confiscation. For gold, Section 123 shifts the burden of disproving smuggling only after a lawful seizure made in reasonable belief that the gold is smuggled. A general panchnama recital, foreign markings, high purity, or an uncorroborated retracted statement cannot alone establish that foundation. Reasons must exist contemporaneously and cannot be supplied retrospectively through later investigation.
Case Laws Income Tax
Show AI Summary
Political contribution deductions require proof that payments are genuine, not merely bank transfers, receipts, and recipient registration.
Registration of the recipient political party, non-cash remittance, banking records and donation receipts are necessary evidentiary facts for a political-contribution deduction, but do not conclusively prove a genuine contribution. Where credible material indicates an accommodation-entry arrangement involving return of funds through intermediaries, the claimant must substantiate the transaction and address taxpayer-specific circumstances. General allegations about a recipient cannot alone displace a claim without a sufficient nexus to the taxpayer's own payment. Penalty initiation requires separate determination of under-reporting or misreporting and a reasonable opportunity of hearing.
Case Laws GST
Show AI Summary
Estate-limited GST recovery permits post-death assessment of legal representatives while protecting heirs' independent assets after business discontinuance.
Section 93 permits post-death GST determination against a legal representative where a liable person dies. If the business is discontinued, tax, interest and penalty may be recovered only from the deceased's inherited estate and only within its capacity; the heir's independent assets remain outside that limit. Proceedings may be initiated without a pre-death notice, but must be addressed to the legal representative in that capacity, follow the applicable adjudication process, and provide hearing and a reasoned order.
Case Laws FEMA
Show AI Summary
Recorded reasons to believe govern foreign-asset seizure; non-confirmation requires appellate resolution before contradictory adjudication proceeds.
Section 37A permits seizure of equivalent domestic assets only where the authorised officer records written reasons to believe that foreign assets are held in contravention of FEMA. The competent authority must examine the material after hearing both sides and either confirm or set aside seizure. A reasoned non-confirmation based on an absent statutory threshold is substantive on seizure, though it does not finally decide the underlying contravention. Pending appeal, the adjudicating authority cannot displace that finding or adopt a contrary premise; Section 37A(4) applies only to confirmed seizure.
Case Laws Companies Law
Show AI Summary
Unstayed tribunal dismissal leaves former directors without corporate authority while banks follow valid company instructions amid management disputes.
Where an oppression and mismanagement petition has been dismissed, a pending appeal without an appellate stay does not itself restore a former director's authority or suspend the dismissal's operative effect. Sections 241 and 242 require statutory prejudice and prescribed Tribunal findings; procedural irregularities in director removal may be relevant but do not alone establish oppression. Banks should ordinarily follow formally authorised company instructions rather than decide unresolved management disputes, unless a binding judicial or statutory restraint applies.
Case Laws Benami Property
Show AI Summary
Benami property claims cannot be recast through wills or employment-based trust when pleadings assert beneficial ownership.
Benami-property claims based on a claimant's payment for property titled in another person's name may fall within the statutory definition when the property is alleged to be held for that claimant's benefit. A Will, succession claim, or other later instrument does not provide an independent basis of title where the pleaded foundation is restoration of beneficial ownership. The statutory scheme prohibits benami arrangements, bars enforcement of claimed beneficial ownership, and treats prohibited re-transfers as invalid; self-acquired title in the named holder's name does not displace the pleaded funding arrangement.
Case Laws Income Tax
Show AI Summary
Reason to believe in reassessment requires tangible material, a live nexus, and recorded reasons; review of examined issues is barred.
Income-tax reassessment under Sections 147 and 148 is permissible only where recorded reasons, assessed at the time of notice, disclose a bona fide reason to believe that chargeable income escaped assessment. Final proof is unnecessary at that stage, but relevant tangible material must have a rational, live link to escapement. Reopening cannot be used to review an issue consciously examined and decided in the original scrutiny; nor can later or extraneous material supplement the recorded reasons. The taxpayer may seek the reasons, file focused objections, and receive a speaking order before reassessment continues.
Case Laws Income Tax
Show AI Summary
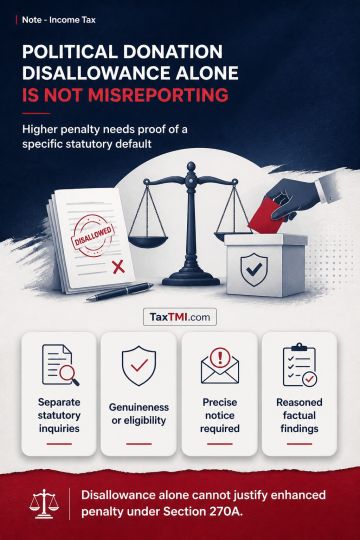
Political-donation deduction disallowance does not itself establish misreporting; enhanced penalty requires proof of a specific statutory default.
Disallowance of a political-contribution deduction under Section 80GGC and imposition of penalty under Section 270A are separate statutory inquiries. An adverse finding on genuineness or eligibility may raise assessed or reassessed income, but cannot alone establish misreporting. Enhanced penalty requires proof that the taxpayer's conduct falls within a specific Section 270A(9) category, supported by a precise notice and reasoned factual findings.
Case Laws Income Tax
Show AI Summary
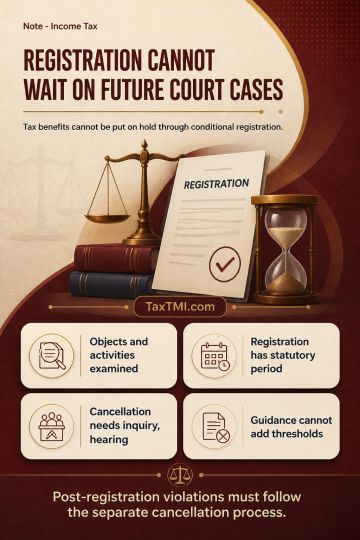
Conditional charitable registration cannot suspend tax benefits pending litigation outside the statutory grant and cancellation framework.
Section 12AB permits the authority, after inquiry into objects, genuine activities and material legal compliance, to grant registration for the statutory period or reject the application. It does not create a contingent form of registration whose tax consequences await future litigation. Post-registration violations must be addressed through the separate cancellation process, requiring inquiry and hearing. Conditions in prescribed forms or administrative guidance may operationalise statutory duties but cannot create extra-statutory eligibility thresholds, future-conduct obligations or anticipatory cancellation consequences. Binding jurisdictional rulings remain applicable unless stayed, modified or reversed.
Case Laws Customs
Show AI Summary
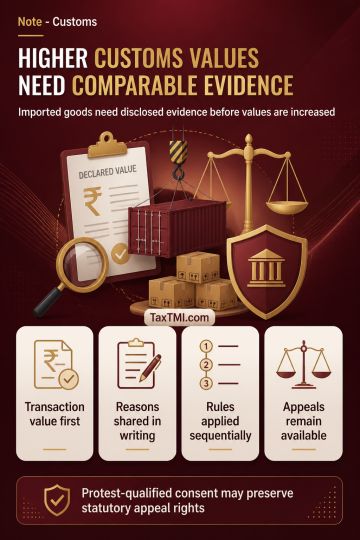
Transaction value reassessment requires disclosed comparable evidence, while protest-qualified consent preserves appellate rights against enhanced customs valuation.
Transaction value under Section 14 and Rule 3 is the primary basis for valuing imported goods. Rule 12 permits rejection only where an objectively sustainable reasonable doubt persists after considering further information; on request, the grounds must be disclosed in writing and a hearing afforded. Redetermination must follow Rules 4 to 9 sequentially and rely on demonstrably comparable import data. Written acceptance of reassessment may dispense with a speaking order under Section 17(5), but protest-qualified or provisional-clearance correspondence may preserve the statutory right to appeal.
Case Laws GST
Show AI Summary
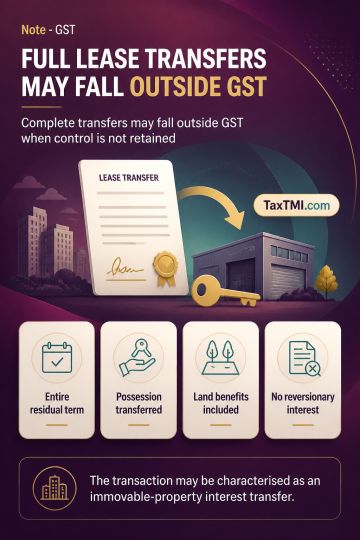
Leasehold rights assignment may fall outside GST when the lessee permanently transfers the entire proprietary estate.
GST treatment of assignment of leasehold rights turns on whether the lessee has made a complete transfer of its existing estate or continues to provide occupation or enjoyment. Where the assignor transfers the whole residual term, possession, building and associated rights, retains no reversionary or controlling interest, and the assignee succeeds directly to obligations towards the original lessor, the transaction may be characterised as transfer of benefits arising out of land rather than a supply of services. Labels such as premium, salami or transfer fee are not conclusive.
Case Laws Income Tax
Show AI Summary
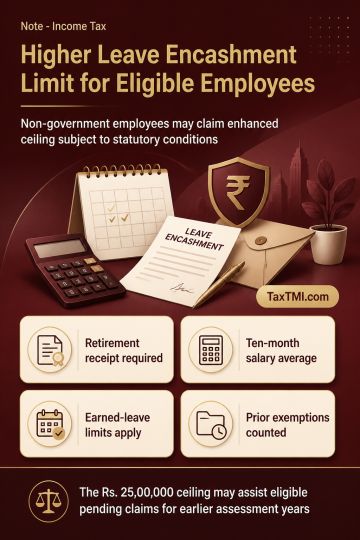
Leave encashment exemption: Non-government employees may claim the enhanced notified ceiling subject to statutory computation conditions.
Retirement leave encashment received by employees other than Central or State Government employees falls under Section 10(10AA)(ii). Exemption depends on retirement, the ten-month earned-leave limit, average salary for the preceding ten months, earned-leave entitlement restrictions, aggregate limits, and prior exempt receipts. The enhanced notified ceiling of Rs. 25,00,000, deemed to operate from 1 April 2023, is treated in the Tribunal approach discussed as a beneficial rationalisation available to eligible pending claims for earlier assessment years, without displacing the statutory computation conditions.
Case Laws Income Tax
Show AI Summary
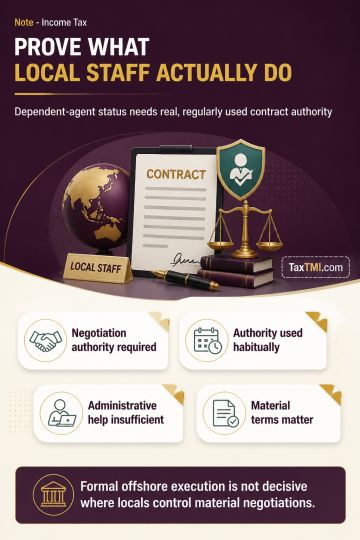
Dependent agent permanent establishment requires proven habitual contractual authority; liaison, administrative support, and customer contact alone remain insufficient.
Dependent agent permanent establishment under Article 5(5) requires proof that an Indian person has authority to negotiate and enter contracts for the foreign enterprise and habitually exercises that authority. Customer liaison, account management, administrative support, communication of pre-approved terms, document routing, and assistance with online standard-form contracting fall short unless Indian personnel substantively determine essential terms or routinely bring negotiations to a binding commercial conclusion. Formal offshore execution is not decisive where local personnel effectively control material negotiations. Corporate association, economic dependence, and independent-agent considerations cannot replace proof of the positive authority and habitual-exercise requirements.
Case Laws Customs
Show AI Summary
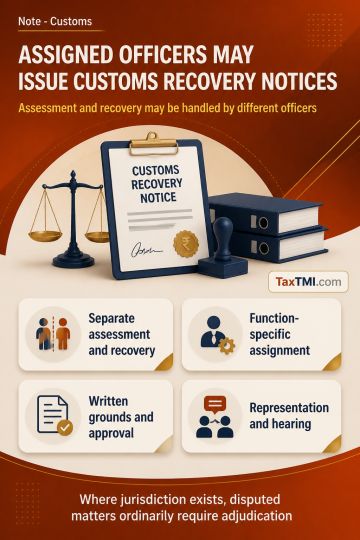
Proper-officer jurisdiction permits assigned customs officers to issue recovery notices without having performed the original assessment.
Customs show-cause jurisdiction requires both appointment as an officer of customs and function-specific assignment as the proper officer. Assessment under Section 17 and recovery under Section 28 are distinct functions; the original assessing officer need not alone issue a recovery notice. Retrospective validation of qualifying officers' proper-officer status applies independently of the preserved historical recovery regime. Confiscation and penalty proceedings require written grounds, prescribed prior approval, representation, and hearing. Where jurisdiction exists, disputed facts, evidence, limitation, and procedural compliance ordinarily require determination through adjudication.
Case Laws Money Laundering
Show AI Summary
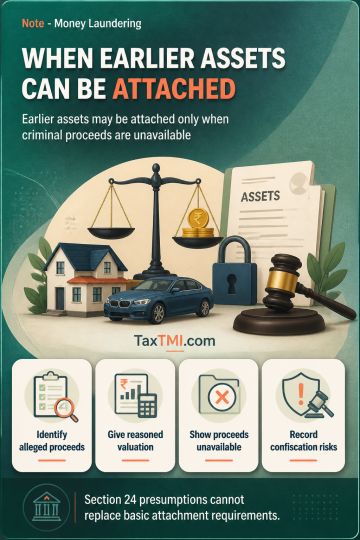
Equivalent-value attachment permits securing untainted pre-offence assets only when unavailable criminal proceeds, valuation, and statutory risk are established.
Pre-offence property is ordinarily not directly derived from later scheduled-offence activity, but may be provisionally attached as equivalent value where actual proceeds are unavailable. Such attachment requires identification and reasoned valuation of the alleged proceeds, material showing their unavailability, and recorded reasons to believe that non-attachment risks concealment, transfer, or other frustration of confiscation. A later use of illicit funds to repay loans, construction borrowing, or secured obligations may separately establish a direct or indirect nexus. Section 24 presumptions do not replace the foundational requirements for attachment.
Case Laws IBC
Show AI Summary
Cross-assignment disciplinary suspension requires proportionate, assignment-specific hearing while creditor committees retain statutory control over replacement decisions.
Where disciplinary misconduct concerns one CIRP, cross-assignment suspension requires a proportionate link to the pleaded charge, supporting material and hearing afforded. Section 220(2) permits disciplinary sanctions after hearing, while Regulation 13(7) requires intimation to Committees of Creditors and the Adjudicating Authority. On the prima facie construction applied, intimation informs each Committee's decision on continuation or replacement rather than automatically removing the professional from unrelated ongoing assignments. The Board's regulatory role and the Committee's replacement power remain distinct but connected.
Case Laws GST
Show AI Summary
Electronic authentication of GST notices requires prescribed signatures; portal uploads, reference numbers, and DRC summaries cannot independently validate proceedings.
Rule 26(3) makes electronic issuance and authentication by digital signature, e-signature, or a notified verification mode cumulative conditions for GST notices and orders. A portal upload concerns service, while a system-generated reference number, DRC summary, or DIN performs tracking or procedural functions; none independently establishes the authorised officer's authentication. Section 169 governs service rather than validity, and Section 160 does not ordinarily cure a defect preventing attribution of the instrument to the competent officer. DRC-01 cannot replace the statutory notice, and DRC-07 supports recovery only upon a valid order.
Case Laws GST
Show AI Summary
GST bail classification requires precise Section 132 charging clauses, with investigation status, cooperation and proportionality governing custodial necessity.
GST-evasion bail adjudication requires a case-specific assessment of custodial necessity rather than an automatic consequence of the alleged tax magnitude, Magistrate-triability, or a maximum five-year sentence. Section 132 classification depends on the precise offence clause and punishment bracket, not merely on the alleged quantum of evasion. Relevant considerations include the stage of investigation, cooperation with summons, security of evidence, individual role, risks of absconding or interference, proportionality, and personal liberty under Article 21.
Case Laws Customs
Show AI Summary
Certificate-specific origin verification prevents preferential-duty denial based solely on unrelated suspect certificates or supplier doubts.
Preferential customs-duty treatment requires compliance with applicable rules of origin and reliable proof that imported goods qualify as originating. A country-of-origin certificate is important evidence but does not remove the importer's duty to possess supporting origin information and exercise reasonable care. Challenges to preferential treatment must be certificate-specific and consignment-specific: an adverse finding concerning identified certificates cannot, without direct evidence, invalidate separate certificates. Customs verification should identify the particular proof of origin, alleged defect and material linking it to the import, while fraud, suppression or misrepresentation independently established may support substantive action.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Comparison of section 341 "Application of income." between the Income-Tax Act, 2025 (as passed) and the Income-Tax Bill, 2025 (as originally introduced)

11 September, 2025

Contents
Acts
Rules & Regulations
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Section 341 Application of income

Income-tax Act, 2025

At a Glance

Clause 341 of the Income Tax Bill, 2025 (Old Version) sets out what constitutes permissible application of income by registered non-profit organisations. It matters to charitable/religious trusts and registered non-profit organisations, and to tax authorities monitoring compliance with application-of-income conditions. Effective date/decision date: Not stated in the document.

Background & Scope

Statutory hook: Clause 341 of the Income Tax Bill, 2025 (Old Version) addressing "Application of income" of a registered non-profit organisation. Context: governs what sums may be treated as application of income for non-profit organisations to ascertain compliance with conditions for tax treatment. Coverage: sums applied for charitable/religious purposes in India, donations to other registered non-profits, corpus donations, reinvestment of corpus in permitted modes u/s 350, repayment of loans/borrowings, and exclusions. Definitions or further explanations: Not stated in the document beyond references to sections 35(b)(i), 36(4)-(7), and section 350.

Statutory Provision Mode

Text & Scope

Clause 341, Income Tax Bill, 2025 (Old Version) sets out what sums are to be allowed as "application of income" to a registered non-profit organisation. The provision identifies three categories in sub-section (1): (a) sums applied for charitable or religious purposes in India for which the organisation is registered (subject to payment during the tax year and allowability under specified sections), (b) 85% of donations made to other registered non-profit organisations, and (c) nil with respect to corpus donations to other registered non-profit organisations. Sub-section (2) includes reinvestments into permitted corpus modes and repayments of loans/borrowings within five years (subject to conditions including no prior violation and application post 31 March 2021) as application of income. Sub-section (3) excludes from application: depreciation/allowances claimed in respect of an asset acquisition already treated as application of income and set off/allowance of excess application from prior years. Sub-section (4) states that application from corpus, loan/borrowing, accumulated income, specified income or deemed accumulated income shall not be considered as application for the purpose of sub-sections (1) and (2).

Interpretation

The text links the concept of "application of income" to both timing (payment during the tax year) and substantive allowability u/ss 36(4)-(7) and 35(b)(i). Legislative intent apparent from the text is to restrict qualifying applications to sums that are both paid and allowable under income tax rules, and to avoid treating corpus transfers as qualifying applications. The Bill articulates a cross-reference approach whereby existing tax-law tests (sections 35 and 36 provisions) determine allowability. The inclusion of a prescribed percentage treatment for donations to other registered organisations (85%) indicates a legislative policy to permit a substantial portion of inter-charity donations to count as application while retaining a residual disallowance (15%).

Exceptions/Provisos

Explicit exceptions in the Bill text: corpus donations to other registered non-profit organisations are treated as nil for application purposes. Sub-section (3) excludes depreciation/allowances already claimed and set off of earlier excess applications. Sub-section (4) excludes application from corpus, loan/borrowing, accumulated income, specified income or deemed accumulated income for the purposes of sub-sections (1) and (2). There are conditional provisos in sub-section (2) requiring reinvestment or repayment within five years and that the original application from corpus or loan/borrowing be post-31 March 2021 and compliant with the Part.

Illustrations

  • Example 1 - Direct application: A registered trust pays Rs. 1,000,000 during the tax year for a charitable program for which it is registered, and the payment is allowable u/ss 36(4)-(7) and 35(b)(i). That sum would qualify as application of income under sub-section (1)(a).
  • Example 2 - Donation to another registered organisation: A registered society donates Rs. 100,000 to another registered society. Under sub-section (1)(b), 85% (i.e. Rs. 85,000) would count as application of income; under sub-section (1)(c) corpus components would count as nil if the payment is a corpus donation.
  • Example 3 - Reinvestment from corpus: Not stated in the document whether a trust that re-invests corpus within five years will satisfy other procedural prerequisites beyond those listed; the Bill requires reinvestment within five years and that the original corpus application be after 31-03-2021 with no violations. Specific permitted modes are referred to section 350 (modes) but details of those modes are Not stated in the document.

Interplay

The clause expressly refers to and depends upon sections 35(b)(i), 36(4)-(7) and section 350 for determining allowable payments and permitted modes of investment. It also cross-refers to "this Part" and corresponding provisions of the Income-tax Act, 1961 for compliance history. Specific rules, notifications or circulars beyond these textual cross-references are Not stated in the document.

Differences between the two provisions and practical impact

  • Explicit treatment of corpus donations paid to other organisations:

    • Bill (Clause 341, Document 2): sub-clause (1)(c) expressly states "nil, with respect to any sum paid as a corpus donation to any other registered non-profit organisation."
    • Act (Section 341, Document 1): sub-section (3)(c) provides that "any sum paid as a corpus donation to any other registered non-profit organisation" shall not be allowed as application of income (i.e., it is listed among claims not allowed).
    Practical impact: Both texts in effect disallow treating corpus donations to other registered entities as application of income, but the Bill states the position as a component of what is allowed (explicitly allowing "nil"), while the Act lists it among exclusions. Substance is similar; the Bill's expression is potentially clearer as a standalone rule, whereas the Act's placement in exclusions may be read as reinforcing general illegibility for application treatment.
  • Order and wording of paid sums qualifying as application:

    • Bill (Document 2): sub-section (1)(a) requires the sum be "paid during such tax year" and "such payment is allowable u/ss 36(4), (5), (6) and (7) and 35(b)(i)."
    • Act (Document 1): sub-section (1)(a) provides similar requirements but phrases them as "where such sum is paid during the tax year provided that the provisions of section 35(b)(i) and section 36(4), (5), (6), and (7) shall apply in respect of such sum."
    Practical impact: No substantive difference in the qualifying conditions; the Act's language places emphasis on the applicability of the identified sections, while the Bill is more prescriptive that payment during the year and allowability under those sections are required. Both link allowability u/ss 35/36 to qualification as application.
  • Deemed application (85% rule and deemed application mechanics):

    • Bill (Document 2): does not contain provisions comparable to Section 341(5)-(8) of the Act concerning the 85% of regular income requirement, shortfall treatment as deemed application, timing for application of deemed application, and exercise of option.
    • Act (Document 1): contains sub-sections (5)-(8) establishing an 85% regular income normative target, permitting registered organisations to elect to treat shortfall as deemed application, specifying timing rules for application, and prescribing exercise of option on or before the due date u/s 263(1) for furnishing return of income.
    Practical impact: The Act introduces a compliance mechanism (85% of regular income) and a deemed application regime with procedural timings. The Bill version lacks this constructive mechanism; therefore, under the Bill an organisation's failure to apply regular income to the extent of 85% would not be remedied by deeming (unless other provisions exist elsewhere). The Act increases formal compliance burdens and provides a remedy (option) to treat shortfall as application within specific timelines; omission from the Bill means those procedural obligations/benefits are not present in the Bill text as reproduced.
  • Capital gains treated as application:

    • Bill (Document 2): contains no counterpart to the Act's sub-sections (9) and (10) dealing with capital gains from transfer of capital assets held for charitable or religious purposes and definitions such as "appropriate fraction," "cost of transferred asset," and "net consideration."
    • Act (Document 1): specifies when capital gains on transfers of trust property are deemed application (full or fractional amounts) and provides definitions for key terms used in that analysis.
    Practical impact: The Act creates a clear statutory rule treating certain capital gains as application of income when proceeds are reinvested in qualifying capital assets; the Bill lacks such rules, leaving potential ambiguity regarding tax treatment of capital gains arising to trusts. The Act's rules may aid in tax neutrality for reinvestment of trust assets; absent that, the Bill would leave organisations reliant on other provisions or administrative guidance.
  • Express exclusions and structuring differences:

    • Bill (Document 2): The exclusions list in sub-section (3) comprises clauses (a) and (b) (depreciation/allowance previously claimed as application; set off of excess application), but does not include clause (c) of the Act (which there is included in Act sub-section (3)(c)).
    • Act (Document 1): explicitly includes three exclusions (a), (b), (c) in sub-section (3), making the treatment of corpus donations as excluded clearer within the exclusions list.
    Practical impact: The Act's exclusions list is more exhaustive. The Bill's omission (as presented) could cause interpretive uncertainty until clarified by other provisions or parliamentary amendments.

Practical Implications

  • Compliance and risk areas: The requirement that payments be "paid during such tax year" and be allowable under the cross-referenced sections imposes evidentiary and timing burdens on registered non-profit organisations to substantiate payments and their tax allowability. The 85% rule for donations to other registered entities creates a mathematical step for accounting and tax reporting; organisations must track whether payments are corpus or non-corpus to determine whether 85% or nil applies.
  • Record-keeping/evidence: Organisations will need contemporaneous payment evidence (ledgers, bank payment instruments), documentation demonstrating allowability u/ss 35/36, clear characterisation of donations as corpus or revenue, and records of repayments or reinvestments into permitted modes (section 350) within five-year periods where applicable. The Bill's five-year windows and post-31-03-2021 condition require maintenance of historical compliance records showing no violations.

Key Takeaways

  • Clause 341 defines what counts as application of income for registered non-profit organisations, linking allowability to sections 35 and 36 and to timing of payment.
  • Donations to other registered organisations are partly recognised (85%) except corpus donations which are expressly treated as nil.
  • Reinvestment into permitted corpus modes and repayment of loans may be treated as application if made within five years and subject to compliance conditions and post-31-03-2021 applicability.
  • Certain claims (depreciation/allowances already claimed as application; set off of earlier excess application) are excluded from being treated as application.
  • The clause depends on other provisions (sections 35, 36 and 350) for definitions and modalities; practical compliance requires careful recordkeeping.
  • Compared with the enacted Section 341, the Bill (old version) omits the deemed-application (85% regular income) mechanism and capital-gains-deemed-application rules present in the Act.

Full Text:

Section 341 Application of income

Topics

Acts Income Tax