Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Concessional GST on Works Contracts for Co-operative Spinning Mills: Government Entity Status and Pr...
    Case Laws Customs
    Abetment and Knowing Use of False Import Documents under Sections 112(a) and 114AA
    Subcontracted Services on Own Account and the Intermediary Exclusion under Section 2(13)
    Case Laws Customs
    Classification of Two-Ton Ductless Split Air Conditioners under Tariff Item 8415 82 10
    Case Laws Income Tax
    Transfer Pricing of Pre-Conversion Interest on Compulsorily Convertible Debentures
    Case Laws Customs
    Clubbing of Contrived Split Consignments under Rule 2(a) and Valuation of a Dismantled Motorcycle
    GST on Corporate Guarantees: Substantive Liability, Deemed Valuation and Judicial Relief
    Case Laws Income Tax
    Employee Secondment under the India-USA DTAA: Employment Rights, Reimbursements and Included Service...
    Pre-deposit Under Section 112 and Independent Compliance with Tribunal Filing Fees
    Case Laws Income Tax
    TDS on Interest Paid by Co-operative Banks to Non-Member Co-operative Societies under Section 194A(3...
    Input Tax Credit and Supplier Non-Payment: Statutory Limits on Mechanical Reversal Under Section 16(...
    Case Laws Customs
    Appellate Jurisdiction over Goods Imported as Baggage under Sections 129A and 129DD of the Customs A...
    Monetary Limits for Departmental GST Appeals under Section 120 and Circular No. 207/1/2024-GST
    Alleged Re-use of E-Way Bills under Section 129: Evidentiary Burden in Detention Proceedings
    Turnover of Zero-Rated Supply Under Rule 89(4): Invoice Period and Subsequent Physical Export
    Case Laws Income Tax
    Reassessment Proceedings: Speaking Disposal of Objections Before Scrutiny Under Sections 143(2) and ...
    Suppression of Facts under Explanation 2 to Section 74 of the CGST Act in Cases of Ineligible Input ...
    Case Laws Customs
    Classification of Low-Ethoxylated Non-Ionic Fatty Alcohol Ethoxylates under Headings 3402 and 3824
    Case Laws Customs
    Seizure and Detention of Imported Cars under Sections 110, 110A and 124 of the Customs Act, 1962
    Case Laws Companies Law
    Lifting the Corporate Veil Where Promoter Shareholding Is Allegedly Dissipated Despite Judicial Assu...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
Non-business construction concessions for spinning mills require eligible recipient status and predominantly non-industrial use of the constructed buildings.
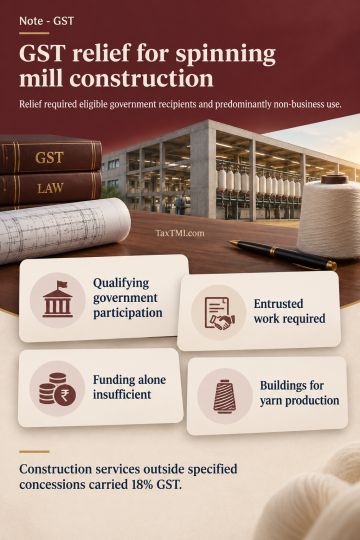
For the disputed period, the works-contract concession required both an eligible governmental recipient and structures predominantly meant for use other than commerce, industry, business or profession. Government Entity status required evidence of the recipient's constitution and qualifying governmental participation, while procurement had to relate to entrusted work. Project funding, tender approval and supervision did not by themselves establish governmental constitution or control. The spinning-mill factory buildings and allied works were intended for yarn production and related commercial activities. The residual construction-services entry carried aggregate GST of 18% for services outside the specified concessional entries.
Case Laws Customs
Show AI Summary
Import document handling alone does not establish customs abetment or knowing use of materially false declarations.
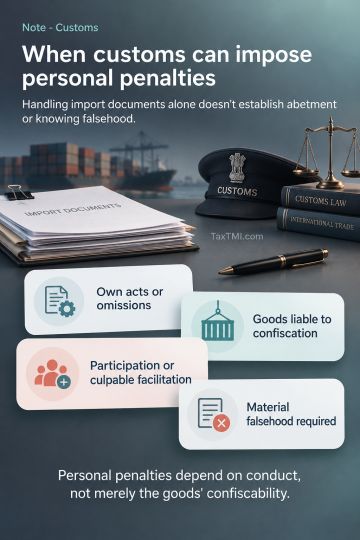
Personal customs penalties depend on the person's own conduct, not merely on the confiscability of imported goods. Under Section 112(a) of the Customs Act, 1962, liability may arise from a person's own act or omission rendering goods liable to confiscation or from abetment of such conduct. The direct limb can operate on a strict-liability basis where a person's own act or omission renders goods confiscable; an allegation of abetment instead requires evidence of participation or culpable facilitation. Section 114AA requires knowing or intentional making, signing or use, or causing the making, signing or use, of a declaration, statement or document that is materially false or incorrect in customs business.
Case Laws GST
Show AI Summary
Subcontracted services performed on own account are not intermediary services merely because they support overseas recruitment and customer-facing activities.
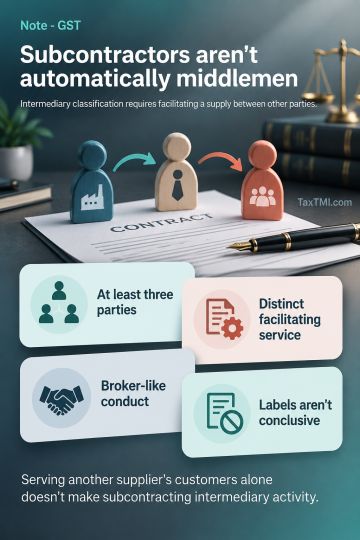
Intermediary classification under Section 2(13) of the IGST Act distinguishes arranging or facilitating supplies between other persons from supplying services on one's own account. The intermediary framework requires at least three parties, a main supply and a distinct ancillary facilitating supply, with conduct resembling that of a broker or agent. Subcontracting the whole or part of a service is not intermediary activity merely because performance supports another supplier's business or involves its customers. Neither a bilateral agreement, contractual label nor remuneration method is conclusive.
Case Laws Customs
Show AI Summary
Split air conditioner classification requires capacity and refrigeration features to be assessed against the applicable tariff hierarchy.
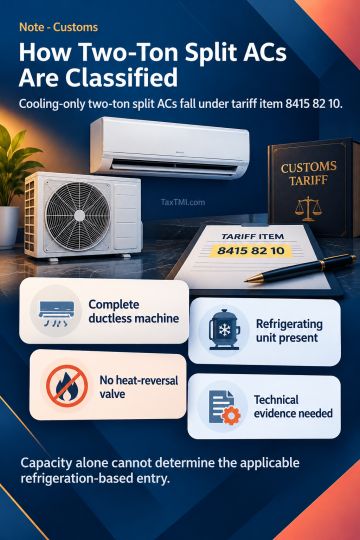
Classification of ductless split air conditioners depends on the complete tariff description and the machine's technical characteristics. A complete, cooling-only, two-ton split air conditioner incorporating a refrigerating unit and lacking a heat-reversal valve falls within tariff item 8415 82 10 rather than the general split-system item 8415 10 10. Item 8415 82 10 inherits its parent subheading's refrigerating-unit requirement, while item 8415 83 10 requires the absence of such a unit. Capacity alone does not establish the applicable refrigeration-based entry. Technical evidence should establish whether the goods are a complete machine and identify their capacity and operating features.
Case Laws Income Tax
Show AI Summary
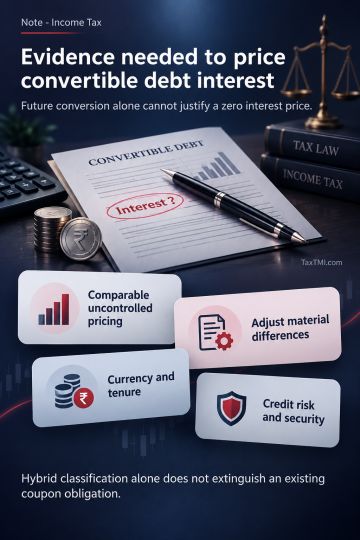
Convertible debenture interest requires evidence-based pricing before conversion; future equity conversion alone cannot establish a nil arm's length price.
Pre-conversion interest on compulsorily convertible debentures (CCDs) issued to a non-resident associated enterprise requires arm's length pricing. Compulsory future conversion and hybrid classification do not, by themselves, establish a nil price or extinguish an existing coupon obligation. Rule 10AB's Other Method requires a price charged, paid or expected in comparable uncontrolled circumstances, with reasonably accurate adjustments for material differences under Rule 10B. Currency, benchmark date, tenure, credit risk, security, non-redemption and conversion benefits affect comparability; a conventional bank lending rate is not automatically comparable to a long-tenor CCD.
Case Laws Customs
Show AI Summary
Split motorcycle consignments require evidence of deliberate fragmentation for composite classification, with valuation assessed independently of classification.
Clubbing of split consignments for customs classification depends on proof that apparently separate imports form one deliberately fragmented transaction, not merely on the possibility of assembly. Rule 2(a) extends a tariff heading to an incomplete article possessing the essential character of the complete article and also covers a complete article presented disassembled. A change of tariff heading alone does not establish that the transaction value is inaccurate; substantive misdescription of the goods requires separate evidentiary consideration. Replacement value must follow the prescribed sequence of methods.
Case Laws GST
Show AI Summary
Corporate guarantee taxation depends on distinguishing taxable supply from valuation, particularly for unpaid support between related businesses.
GST on corporate guarantees requires separate consideration of whether a taxable supply exists and how that supply is valued. Section 7(1)(c) and Schedule I encompass qualifying supplies between related or distinct persons without consideration when made in the course or furtherance of business. Rule 28(2) deems the value of a guarantee furnished to a banking company or financial institution for a related recipient in India to be one per cent of the guaranteed amount per annum or actual consideration, whichever is higher. Where the recipient is eligible for full input tax credit, the proviso treats the value declared in the invoice as the value of the supply.
Case Laws Income Tax
Show AI Summary
Employee secondment taxation depends on employment rights, service consideration and demonstrable transfer of technical capability to host entities.
Local operational control and a stated suspension of foreign employment do not, by themselves, resolve whether underlying foreign employment rights survive. Under Article 12(4)(b) of the India-USA DTAA, technical or consultancy services must make technical knowledge, experience, skill, know-how or processes available, or involve development and transfer of a technical plan or design. Under the knowledge-transfer limb, the recipient must acquire a capability it can use independently; the mere application of expertise or presence of qualified personnel is insufficient. Recovery at actual cost and absence of markup do not, by themselves, establish that a foreign enterprise's receipt is non-taxable.
Case Laws GST
Show AI Summary
GST appellate pre-deposits may be satisfied by verified earlier payments after demand reduction, but filing fees remain independently payable.
When the first appellate authority substantially reduces the disputed tax demand, an earlier deposit may be sufficient to satisfy the Tribunal-stage requirement, subject to verification. Sufficiency depends on the reduced liability, the applicable appellate requirements and the amount actually deposited; a first appellate payment does not automatically eliminate the additional obligation. Tribunal filing fees under Section 112(7) operate independently of pre-deposit. Where a fee shortfall and earlier deposit require verification, proof of fee payment and verification of the deposit precede consideration of admission.
Case Laws Income Tax
Show AI Summary
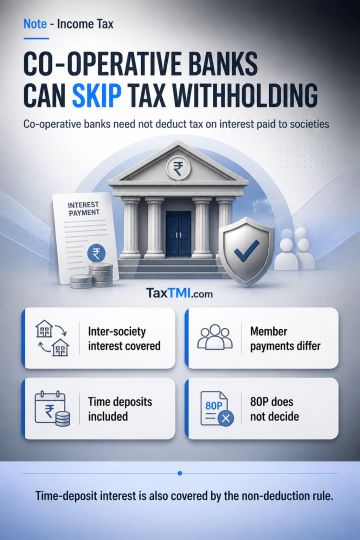
Inter-co-operative society interest exemption preserves non-deduction by co-operative banks when depositors are co-operative societies under the statutory withholding framework.
Section 194A(3)(v) separately addresses interest paid by a co-operative bank to a member and interest paid by a co-operative society to another co-operative society. The exclusion of co-operative banks is confined to the member-payment limb; a co-operative bank remains a co-operative society for the inter-co-operative society limb. Paragraph 42.7 of Circular No. 19/2015 preserves non-deduction, including time-deposit interest, where the depositor is a co-operative society. Section 80P does not determine this withholding obligation.
Case Laws GST
Show AI Summary
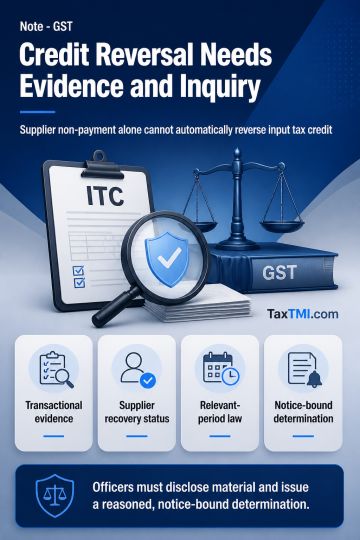
Input tax credit reversal requires evidence linking supplier non-payment to recipient ineligibility and a reasoned statutory inquiry.
Input tax credit under Section 16(2)(c) remains conditional on actual payment of tax to Government, but supplier non-payment or retrospective cancellation cannot by itself justify reversal. The recipient must establish eligibility through transactional evidence, while the proper officer must investigate the particular supply, disclose supplier-default and recovery material, apply the law applicable to the relevant period, and issue a reasoned, notice-bound determination. Supplier recovery status and protection against duplicate collection are material considerations.
Case Laws Customs
Show AI Summary
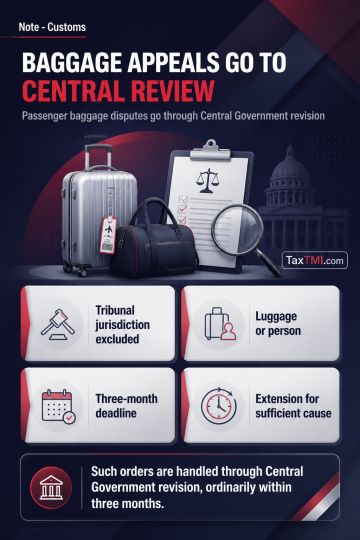
Baggage-related customs appeals proceed through statutory revision when the jurisdictional exclusion applies to passenger imports.
The first proviso to section 129A(1) excludes Appellate Tribunal jurisdiction over an order under section 128A relating to goods imported or exported as baggage. The decisive issue is the order's connection with baggage, not disputes concerning confiscation, declaration, duty, personal effects, concealment, concession, or penalty. Articles carried by an international passenger in luggage or on the person may constitute baggage. Section 129DD provides revision before the Central Government, ordinarily within three months, subject to a further period on sufficient cause.
Case Laws GST
Show AI Summary
Departmental GST appeal monetary limits regulate officers, while composite orders and proven recurring issues may permit appeals.
Sections 120 and 168 of the Central Goods and Services Tax Act, 2017 make monetary-limit directions binding within the Central tax hierarchy, while they regulate the executive decision to file rather than create an inflexible jurisdictional bar before the Tribunal. In a composite order disposing of multiple appeals or demand notices, the relevant amount is the total disputed tax, interest, penalty or late fee, as applicable. The recurring or interpretative-issue exclusion requires a reasoned, case-specific basis, and Commissioner authorisation does not itself establish compliance with the litigation policy.
Case Laws GST
Show AI Summary
E-way bill re-use allegations require corroborated proof identifying the same goods; vehicle movement alone cannot establish contravention.
Alleged re-use of invoices and e-way bills requires the seizing authority to establish through positive, corroborated evidence that the intercepted goods are the same consignment previously transported under those documents. Toll data, vehicle movements and photographs may justify inquiry but do not alone prove prior delivery, identity of goods or re-use. Where invoices and e-way bills accompany the goods and physical verification shows no discrepancy, the authority must investigate and address any explanation of a different earlier consignment. Cases involving absent or expired transport documents remain factually distinct.
Case Laws GST
Show AI Summary
Zero-rated supply turnover includes export invoices from the refund period when actual export is subsequently established under bond or LUT.
Under Rule 89(4), invoice values for goods invoiced before or at removal for export under bond or Letter of Undertaking may be included in zero-rated turnover for the relevant refund period, although physical export occurs later. The invoice and removal determine period-wise attribution for the refund formula, while actual export remains essential to sustain the claim. Shipping bills, bills of export and related export records must correlate with the export invoices to establish that the goods were ultimately exported. Compliance with valuation, input tax credit eligibility and bond or Letter of Undertaking conditions remains necessary.
Case Laws Income Tax
Show AI Summary
Reassessment objections require speaking disposal and a four-week pause before scrutiny or information requests can begin.
Under the pre-amendment Section 148 framework, reassessment jurisdiction must be resolved before merits-stage scrutiny begins. The Assessing Officer must furnish recorded reasons when requested, permit objections, and decide them through a separate speaking order. A Section 143(2) notice commences scrutiny, while a Section 142(1) notice is a substantive inquiry step; neither may issue before objections are decided. Following rejection, a four-week period from service of the speaking order must be allowed before further reassessment action, preserving an effective opportunity to challenge reopening.
Case Laws GST
Show AI Summary
Suppression of facts requires proof of deliberate tax evasion; ineligible input tax credit alone cannot support enhanced proceedings.
Section 74 permits enhanced tax determination for wrongly availed or utilised input tax credit only where fraud, wilful misstatement, or suppression of facts to evade tax is established. Wrong or ineligible credit is distinct from substantive credit eligibility and cannot, without evidence of deliberate conduct and intent, amount to suppression. Under historical Explanation 2, suppression required either omitted information legally required in prescribed filings or failure to provide information sought in writing; both operate subject to the statutory evasion requirement. Disclosed reconciliations and portal records materially weaken a bare allegation of non-declaration.
Case Laws Customs
Show AI Summary
Organic surface-active agent classification requires water solubility and stability; phase-separating low-ethoxylated products fall outside Heading 3402.
Classification of low-ethoxylated non-ionic fatty alcohol ethoxylates under Heading 3402 requires satisfaction of the cumulative water test in Chapter Note 3. At the prescribed concentration, temperature, and standing period, the product must both remain a transparent or translucent liquid, or stable emulsion, without phase separation and reduce water surface tension to the stated threshold. Non-ionic character or surface activity alone is insufficient. Where a low-ethoxylated product separates into layers and fails the solubility and stability requirement, Heading 3824 may be considered after exclusion from Heading 3402.
Case Laws Customs
Show AI Summary
Lawful customs seizure requires recorded confiscation grounds, formal restraint where needed, and timely notice; detention cannot bypass safeguards.
Customs seizure of an imported car requires recorded reason to believe that it is liable to confiscation. A panchnama restraint cannot replace a lawful seizure order, an undertaking where seized goods remain in custody, or a served non-dealing order where seizure is impracticable. Section 110(2) requires prompt notice under Section 124, subject only to the prescribed extension mechanism. Prolonged effective detention cannot postpone those safeguards. Provisional release under Section 110A applies only to goods lawfully seized and cannot validate an earlier detention without statutory authority.
Case Laws Companies Law
Show AI Summary
Corporate veil-piercing permits forensic scrutiny in execution where promoter-controlled entities may dissipate shareholding despite judicial assurances.
Corporate veil-piercing in execution is an exceptional response where promoters allegedly use layered entities and securities transactions to deplete shareholding represented as security through judicial assurances. Separate personality remains the rule, and control or ownership alone does not suffice; there must be a nexus between control, misuse of the corporate form, and frustration of enforcement. A forensic audit reconstructs share movements, pledges, sales, financing, approvals, disclosures, and fund flows, distinguishing legitimate enforcement of pre-existing security from coordinated asset dissipation.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Comparison of section 296 "Time-limit for completion of block assessment." between the Income-Tax Act, 2025 (as passed) and the Income-Tax Bill, 2025 (as originally introduced)

10 September, 2025

Contents
Acts
Rules & Regulations
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Section 296 Time-limit for completion of block assessment

Income-tax Act, 2025

At a Glance

The document under detailed consideration is Clause 296 of the Income Tax Bill, 2025 - (Old Version) which prescribes the time-limits and exclusion rules for completion of block assessments under the special procedure for search cases (section 294). It matters to taxpayers subjected to search and seizure proceedings, their representatives, and the Income-tax Department. The Bill text sets out computation rules, specified exclusions, and minimum remaining-period safeguards. Effective date or enactment status: Not stated in the document.

Background & Scope

Statutory hooks: Clause 296 (Bill) interacts primarily with section 294 (orders following search), section 295 (other persons), section 166(1) (references), section 159 (agreements for exchange of information), sections 244(2), 268(5), 269(1), 270(11)(i), 270(13), 274(1), and chapters dealing with Advance Rulings (sections 381 and 384 cited in the Bill). The Clause sets time-limits for passing assessment orders under the special search/block-assessment procedure and prescribes periods that are to be excluded in computing limitation. Definitions or explanatory notes: Not stated in the document beyond cross-references to the cited sections.

Statutory Provision Mode

Text & Scope

Clause 296 prescribes that an order u/s 294 must be passed within twelve months from the end of the month in which the last of the authorisations for search was executed or requisition was made (sub-s. (1)). It applies "irrespective of the provisions of section 296" (likely an editorial inconsistency in the Bill text: see Interplay). The clause covers both the primary assessee and "other persons" (section 295) with separate computation for the latter (sub-s. (5)). It also provides for a 12-month extension where a reference u/s 166(1) is made during the course of proceedings (sub-ss. (2) and (6)).

Interpretation

The Bill text indicates an intent to fix a relatively short, definite time-frame (12 months) from a clear calendar point (end of the month in which the last search authorisation was executed or requisition made), subject to specified exclusions and extensions. The inclusion of enumerated excluded periods suggests the legislative principle that certain delays (court stays, information exchange, valuation/audit directions, references to authorities) should not count against the statutory limit. The use of calendar-month endpoints and an explicit minimum remaining period mechanism (sub-s. (8)) reflects an aim to provide practical breathing space for completion after exclusion periods. Legislative intent beyond these textual signals: Not stated in the document.

Exceptions/Provisos

Key carve-outs and conditions in the Clause:

  • Exclusion of a period (not exceeding 180 days) from date of search/requisition to date on which seized/requisitioned items are handed over to the Assessing Officer having jurisdiction (sub-s. (3)).
  • Enumerated exclusions in sub-s. (7): court stay periods (until certified copy of vacating order received), exchange-of-information reference periods (up to last receipt or one year, whichever less), time for reopening or re-hearing u/s 244(2), time taken where assessee is directed to get accounts audited/inventory valued u/s 268(5), period for reference to Valuation Officer u/s 269(1), periods linked to contraventions under Schedule III as per section 270(11)(i), references to Principal Commissioner/Commissioner u/s 270(13), periods relating to impermissible avoidance arrangement references u/s 274(1), and periods for Board for Advance Rulings applications and pronouncements u/ss 381/384 (sub-ss. (7)(a) to (j)).
  • Minimum remaining-period protection: where, after exclusion under (3) or (7), the remaining period is less than sixty days, it is extended to sixty days (sub-s. (8)).
  • Month-end extension: if after exclusions or extensions the period would expire before month end, it is extended to end of that month (sub-s. (4) and (9)).

Illustrations

  • Example 1: Search executed on 10 January. Last authorisation executed that month. The normal limitation runs to 31 January of the next year (twelve months from end of the month of execution). If 120 days elapse between search and physical handover and are excluded under sub-s. (3), the remaining period is computed after excluding that 120-day span and then adjusted under sub-s. (4) or (8) as applicable.
  • Example 2: During assessment a reference u/s 166(1) is made. The time available for completion is extended by twelve months under sub-s. (2).
  • Example 3: A court grants a stay on assessment for 90 days; the stay is vacated and the jurisdictional Principal Commissioner receives certified copy 100 days later. The stay period (start to certified copy receipt) is excluded under sub-s. (7)(a) from computation.

Interplay

The Clause expressly interacts with multiple provisions: section 294 (orders after search), section 295 (other persons), section 166 (references), section 159 (exchange of information), section 244(2) (re-hearing/reopening), sections 268-269 (audit/valuation), section 270 (penalty/procedure references), section 274 (avoidance arrangements), and the Advance Rulings provisions (sections 381/384). The Bill text does not refer to any subordinate Rules, notifications or circulars. Potential textual inconsistency: sub-s. (1) refers to "Irrespective of the provisions of section 296", which appears circular or mis-referenced (likely intended to refer to another section-Not stated in the document).

Practical Implications

  • Compliance and risk areas: Tax officers must track multiple exclusion events and maintain documentary proof (dates of handover of seized items, certified copies of court orders, dates of receipt of exchanged information, audit/valuation reports, Valuation Officer reports, advance ruling communications). Failure to accurately compute exclusions could result in time-bar disputes. The Bill requires attention to the precise calendar endpoint ("end of the month") for initial limitation calculation.
  • Record-keeping/evidence points: The text implicitly requires records showing the date of search/requisition, date of handover of seized/requisitioned items, dates of service/receipt of certified copies of court orders and authority communications, dates of references and replies under information-exchange, dates of audit/inventory valuation directions and reports, reports from Valuation Officer, and communications from the Board for Advance Rulings. Specific required forms or formats: Not stated in the document.

Key Takeaways

  • Clause 296 fixes a twelve-month period (from end of the month of last search authorisation/requisition) for completion of block assessment orders u/s 294.
  • Specified exclusions (including up to 180 days for seizure custody and a series of procedural delays) are carved out from limitation computation.
  • A 12-month extension applies where a reference u/s 166(1) is made during proceedings (for primary assessee and separately for "other persons").
  • Where exclusions leave less than sixty days to proceed, the remaining period is extended to sixty days, creating a minimum workable timeframe post-exclusions.
  • Month-end rounding rules extend expiry to the end of the month if the period would otherwise expire mid-month.
  • The Clause requires careful tracking of multiple external events and receipt dates; however, procedural forms, judicial or administrative guidance on computation: Not stated in the document.
  • Textual inconsistency in sub-section (1) referring to "provisions of section 296": Not explained in the document.

Differences Between (Document 2) Clause 296 of the Income Tax Bill, 2025 - Old Version and (Document 1) Section 296 of the Income-tax Act, 2025

  • Trigger point for the twelve-month period: Bill uses "twelve months from the end of the month in which the last of the authorisations for search was executed, or requisition was made" (Bill sub-s. (1)). The Act uses "twelve months from the end of the quarter in which the last of the authorisations for search was executed, or requisition was made" (Act sub-s. (1)(a)).
    • Practical impact: The Act lengthens the period by aligning to quarter ends rather than month ends, effectively giving up to approximately three additional months in some cases for completion, reducing pressure on the department (more time) and increasing uncertainty for taxpayers about the precise deadline (wider window).
  • Provision for extension where return-filing time is extended: The Act contains sub-s. (1)(b) stating that if the time for furnishing return u/s 294(1)(a)(v) is extended by 30 days, "twelve months" is to be read as "thirteen months". This is absent in the Bill.
    • Practical impact: Act expressly accommodates administrative extensions for return filing; the Bill silent on that contingency.
  • Seizure/exclusion wording: Bill excludes "the period (not exceeding one hundred eighty days) commencing from the date on which a search is initiated or a requisition is made and ending on the date on which seized or requisitioned items are handed over to the Assessing Officer having jurisdiction over the assessee" (Bill sub-s. (3)). The Act is more specific in sub-s. (3): it refers to assets [as provided in section 261(b)] and material seized or requisitioned [as provided in section 261(i)] are handed over to the Assessing Officer having jurisdiction.
    • Practical impact: Act clarifies the nature of items (cross-referring to section 261 definitions) which may reduce disputes about what constitutes seized items; Bill is more general.
  • Detailed sub-sectioning and drafting refinements: The Act expands certain sub-section numbering and presents the "quarter" rule, an additional clause for extension linked to return-filing, and adds or rearranges textual clarifications for persons u/s 295 (Act sub-s. (5) refers to "twelve months from the end of the quarter in which the notice u/s 294 in pursuance of section 295, was issued ..."). The Bill refers to "end of the month".
    • Practical impact: For "other persons" (section 295), the Act again gives a quarter-end anchor, providing more time compared to the Bill's month-end anchor.
  • Order of exclusions and minor drafting differences: The Act reorders or clarifies some exclusion clauses, and in some instances expands wording to refer to delivery/receipt to Principal Commissioner/Commissioner or Assessing Officer.
  • Practical impact: The Act's drafting appears designed to reduce ambiguity on receipt events and which authority's receipt triggers cessation of exclusion; the Bill is less explicit in certain respects.
  • Other differences: The Act includes an explicit sub-s. (8) and (9) analogous to the Bill but keyed to quarter-end based primary limitations.
    • Practical impact: Overall the Act tends to provide marginally more time and greater specificity on what is excluded and how computation is to be anchored.

Action Points

  • Parties should maintain contemporaneous records establishing dates of search/requisition, dates of handover of seized items, certified copies of court orders, communications for exchange of information, references and reports from Valuation Officer, audit/inventory valuation reports, and Board for Advance Rulings communications.
  • Practitioners should note whether the operative limitation is computed from month-end (Bill) or quarter-end (Act) when advising clients and tracking deadlines; post-enactment, use the Act wording (quarter-end) where applicable.
  • In disputes, ensure pleadings and computation tables explicitly apply the correct anchor (month vs quarter) and list excluded periods with documentary proof of receipt dates.

Full Text:

Section 296 Time-limit for completion of block assessment

Topics

Acts Income Tax