Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Consolidated Show Cause Notices under Sections 73 and 74 and Taxability of School Affiliation Servic...
    Fraudulent Input Tax Credit from Non-Existent Suppliers: Application of Sections 16, 74 and 155 of t...
    Case Laws Money Laundering
    Prolonged Pre-Trial Incarceration and Bail under Section 45 of the Prevention of Money-Laundering Ac...
    Case Laws Income Tax
    Prospective Operation of Section 56(2)(x)(b) in Stamp-Value Difference Cases Involving Immovable Pro...
    Seizure of Cash under Section 67 of the CGST Act and Interest on Illegal Retention
    Case Laws Income Tax
    Disallowance of Salary Expenditure for Allegedly Non-Genuine Services under Section 37
    Case Laws Income Tax
    Fair Market Value of Unquoted Equity Shares Under Section 56(2)(viib) and Rule 11UA
    Refund of Excess IGST Paid on Exports Following Clerical Error in FORM GSTR-3B
    Revocation of Cancellation of GST Registration for Non-Filing of Returns under Section 30 and Rule 2...
    Case Laws Income Tax
    TOLA, Section 149 and the Surviving-Time Test for Reassessment Proceedings
    Case Laws Customs
    Provisional Release of Unseized Imported Food Consignments under the Customs Act, 1962
    Case Laws Customs
    Recovery of Unpaid Anti-Dumping Duty After Self-Assessment Under Section 28 of the Customs Act, 1962
    Project-Wise Anti-Profiteering Methodology in Real Estate under Section 171 of the Central Goods and...
    Case Laws Income Tax
    Retirement Leave Encashment Exemption under Section 10(10AA)(ii) and Retrospective Application of No...
    Transit-State Jurisdiction under GST: Limits on Detention and Penalty in External Inter-State Suppli...
    Post-Facto Shareholder Ratification of Diversion of Preferential Issue Proceeds under the PFUTP Regu...
    Case Laws Income Tax
    Section 195 Withholding on Payments to Non-Residents: Royalty, Fees for Technical Services and Busin...
    Penalty: Scope of "Any Person" under Section 122(1A) of the Central Goods and Services Tax Act, 2017
    Recovery of Corporate Debtor Premises and Proof of Tenancy, Lease or Licence Rights under the Insolv...
    Service of GST Notices through the Common Portal: Statutory Validity and Practical Accessibility
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
School affiliation services fall outside educational exemption without a direct nexus to admissions or examination conduct.
Consolidated show cause notices may combine financial years governed by Sections 73 and 74 where liabilities are segregated period-wise, each component independently meets limitation and notice requirements, the additional ingredients for fraud-based proceedings are satisfied, and no actual prejudice arises. School affiliation and affiliation-form processing charges are independent taxable supplies where they concern institutional eligibility and compliance, rather than directly and immediately relating to student admission or the conduct of examinations. A broad connection with education does not satisfy the educational-services exemption.
Case Laws GST
Show AI Summary
Fraudulent input tax credit requires proof of fictitious supplies, absent goods receipt, and fraud-linked self-assessment, not cancellation alone.
Input tax credit from allegedly non-existent suppliers depends on proof of genuine supply and actual receipt of goods or services, not merely invoices, accounting entries, or banking-channel payments. Section 155 places the burden of establishing ITC eligibility on the claimant. Section 74 requires more than ineligible credit: the wrongful availment must be linked to fraud, wilful misstatement, or suppression to evade tax. Retrospective supplier-registration cancellation is relevant evidence but is not conclusive. A fraud-based notice must disclose facts showing fictitious suppliers, absence of supply, and a basis for inferring the recipient's knowledge or participation.
Case Laws Money Laundering
Show AI Summary
Prolonged pre-trial incarceration may justify conditional PMLA bail when delayed trials make continued detention constitutionally disproportionate.
Section 45 of the Prevention of Money-Laundering Act remains the stringent ordinary bail threshold, requiring prosecutorial opportunity and, on opposition, reasonable grounds to believe that the accused is not guilty and unlikely to offend while on bail. Article 21 nevertheless requires a separate, fact-sensitive inquiry where prolonged pre-trial detention and an unrealistic trial timetable make custody disproportionate. Relevant factors include custody length, trial progress, remaining witnesses, secured documentary evidence, source of delay, predicate-case status, and risks of absconding or witness interference. Conditions such as passport surrender, attendance, non-contact directions, and residence disclosure may safeguard the trial.
Case Laws Income Tax
Show AI Summary
Prospective operation of stamp-value taxation prevents retrospective application where property agreements and substantial payments predate the charging provision.
Section 56(2)(x)(b) applies to immovable property received for inadequate consideration only where its temporal and valuation conditions are satisfied. A stamp-value difference alone does not establish taxability. Where consideration was fixed and substantial payments or contractual performance occurred before the charging provision commenced, later conveyance or registration does not by itself attract the later charge. Agreement-date valuation is available only for covered transactions where consideration was fixed and paid, wholly or partly, through prescribed banking or electronic modes on or before the agreement date. The tax authority must identify the correct statutory basis and provide a meaningful opportunity to respond.
Case Laws GST
Show AI Summary
GST cash seizure limits require statutory relevance and restitutionary interest for unlawfully retained currency following searches.
GST seizure powers cannot be used to take cash as a general investigative measure or security for a possible tax demand. Currency is excluded from goods, and "things" is confined contextually to articles useful or relevant as evidence in GST proceedings. Valid seizure and retention require recorded statutory reasons, procedural compliance and observance of return timelines. Unauthorised retention engages property protections; later return does not cure the deprivation, and accrued interest is restitutionary rather than delayed-refund interest.
Case Laws Income Tax
Show AI Summary
Salary expense genuineness requires proof of actual services, business purpose, and fair testing of adverse third-party statements.
Under Section 37(1), salary expenditure is deductible only where it is actually incurred wholly and exclusively for business purposes and is supported by proof of genuine employment, services rendered, business nexus, and payment. Bank transfers and accounting entries alone are not conclusive. Where a third-party statement is central to an allegation of non-genuine salary, the taxpayer should receive disclosure and a meaningful opportunity to rebut it, including cross-examination where appropriate. A retracted and uncorroborated statement is vulnerable as the sole basis for disallowance.
Case Laws Income Tax
Show AI Summary
Discounted cash flow valuation remains taxpayer-selected under prescribed rules, while tax scrutiny must identify specific valuation-date defects.
The taxpayer may elect a prescribed DCF valuation for unquoted equity shares, and scrutiny of that method does not permit substitution with Net Asset Value merely because it produces a lower fair market value. The Assessing Officer may examine projections, discount rates, terminal assumptions, computations and source data, but rejection requires demonstrably wrong facts, material errors, a wholly erroneous basis or objectively unsupported assumptions. Subsequent financial performance cannot alone invalidate a bona fide DCF valuation; the relevant inquiry remains the reasonableness of valuation-date information.
Case Laws GST
Show AI Summary
Excess IGST on exports remains refundable when later correction triggers automated refund and reconciliation proves duplicate payment.
Refund of excess IGST paid on zero-rated exports may arise where turnover and tax are mistakenly entered under non-zero-rated supplies in FORM GSTR-3B while export invoices and shipping bills are correctly reported in FORM GSTR-1. If the exporter then pays the same IGST in the correct zero-rated field and the automated refund is credited against that later payment, the earlier payment remains a separately identifiable potential excess; its claim is not a repeat request for the same export-tax refund.
Case Laws GST
Show AI Summary
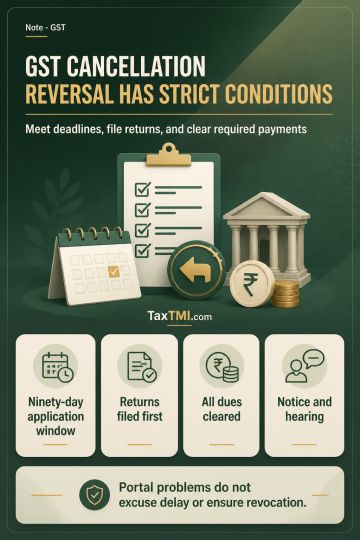
GST registration revocation requires timely application, return compliance, payment of dues, and a reasoned statutory decision.
GST registration revocation after cancellation for return default is a conditional, time-bound process. An application under Section 30 and Rule 23 must ordinarily be filed within ninety days, subject to prescribed extension, and cannot be made until pending returns are filed and tax, interest, penalty and late fee are paid. Portal non-acceptance may permit online or physical submission where technically unavailable, but does not condone delay or ensure revocation. The competent authority must assess statutory eligibility, sufficient grounds and compliance while following notice and hearing requirements before rejection.
Case Laws Income Tax
Show AI Summary
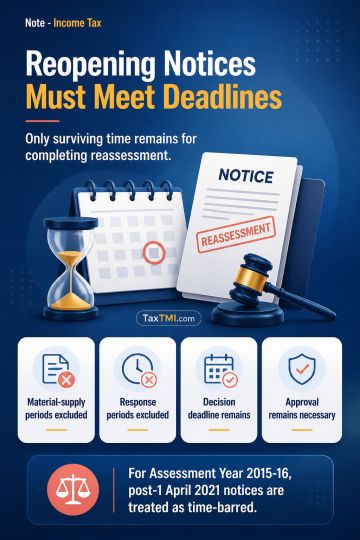
Reassessment limitation under TOLA requires final notices to issue within surviving time and satisfy statutory safeguards.
Reassessment limitation under TOLA is a jurisdictional restraint. Transitional notices issued between 1 April 2021 and 30 June 2021 are treated as Section 148A(b) show-cause notices, but only the surviving time remaining until 30 June 2021 is available for completing the reassessment process. Periods for supply of material and the assessee's response are excluded, but the Section 148A(d) decision, statutory approval and final Section 148 notice must issue within the remaining period. For Assessment Year 2015-16, post-1 April 2021 notices are treated as time-barred.
Case Laws Customs
Show AI Summary
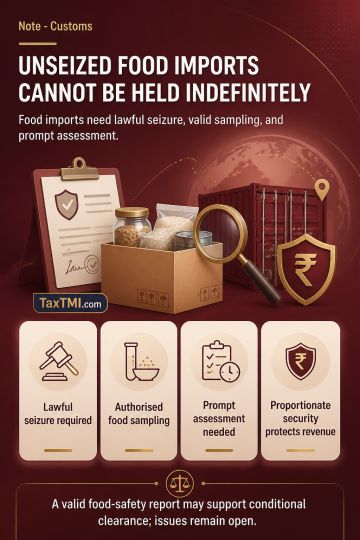
Unseized food consignments cannot face indefinite detention without lawful seizure, valid sampling, and prompt assessment.
Provisional release of an unseized imported food consignment is not mechanically governed by Section 110A, which applies to goods seized under Section 110. Customs may examine, test, verify and reassess imports, but indefinite retention without a seizure memorandum or disclosed reasons connecting the goods with confiscation is not justified. Food sampling should follow the specialised food-safety process through an authorised officer. A valid food-safety report may support conditional clearance, while classification, duty liability, confiscation and adjudication remain open. Revenue may be protected through proportionate security.
Case Laws Customs
Show AI Summary
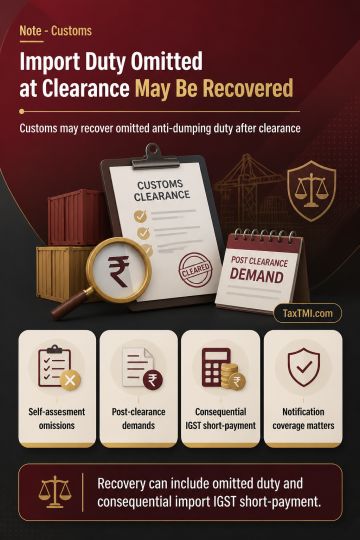
Anti-dumping duty recovery permits post-clearance demands and consequential import IGST where self-assessment omitted an applicable levy.
Unpaid anti-dumping duty omitted during self-assessment may be pursued through the customs recovery procedure without prior appellate modification of the self-assessment. The recovery framework applies to anti-dumping duty through statutory incorporation of provisions concerning assessment, non-levy, short-levy, interest and recovery. Where anti-dumping duty is chargeable, it forms part of the aggregate value used to compute IGST on imports, potentially creating a consequential IGST short-payment. Recovery requires accurate assessment of notification coverage, product, origin, rate, valuation, limitation and procedural safeguards.
Case Laws GST
Show AI Summary
Project-wise anti-profiteering requires actual input tax credit measurement and area-based allocation of benefits to real-estate purchasers.
Real-estate anti-profiteering under Section 171 requires project-level identification of additional input tax credit and allocation of the saving across total project area on a per-square-foot basis. Purchase value may quantify credit attributable to project expenditure, but turnover or collections cannot serve as the allocation basis. The comparison must use pre-GST credit actually availed rather than merely available credit. GST collected on consideration inflated by an undistributed benefit forms part of the amount not passed on and remains distinct from statutory interest.
Case Laws Income Tax
Show AI Summary
Retirement leave encashment exemption applies under the enhanced notified ceiling while preserving non-government employee classification and statutory conditions.
Section 10(10AA)(ii) governs retirement leave-encashment exemption for non-Government employees, subject to the ten-month earned-leave measure, average-salary computation, and the notified monetary ceiling. Notification No. 31/2023 specifies an enhanced ceiling of Rs. 25,00,000, is deemed effective from 1 April 2023, and certifies that retrospective effect causes no adverse effect. The enhanced ceiling is treated as a remedial rationalisation of an existing exemption and may govern pending earlier-period matters, while preserving the distinction between Government and non-Government employees.
Case Laws GST
Show AI Summary
Transit GST jurisdiction limits detention penalties for documented inter-State supplies lacking a local taxable nexus.
Transit-State jurisdiction under GST permits interception, document production, e-way bill verification and authorised physical inspection of goods moving through an intermediate State. It does not, in a pure transit movement, support detention-related penalty for an external inter-State supply where origin and destination lie outside the intercepting State, no tax is payable there, and there is no evidence of diversion, local supply, fictitious or mismatched documents, or mismatch of goods. Cross-empowerment is administrative and does not create an independent territorial taxable nexus.
Case Laws SEBI
Show AI Summary
Shareholder ratification cannot cure preferential-issue fund diversion when disclosed objectives are abandoned, triggering securities-market fraud and disclosure concerns.
Post-facto shareholder approval cannot retrospectively validate diversion of preferential-issue proceeds contrary to issue-specific objects disclosed to shareholders and the market. A special resolution authorises the issue but does not permit unrestricted use of proceeds. Periodic deviation reporting, audit-committee review and utilisation disclosures promote transparency; they do not enable diversion followed by later regularisation. Immediate diversion, inadequate commercial justification and missing documentation may indicate that disclosed objects were not genuinely intended to be performed. Later amendment of corporate objects or shareholder ratification cannot cure a completed securities-market disclosure breach.
Case Laws Income Tax
Show AI Summary
Cross-border software payments require copyright-right, technical-service, and permanent-establishment analysis before withholding obligations are determined under applicable treaties.
Section 195 requires withholding only from a remittance to a non-resident that includes income chargeable in India. For software, royalty depends on transfer of copyright rights, not merely the right to install, access, use, or distribute a copyrighted article under restrictive terms. Where a DTAA is more beneficial, its royalty and FTS definitions control; treaty FTS may require technology to be made available. Amounts that are neither royalty nor FTS require consideration as business profits, ordinarily taxable only where profits are attributable to a permanent establishment. Composite payments require component-wise allocation and analysis.
Case Laws GST
Show AI Summary
Personal GST penalty requires proof that the beneficiary retained benefit and directed a covered invoice or credit transaction.
Section 122(1A) may impose personal GST penalty on a registered or unregistered person only for a covered invoice or input tax credit transaction. Liability requires cumulative proof that the individual retained an identifiable personal benefit and that the transaction was conducted at that person's instance. Directorship, employment, registration, signature authority, or association with the taxable entity neither independently establishes nor excludes liability. Proceedings require transaction-specific and person-specific allegations and findings. The provision operates prospectively for underlying acts or transactions occurring on or after 01.01.2021.
Case Laws IBC
Show AI Summary
Proof of tenancy rights governs insolvency recovery of corporate-debtor premises from occupants lacking enforceable possessory interests.
Where premises form part of the corporate debtor's assets, Sections 18 and 25 of the Insolvency and Bankruptcy Code, 2016 require the resolution professional to take custody, control, preservation and protection measures. An occupant resisting recovery must prove a subsisting tenancy, leasehold interest or enforceable licence through reliable evidence of the parties' intended relationship and its essential terms. Permission to stock goods or conduct limited business activity, prolonged occupation, and business or utility records do not independently create rights in the premises. Section 60(5)(c) supports insolvency jurisdiction over asset-recovery measures connected with the insolvency estate.
Case Laws GST
Show AI Summary
GST portal service requires statutory validity and practical accessibility before ex parte adjudication can fairly proceed.
GST portal service is a statutory method under Section 169, but its use in an ex parte demand proceeding depends on effective accessibility and a meaningful opportunity to reply and be heard. Rule 142 requires electronic DRC-01 and DRC-07 summaries to operate alongside the underlying show-cause notice and reasoned order. Portal placement, complete communication, e-mail transmission, technical reliability and proof of actual access may determine whether service is effective, whether waiver applies, and whether appellate limitation begins.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Comparison of Section 108 "Set off of losses under same head of income." between the Income-Tax Act, 2025 (as passed) and the Income-Tax Bill, 2025 (as originally introduced)

1 September, 2025

Contents
Acts
Rules & Regulations
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Section 108 Set off of losses under same head of income.

Income-tax Act, 2025

At a Glance

These materials compare Clause 108 of the Income Tax Bill, 2025 - (Old Version) with Section 108 as enacted in the Income-tax Act, 2025. Both provisions regulate intra-head set-off of losses, including the special rules for capital gains. The provisions affect taxpayers who realise losses and gains under the same head (notably capital gains) and the tax administration that applies set-off rules. Effective date or decision date: Not stated in the document.

Background & Scope

Statutory hook: Chapter VII, "Set off, or Carry Forward and Set off of Losses," Income-tax Act/Bill, 2025. The clauses address intra-head set-off of losses. The text explicitly excludes "Capital gains" from the general rule in sub-section (1) and then dedicates sub-section (2) to rules for capital gains losses u/ss 72 to 90. Definitions of "short-term capital asset" and "long-term capital asset" are Not stated in the document. Cross-references: sections 72 to 90 are referenced as the computational framework for capital gains; the content of those sections is Not stated in the document.

Statutory Provision Mode

Text & Scope

Clause 108 (Old Version) contains two operative parts:

  • Sub-section (1): A general rule for the same head (excluding capital gains). If the net result from any source under any head of income (other than "Capital gains") is a loss for a tax year, the assessee may set off such loss against income from any other source under the same head for that tax year.

  • Sub-section (2): Specific rules for capital gains losses computed u/ss 72-90. Losses arising from transfer of a capital asset are classified by whether the asset is long-term or short-term and the set-off permitted differs accordingly:

    • (a) Loss arising from transfer of a long-term capital asset shall be set off only against gains, if any, from transfer of another long-term capital asset.

    • (b) Loss arising from transfer of a short-term capital asset shall be set off against gains, if any, from transfer of any capital asset.

Interpretation

Legislative intent as expressed by the text: the statute draws a distinction between capital gains and other income heads. It preserves the conventional tax treatment that long-term capital losses are more restricted - they cannot be used to offset short-term capital gains or other forms of income - whereas short-term capital losses are more freely available against gains from any capital asset. The language indicates an intent to confine cross-category set-off within the capital gains head to protect the treatment accorded to long-term capital gains (often taxed differently) while allowing short-term losses to mitigate capital gains across categories.

Exceptions/Provisos

No provisos, exceptions, time-limits or carry-forward rules are stated in Clause 108 of the Bill. Carry-forward of unabsorbed losses, conditions for set-off in subsequent years, or special carve-outs (e.g., for specified transactions) are Not stated in the document.

Illustrations

  • Example 1: Taxpayer A has, in one tax year, a loss of Rs. 100,000 on transfer of a short-term equity holding (short-term capital loss) and a gain of Rs. 80,000 on transfer of a long-term property (long-term capital gain). Under Clause 108(2)(b) the short-term capital loss can be set off against the long-term capital gain. (All numeric facts hypothetical but consistent with the text.)

  • Example 2: Taxpayer B has a long-term capital loss of Rs. 50,000 from sale of a long-term asset and a short-term capital gain of Rs. 30,000 in the same year. Under Clause 108(2)(a) the long-term loss cannot be set off against the short-term gain; it may be set off only against gains from transfer of another long-term capital asset. If no such gains exist, set-off in that year is precluded by Clause 108(2)(a).

Interplay

Clause 108 cross-references sections 72 to 90 as the computational framework for capital gains: the Bill contemplates that capital gains/loss computation, classification and quantum will be governed by those sections. Other interactions - for example with provisions on carry-forward and set-off across subsequent years, tax rates, or special exemptions - are Not stated in the document.

Summary of Differences between Clause 108 of the Income Tax Bill, 2025 - (Old Version) with Section 108 of the Income-tax Act, 2025

  • Structure and Wording of Capital Gains Set-off Rules
    Difference: Section 108(2) of the Act divides capital asset losses into two specific categories: (a) short-term capital asset loss set off against income from any other capital asset; and (b) long-term capital asset loss set off only against income from any other long-term capital asset. The Bill (Clause 108(2)) reverses the emphasis and frames the rule as: (a) loss from a long-term capital asset shall be set off only against gains (if any) from transfer of another long-term capital asset; (b) loss from a short-term capital asset shall be set off against gains (if any) from transfer of any capital asset.

    Practical impact: The Act's text appears to permit short-term losses to be set off against any other capital asset income (which would include both STCG and LTCG), and long-term losses only against other long-term capital income. The Bill's text expressly states the converse ordering but functionally is similar except for phrasing: Bill explicitly allows short-term losses to be set off against gains from any capital asset (including long-term), and restricts long-term losses to long-term gains only. The primary practical consequence is clarity: the Bill is explicit that long-term capital losses cannot be used against short-term capital gains, whereas the Act also contains that restriction but phrases the short-term rule as set off against "any other capital asset" which may be read the same; the Bill's framing is marginally clearer on the directional limitation for long-term losses.

  • Placement and Minor Wording Variations
    Difference: The Act uses the heading "(2) Where the net result of computation of income made for any tax year u/ss 72 to 90 in respect of-" followed by two subparagraphs (a) and (b) specifying short-term and long-term capital assets. The Bill uses "(2) Any loss, as a result of computation made u/ss 72 to 90, for any tax year, arising from transfer of a capital asset as arrived at under a similar computation made for the tax year in respect of any other capital asset being,--" followed by (a) and (b).

    Practical impact: This is a drafting difference only; the Bill's version is slightly more verbose and emphasizes that the loss is "arising from transfer of a capital asset." No substantive change in coverage is evident from the texts provided.

  • Explicit Cross-References to "Capital gains" Exclusion
    Difference: Both texts exclude "Capital gains" from clause (1) by the parenthetical "(other than "Capital gains")" when addressing set-off under the same head. There is no substantive difference here.

    Practical impact: No change; both provisions maintain capital gains as a special category requiring separate rules under clause (2).

  • Overall Substance
    Difference: There is no substantive divergence in the fundamental rule that losses under the same head can be set off against other sources within that head and that capital gains have specialized set-off rules distinguishing short-term and long-term losses. The Bill's text is slightly different in ordering and phraseology concerning which category of loss can be set off against which gains.

    Practical impact: Tax practitioners can treat the provisions as substantively aligned; however, reliance on the enacted Act (Section 108) rather than the Bill text is necessary for certainty. The practical effect on taxpayers' ability to set off capital losses appears unchanged: long-term capital losses are confined to long-term capital gains, whereas short-term capital losses may be applied against gains from any capital asset.

Practical Implications

  • Compliance and risk areas: Taxpayers must correctly classify capital asset transfers as short-term or long-term (classification rules Not stated in the document) because the permissible intra-head set-off depends on that classification. Misclassification could lead to incorrect set-off, reassessment risk, or tax litigation.
  • Record-keeping/evidence: Though the Bill does not prescribe records, taxpayers will need contemporaneous evidence of acquisition date, sale date, and computation of capital gains/losses (Not stated in the document as express requirements). Retention of documentation supporting holding period and computation is implied by the need to establish short-term vs long-term status.
  • Tax planning constraints: The rule restricting long-term capital losses to long-term gains limits the utility of such losses to offset short-term gains or other capital gains in the year - affecting timing strategies for disposal of assets where taxpayers seek to utilise losses against higher taxed or immediate gains.

Key Takeaways

  • Clause 108 distinguishes general intra-head set-off (excluding capital gains) from specific capital gains set-off rules.
  • Long-term capital losses are limited to set-off only against long-term capital gains in the same year.
  • Short-term capital losses can be set-off against gains from transfer of any capital asset in the same year.
  • The Old Version (Bill) and the enacted Section 108 are substantively consistent; differences are primarily in ordering and phrasing.
  • The Bill does not state definitions of short-term/long-term, carry-forward rules, effective date, or administrative procedures - these are Not stated in the document.
  • Accurate classification of capital assets and maintenance of records supporting holding periods and computations are essential for correct application.
  • Absence of express exceptions or cross-year carry-forward language in Clause 108 means readers must consult other provisions (Not stated here) for such rules.

Full Text:

Section 108 Set off of losses under same head of income.

Topics

Acts Income Tax