Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Refund of Accumulated Input Tax Credit on Packing Materials under Section 54(3)(ii) of the CGST Act
    Detention of Goods in Transit: Consequences of Delay in Notice under Section 129(3)
    Case Laws Income Tax
    Section 192 TDS on Leave Travel Concession and the Effect of Subsisting Judicial Restraint
    Cross-Segment Price Manipulation in Stock Derivatives under the SEBI Act and PFUTP Regulations
    Case Laws Income Tax
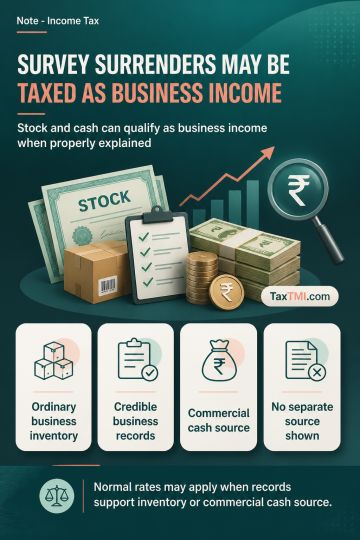
    Enhanced Rate of Tax u/s 115BBE: Survey Surrenders of Excess Stock and Cash: Business Income, Deemed...
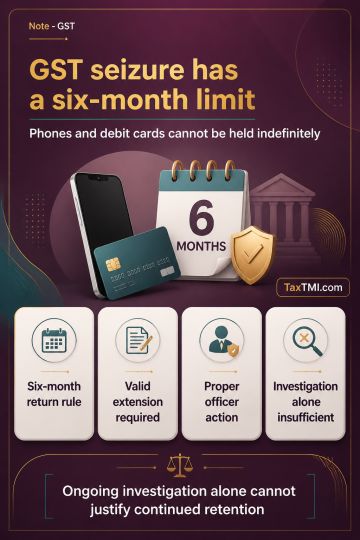
    Retention of Seized Mobile Phones and Bank Debit Cards Beyond the Section 67(7) Period
    Case Laws Customs
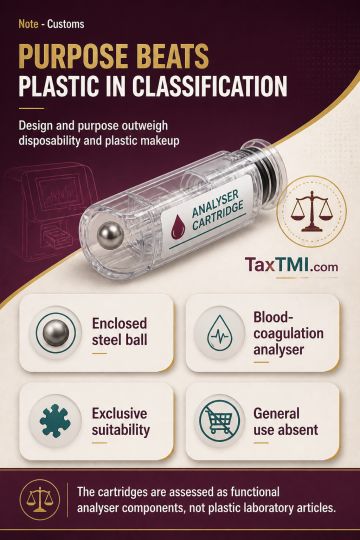
    Classification of Disposable Analytical Cartridges under Chapter 90 and Heading 3926
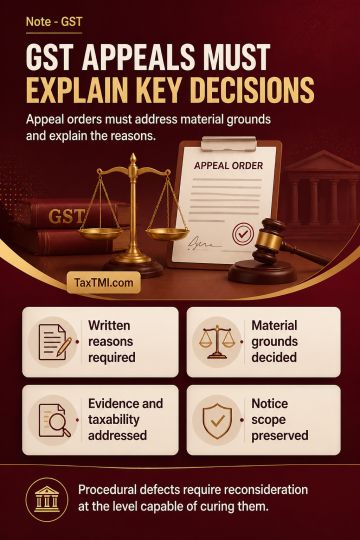
    Reasoned and Speaking Appellate Orders u/s 107 of the CGST Act: Duty to Decide Material Grounds of A...
    Pre-Movement E-Way Bill Compliance and Section 129 Detention for Undocumented Goods in Transit
    Case Laws Income Tax
    Faceless Reassessment Jurisdiction: Retrospective Validation under Section 147A and Automated Alloca...
    Doctrine of Merger: Effect of Non-Speaking and Speaking Dismissal of Special Leave Petitions on Merg...
    Case Laws Indian Laws
    Section 37 of the NDPS Act: Twin Conditions for Grant of Bail in Commercial Quantity Cases
    Case Laws Customs
    Pilferage of Imported Goods: Approval, Custody and Duty Liability under the Customs Act, 1962
    Case Laws Indian Laws
    Condonation of Delay in Statutory Appeals under Section 5 of the Limitation Act, 1963
    Case Laws Income Tax
    Condonation of Delay for Filing Revised Returns under Section 119(2)(b): Genuine Hardship and Merits...
    Case Laws Income Tax
    TDS Credit Where the Deductor Defaults: Proof of Deduction Without Form 16 or Form 16A
    Case Laws Indian Laws
    Reserved High Court Judgments: Constitutional Timelines, Accountability and Litigant Remedies
    Price Depression in Securities Markets: Evidentiary Requirements under the PFUTP Regulations
    Case Laws Income Tax
    Foreign Leave Travel Concession and Tax Deduction at Source under Sections 10(5), 192 and 201
    Refund of Accumulated Input Tax Credit under Inverted Duty Structure: Section 54(3)(ii) and Rule 89(...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
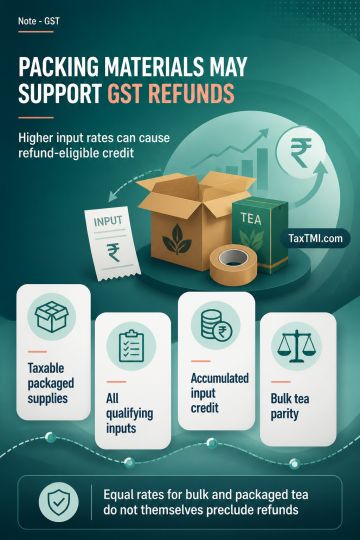
Packing-material input tax credit may support inverted-duty refunds when higher-rated inputs cause accumulation for taxable packaged supplies.
Refund of accumulated input tax credit under Section 54(3)(ii) may arise where packing materials used to make taxable packaged outward supplies bear a higher tax rate than the outward supply and generate the accumulation. The inquiry extends to all qualifying inputs and is not limited to a principal raw material. Parity between the rate on bulk tea and packaged tea does not itself preclude refund if higher-taxed packing materials used for the packaged supply are the cause of unutilised credit.
Case Laws GST
Show AI Summary
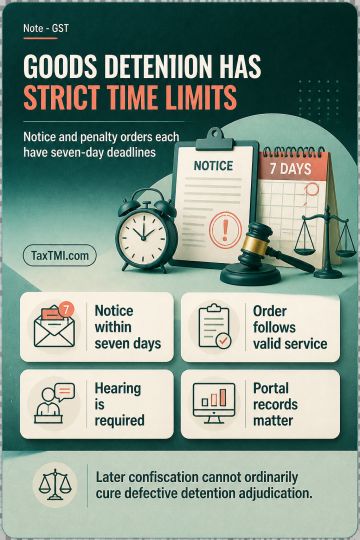
Mandatory detention timelines require timely notice, hearing and penalty order, preventing prolonged restraint of goods in transit.
Section 129(3) establishes a mandatory two-stage timeline: issuance of the penalty notice within seven days of formal detention or seizure, followed by a penalty order within seven days of legally effective service. The periods are independent, and compliance at one stage cannot cure delay at the other. Service, portal timestamps and the electronic records required under Rule 142 are material to chronology. Penalty requires a hearing, while payment under protest may still require a reasoned order to preserve appellate access. Later confiscation action cannot ordinarily cure a defective detention adjudication.
Case Laws Income Tax
Show AI Summary
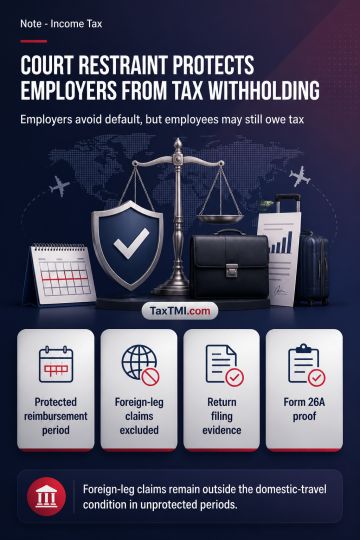
Subsisting judicial restraint on leave travel concession withholding prevents employer default while preserving employees' underlying tax liability.
A subsisting judicial restraint expressly prohibiting deduction from leave travel concession reimbursements governs the employer's withholding conduct for the covered period. Non-deduction in compliance with that restraint cannot constitute failure to discharge an enforceable duty under Sections 192 and 201, even if the underlying exemption claim is later found substantively unavailable. The restraint does not eliminate employee-level tax liability. For unprotected periods, foreign-leg or circuitous travel claims remain outside the domestic-travel condition, and payer protection may depend on proving employee return filing, income inclusion and tax payment through Form 26A.
Case Laws SEBI
Show AI Summary
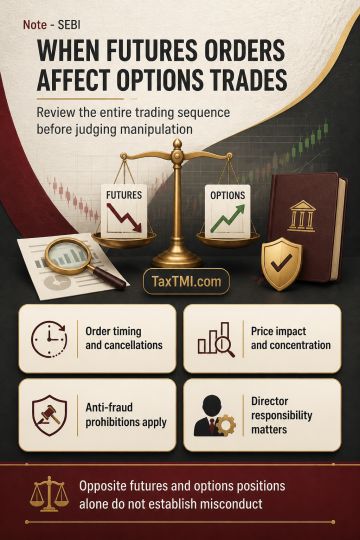
Cross-segment price manipulation examines whether futures orders artificially influence option executions, engaging anti-fraud rules, director responsibility, and interim safeguards.
Cross-segment price manipulation may arise where aggressive futures orders alter the last traded price or visible order-book conditions so that larger, sentimentally opposite options orders obtain favourable execution. The relevant inquiry considers the integrated sequence of resting orders, aggressive executions, cancellations, timing, concentration, price impact and delta-adjusted exposure. Anti-fraud prohibitions cover manipulative devices, false appearances of trading and price manipulation, while opposite futures and options positions alone do not establish misconduct. Director liability requires responsibility for business conduct, or consent, connivance or neglect.
Case Laws Income Tax
Show AI Summary
Survey surrender characterisation determines whether excess stock and cash are taxed as business income or under special deemed-income provisions.
The special regime in Section 115BBE is consequential: it applies only after the amount is properly brought within a specified deeming provision, and a survey surrender, book entry or return description cannot itself create that character. Mixed stock forming part of ordinary business inventory and credibly explained through business records may be assessed as business income at normal rates. Similarly, excess cash may be treated as business income where a commercial source is satisfactorily established and no separate or non-business source is shown.
Case Laws GST
Show AI Summary
Statutory limits on GST seizure require return of retained mobile phones and debit cards without a valid extension.
Section 67(7) establishes a six-month return rule where no notice in respect of seized goods is issued. Any further period requires sufficient cause, action by the proper officer, and a maximum further period of six months; ongoing investigation cannot replace an actual extension order. Although Section 67(7) uses "goods" while Section 67(2) also covers documents, books and things, its application to seized mobile phones and bank debit cards indicates that classification cannot be used to avoid the temporal restriction where articles are held under statutory seizure.
Case Laws Customs
Show AI Summary
Analytical cartridge classification follows functional integration and sole-use suitability, not plastic composition, disposability, or general consumable character.
STA micro-cuvettes containing an enclosed steel ball are assessed as complete functional components of a blood-coagulation analyser, rather than merely as plastic laboratory articles. Classification turns on their objective design, analytical role, exclusive or principal suitability and absence of practical general use. Chapter 90 Note 2 requires consideration of an independent specific heading first and then classification of other dedicated parts or accessories with the relevant instrument. Disposable or single-use status and plastic composition do not by themselves establish classification as residual plastic articles.
Case Laws GST
Show AI Summary
Speaking appellate orders require findings on material GST appeal grounds, ensuring fair hearings and meaningful higher review.
Section 107(12) requires a written appellate order identifying material points for determination, deciding them, and giving reasons. Formulaic confirmation of original assessment does not establish independent appellate consideration, particularly where jurisdiction, notice, evidence, quantification, taxability, section 74 conditions, interest, or penalty are contested. Sections 74 and 75 require a defined notice, disclosure of relied-upon material, effective hearing, and reasoned determination within the notice's scope. Where procedural defects arise at the original stage as well as on appeal, reconsideration must occur at the level capable of curing the foundational defect without expanding the show-cause case.
Case Laws GST
Show AI Summary
Pre-movement e-way bill compliance requires invoices and transport records before dispatch, while later documents cannot cure undocumented transit.
Pre-movement e-way bill compliance requires issuance of an invoice at or before removal, generation of the e-way bill before road movement, and carriage of both records during transit. Where goods are intercepted without either record, the contravention arises upon commencement of undocumented movement; documents generated only after interception cannot retrospectively establish compliance. Such documents may still be considered with other contemporaneous evidence when assessing bona fides or alleged intent to evade tax. Section 129 detention proceedings remain subject to notice, hearing, electronic-summary and statutory-timeline requirements.
Case Laws Income Tax
Show AI Summary
Automated allocation in reassessment determines officer jurisdiction, while retrospective validation cannot bypass continuing faceless-scheme requirements.
Section 151A and the e-Assessment of Income Escaping Assessment Scheme, 2022 require covered reassessment functions and section 148 notice issuance through automated allocation. Risk-based selection of cases is distinct from randomised allocation of the officer authorised to act. Sections 148A and 148 form an integrated reassessment sequence, so general concurrent jurisdiction, administrative instructions or digital service cannot substitute for the prescribed faceless allocation. Section 147A did not amend the continuing statutory and scheme-based allocation requirements and is treated as constitutionally invalid.
Case Laws GST
Show AI Summary
Doctrine of merger distinguishes refusal of special leave from appellate disposal, preserving review subject to independent procedural limits.
Under Article 136, a refusal of special leave remains a discretionary leave-stage determination. A non-speaking dismissal does not merge the challenged lower-court decision into a Supreme Court order, affirm its reasoning, or automatically create res judicata. A speaking refusal may bind only as to legal propositions expressly declared under Article 141, without producing merger. Merger arises when leave is granted and appellate jurisdiction is exercised. Review, writ, and remanded proceedings remain subject to independent procedural requirements, including limitation and safeguards against abuse.
Case Laws Indian Laws
Show AI Summary
NDPS commercial-quantity bail requires independent proof of non-guilt and low reoffending risk alongside proportionate safeguards.
Section 37 of the NDPS Act imposes cumulative bail conditions in commercial-quantity cases: the court must find reasonable grounds to believe the accused is not guilty and unlikely to reoffend while on bail. These requirements supplement ordinary bail factors and demand a genuine, provisional assessment of credible material. Personal liberty and trial delay remain relevant, but must be reconciled with the statutory threshold. Bail conditions, including verification safeguards for foreign nationals, must be proportionate, genuine and capable of enforcement.
Case Laws Customs
Show AI Summary
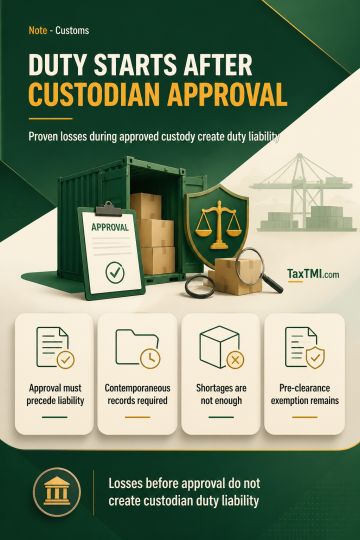
Approved customs custodians bear duty for proven pilferage during custody, but not for losses before their approval takes effect.
Customs-duty liability for pilfered imported goods arises only where pilferage occurs after unloading in a customs area while goods are held by an approved custodian. Approval is indispensable; factual control or statutory custody alone does not impose this liability for a period before approval. Importer duty exemption for pre-clearance pilferage operates alongside the custodian's revenue liability. Pilferage must be proved through contemporaneous records and cannot be presumed from every cargo discrepancy, shortage, or loss.
Case Laws Indian Laws
Show AI Summary
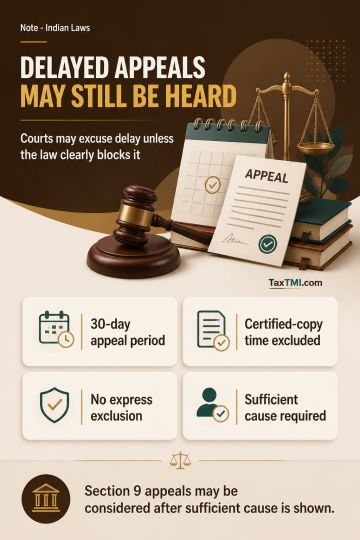
Condonation of delay under Section 5 remains available in special statutory appeals unless the governing scheme clearly excludes it.
Section 5 of the Limitation Act, 1963 applies to a special statutory appeal through Section 29(2) unless the governing enactment excludes it expressly or by necessary implication. A special limitation period alone is insufficient to exclude condonation. Restrictive language, a defined maximum condonable period, or a complete statutory limitation code may create a non-extendable outer limit. Section 9 of the Chhattisgarh Rajya Suraksha Adhiniyam contains a 30-day appeal period and excludes certified-copy time, but lacks an express bar or outer condonation ceiling; delay may therefore be considered upon proof of sufficient cause.
Case Laws Income Tax
Show AI Summary
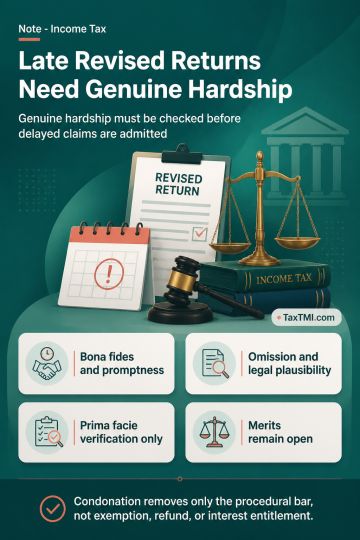
Genuine hardship in delayed revised-return claims requires prima facie verification without converting condonation into final tax adjudication.
Section 119(2)(b) may permit admission of a delayed revised-return claim where expiry of the Section 139(5) period causes genuine hardship. Condonation removes only the procedural bar and does not establish exemption, refund, or interest entitlement. Genuine hardship requires assessment of bona fides, the nature of the omission, promptness after discovery, legal plausibility, and the consequence of refusal. Circular No. 9/2015 permits prima facie verification and inquiry, but substantive taxability and refund entitlement remain for merits examination.
Case Laws Income Tax
Show AI Summary
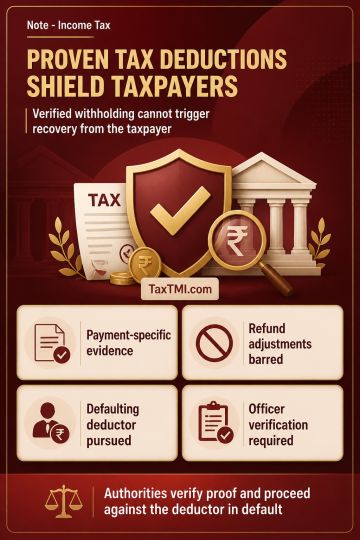
TDS credit after verified deduction protects taxpayers from demands and refund adjustments caused by deductor default.
TDS credit in domestic deductor-default cases depends on verified actual deduction from the taxpayer's income, not solely on deposit, TDS statements, Form 16 or Form 16A, or Form 26AS reflection. Section 205 bars direct or indirect recovery, including refund adjustment, to the extent tax was deducted. The taxpayer must provide reliable payment-specific evidence, and the Assessing Officer must verify the claim while the Department proceeds against the defaulting deductor.
Case Laws Indian Laws
Show AI Summary
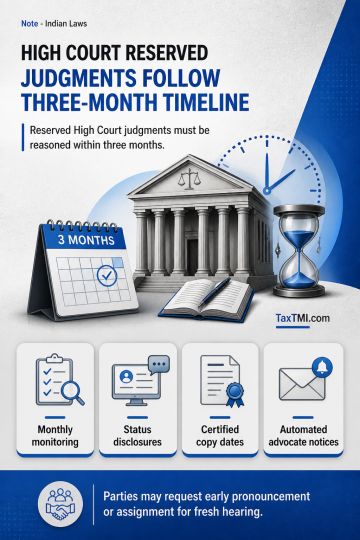
Timely reserved judgments: a three-month framework, transparency, and staged remedies protect liberty and require reasoned decisions.
Reserved High Court judgments are subject to a three-month framework for a reasoned pronouncement, supported by monthly monitoring, status disclosures, date-recorded certified copies, and automated notice to advocates. Urgent matters may receive an operative-part pronouncement, but reasons must be uploaded within seven days or, where practical difficulties exist, within fifteen days. Parties may seek early pronouncement after the specified period and, after further delay, request withdrawal and assignment for a fresh hearing.
Case Laws SEBI
Show AI Summary
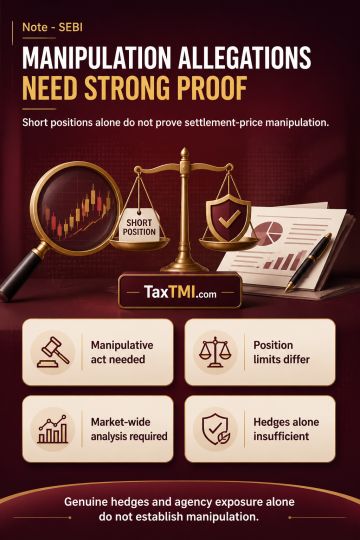
Settlement-price depression allegations require cogent proof of manipulation, not merely short exposure, closing sales, or position-limit non-disclosure.
Settlement-price depression under the PFUTP framework requires cogent proof of a manipulative act, device, scheme or artifice, not merely a substantial short derivative position, closing-window sales, or an incentive to benefit from a lower settlement price. Position concentration and position-limit non-disclosure are distinct from PFUTP fraud. Sales below the last traded price require market-wide causal analysis of other trading activity, execution mechanics, benchmark methodology, commercial rationale, and actual price impact. A genuine hedge and agency-attributed exposure do not, without further proof, establish manipulation.
Case Laws Income Tax
Show AI Summary
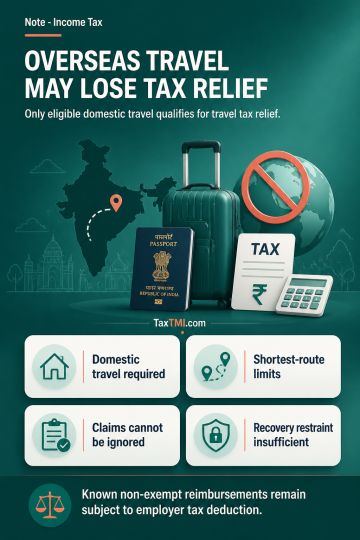
Foreign LTC tax exemption requires domestic travel; employers must deduct tax on known non-exempt travel reimbursements.
Foreign LTC/LFC payments for itineraries containing an overseas leg are outside the Section 10(5) exemption, which is confined to actual eligible domestic travel subject to Rule 2B shortest-route and fare conditions. Under Section 192, employers must include known non-exempt payments in estimated salary and deduct tax; they cannot disregard available claim records showing foreign or circuitous travel. A recovery restraint does not automatically suspend the deduction obligation. Section 201 recipient-compliance conditions, interest, and penalty based on reasonable cause require separate analysis.
Case Laws GST
Show AI Summary
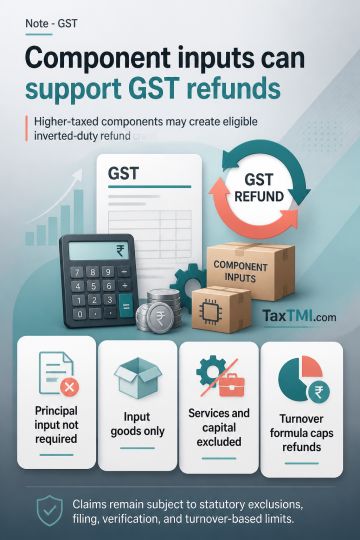
Inverted-duty GST refunds remain available where higher-taxed component inputs, rather than only principal inputs, cause accumulated eligible credit.
Refund of accumulated unutilised ITC under an inverted-duty structure depends on a causal link between higher-taxed input goods and lower-taxed output supplies. The test is not restricted to the principal raw material; higher-rated component inputs may support a claim despite parity between the principal input and output. Refund remains confined to credit on input goods, excluding input services and capital goods. Rule 89(5) separately determines the maximum refundable amount through its turnover-based formula, subject to statutory exclusions and prescribed filing and verification requirements.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Comparison of Section 104 "Unexplained asset." between the Income-Tax Act, 2025 (as passed) and the Income-Tax Bill, 2025 (as originally introduced)

1 September, 2025

Contents
Acts
Rules & Regulations
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Section 104 Unexplained asset.

Income-tax Act, 2025

At a Glance

These texts are two versions of the same provision dealing with "unexplained asset" in the context of aggregation of income: (i) Clause 104 of the Income Tax Bill, 2025 (Old Version) and (ii) Section 104 of the Income-tax Act, 2025 (enacted text). They matter because they prescribe when an asset discovered with a taxpayer may be treated as the taxpayer's income. Affected parties include taxpayers, tax authorities (Assessing Officers) and advisers in personal taxation and compliance. Effective date or decision date: Not stated in the document.

Background & Scope

Statutory hooks: both texts appear as Clause/Section 104 under the heading "AGGREGATION OF INCOME" in the Income Tax Bill/Act, 2025. Both define circumstances under which an asset found to be owned by or belonging to an assessee, but not recorded (or where there is an excess over recorded amount), may be deemed income. Both texts provide a non-exhaustive definition of "asset" in a separate sub-paragraph, expressly including money, bullion, jewellery, virtual digital asset or other valuable article. No further definitions or explanations (for example, of "value", "found", "books of account" or "virtual digital asset") are provided in the documents themselves.

Statutory Provision Mode

Text & Scope

Both provisions operate on two factual situations: (A) an asset is found to be owned by or belonging to the assessee and is not recorded in the assessee's books of account (if any); or (B) the Assessing Officer finds that the asset's measure (either described as "amount of such asset" in the Bill or "amount expended in acquiring such asset" in the Act) exceeds the amount recorded in the books of account. If either situation exists and the assessee either (a) offers no explanation as to nature and source of acquisition, or (b) offers an explanation that is not satisfactory to the Assessing Officer, then the value (or excess amount) is to be deemed income of the tax year in which the asset is found to be owned by or belonging to the assessee. Paragraph (2) in both texts lists examples of "asset", expressly including virtual digital asset.

Interpretation

The enacted text replaces the Bill's phrase "amount of such asset" with "the amount expended in acquiring such asset." This change indicates a legislative choice to focus on acquisition expenditure rather than on some other measure of the asset's worth (for instance, current market value or book value), although the document itself does not state an explicit legislative intent or commentary explaining the reason for the change. The provision vests subjective assessment power in the Assessing Officer by referencing the Assessing Officer's satisfaction with the explanation; no objective standards or burden-allocation rules are provided in the text.

Exceptions/Provisos

Not stated in the document.

Illustrations

  • Example 1 (consistent with the text): An assessee is found to own unreported jewellery. The assessee cannot satisfactorily explain the source of acquisition; the value of that jewellery is therefore deemed the assessee's income for the tax year in which the jewellery was found.

  • Example 2 (illustrating the textual difference): Under the Bill language, if an asset's market value (amount of such asset) exceeded its recorded amount in books, the excess could be treated as income; under the Act language, the focus would be on whether the amount expended in acquiring the asset exceeds the recorded amount - for example, where acquisition expenditure (purchase price) is more than the recorded amount, that excess would be deemed income, even if current market value differs. (These are text-consistent hypotheticals; the document contains no factual cases.)

Interplay

Interaction with other statutory provisions, Rules, Notifications or Circulars: Not stated in the document. The text does not set out procedural rules (assessment procedure, burden of proof, notice requirements, appeals, or valuation methodology), nor does it cross-reference evidentiary standards or other sections addressing unexplained investments, search and seizure, or income determination.

Practical Implications

  • Compliance and risk areas: The provision creates a clear compliance risk where assets are discovered that are not reflected in a taxpayer's books. The Assessing Officer has a statutory power to deem such assets (or excess acquisition expenditure) as income if no satisfactory explanation is given. Taxpayers should be aware that the statutory reach includes virtual digital assets (VDAs), money, bullion and jewellery.
  • Record-keeping/evidence points suggested by the text: Because the outcome is triggered by lack of satisfactory explanation, maintaining contemporaneous evidence of source and acquisition (invoices, bank statements showing funds used for acquisition, contracts, receipts, gift deeds, inheritance documents, sale/purchase agreements, or corroborating third-party records) is critical. The Act's emphasis on "amount expended in acquiring" (as compared with mere "amount of such asset" in the Bill) particularly suggests retaining evidence of acquisition cost or expenditure.

Key Differences Between Bill (Old Version) and Enacted Section, and Practical Impact

  • Wording on measurement of asset: Bill-"amount of such asset"; Act-"amount expended in acquiring such asset."
    • Practical impact: The Bill language could be read to permit use of an asset's present or market value as the point of comparison with books; the Act restricts or narrows the comparison to the expenditure made to acquire the asset. This change tends to focus the assessment on actual outlay by the assessee rather than an external valuation; practically, it may limit instances where market appreciation (unrelated to acquisition cost) would be treated as unexplained income under this section. However, because the Act does not define "amount expended in acquiring" or provide valuation rules, uncertainties remain about treatment of improvements, acquisition via instalments, transfers between related parties, barter, or where acquisition cost cannot be substantiated.
  • Removal of phrase relating to "where the asset is found recorded": The Bill included the qualifier "where the asset is found recorded" in relation to the books; the Act omits this phrase and instead inserts "for any source of income" after reference to books.
    • Practical impact: The Act's phrasing arguably broadens the provision's reach by making explicit that books maintained for any source of income are relevant; the omission of "where the asset is found recorded" reduces textual ambiguity about applicability when an asset is recorded in some part of the books but not others. This may strengthen the Assessing Officer's ability to compare acquisition expenditure against books across sources.
  • Terminology and drafting clarity: The Act's revision appears to tighten the measure by referencing acquisition expenditure and by clarifying the scope of applicable books.
    • Practical impact: While the Act may be intended to bring more precision, because neither text supplies valuation mechanics or burdens (who proves what), practical disputes over valuation, timing, and satisfactory explanation are likely to arise and be resolved through assessment proceedings or appellate adjudication.

Interpretive and Procedural Gaps (as per documents)

  • The document does not state valuation methodology for "value" or "amount expended in acquiring", nor does it provide rules for assets acquired by non-monetary means (gifts, inheritance, swaps) - Not stated in the document.
  • The document does not state the burden of proof, standard for "satisfactory" explanation, or requirements for notice and hearing before deeming income - Not stated in the document.
  • The document does not state how virtual digital assets are to be valued or evidenced - Not stated in the document.

Action Points (derived from the text)

  • Taxpayers should retain documentary evidence of acquisition expenditure (invoices, payment records, bank transfers, loan documents) for any asset likely to be scrutinised, including VDAs.
  • Where an asset is recorded in books, ensure acquisition entries accurately reflect amounts expended and maintain supporting schedules linking books to physical assets.
  • Advisers should prepare documentary narratives to explain source and nature of acquisition in the event of an assessment query, and to challenge any valuation that rests on market price rather than acquisition expenditure if the Act's wording is invoked.
  • Because the Assessing Officer's satisfaction is dispositive in the provision, ensure procedural safeguards (e.g., requests for reasons, reliance on contemporaneous records) are used during assessment and appeals - procedural specifics are Not stated in the document.

Key Takeaways

  • Both texts permit deeming an unexplained asset (or excess over recorded amount) to be assessable income if no satisfactory explanation is provided.
  • The Act alters the metric from "amount of such asset" (Bill) to "amount expended in acquiring such asset", shifting focus to acquisition expenditure.
  • The Act clarifies that books maintained "for any source of income" are relevant; other drafting changes remove certain qualifiers present in the Bill.
  • Virtual digital assets are specifically within the scope of the definition of "asset" in both texts.
  • Significant interpretive and procedural details (valuation method, burden of proof, standards for "satisfactory" explanation) are not provided in the documents and will be decisive in future assessments and disputes.

Full Text:

Section 104 Unexplained asset.

Topics

Acts Income Tax