Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Case Laws Income Tax
    Retirement Leave Encashment Exemption under Section 10(10AA)(ii) and Retrospective Application of No...
    Transit-State Jurisdiction under GST: Limits on Detention and Penalty in External Inter-State Suppli...
    Post-Facto Shareholder Ratification of Diversion of Preferential Issue Proceeds under the PFUTP Regu...
    Case Laws Income Tax
    Section 195 Withholding on Payments to Non-Residents: Royalty, Fees for Technical Services and Busin...
    Penalty: Scope of "Any Person" under Section 122(1A) of the Central Goods and Services Tax Act, 2017
    Recovery of Corporate Debtor Premises and Proof of Tenancy, Lease or Licence Rights under the Insolv...
    Service of GST Notices through the Common Portal: Statutory Validity and Practical Accessibility
    Case Laws Income Tax
    TNMM Comparability: Operating Items, Search Matrix and Functional Analysis under Rule 10B
    Case Laws Customs
    Validity of Gold Seizure under Section 110 and the Conditional Reverse Burden under Section 123 of t...
    Case Laws Income Tax
    Deduction under Section 80GGC: Genuineness of Political Contributions and Evidentiary Burden
    Post-Death Determination of GST Liability and Estate-Limited Recovery from Legal Heirs
    Non-Confirmation of Seizure under Section 37A of FEMA and the Requirement of Recorded Reasons to Bel...
    Case Laws Companies Law
    Oppression and Mismanagement Proceedings under Sections 241 and 242: Corporate Authority During Pend...
    Case Laws Benami Property
    Benami Claims in Self-Acquired Property: Rejection of Plaint and the Limits of the Fiduciary-Capacit...
    Case Laws Income Tax
    Reopening of Assessment under Sections 147 and 148: Reason to Believe, Tangible Material and Change ...
    Case Laws Income Tax
    Penalty under Section 270A on Disallowance of Political Donation Deduction under Section 80GGC
    Case Laws Income Tax
    Conditional Registration under Section 12AB and the Limits of Commissioner's Statutory Powers
    Case Laws Customs
    Transaction Value, Rule 12 and Enhancement Based on Consent Letters in Customs Valuation: Limits of ...
    GST on Assignment of Leasehold Rights: Distinguishing Transfer of Immovable Property from Supply of ...
    Case Laws Income Tax
    Leave Encashment Exemption for Non-Government Employees under Section 10(10AA)(ii) and the Enhanced ...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws Income Tax
Show AI Summary
Retirement leave encashment exemption applies under the enhanced notified ceiling while preserving non-government employee classification and statutory conditions.
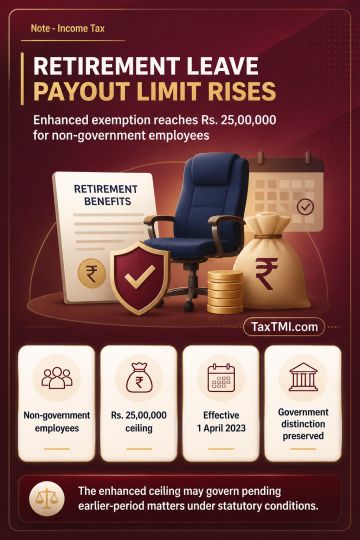
Section 10(10AA)(ii) governs retirement leave-encashment exemption for non-Government employees, subject to the ten-month earned-leave measure, average-salary computation, and the notified monetary ceiling. Notification No. 31/2023 specifies an enhanced ceiling of Rs. 25,00,000, is deemed effective from 1 April 2023, and certifies that retrospective effect causes no adverse effect. The enhanced ceiling is treated as a remedial rationalisation of an existing exemption and may govern pending earlier-period matters, while preserving the distinction between Government and non-Government employees.
Case Laws GST
Show AI Summary
Transit GST jurisdiction limits detention penalties for documented inter-State supplies lacking a local taxable nexus.
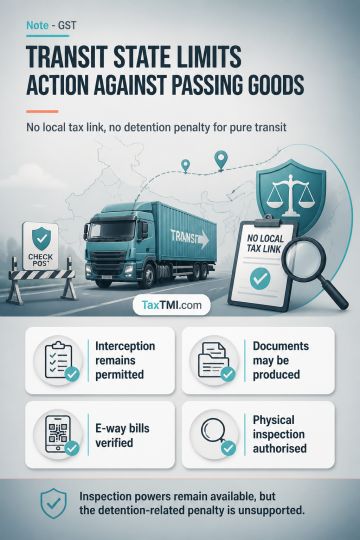
Transit-State jurisdiction under GST permits interception, document production, e-way bill verification and authorised physical inspection of goods moving through an intermediate State. It does not, in a pure transit movement, support detention-related penalty for an external inter-State supply where origin and destination lie outside the intercepting State, no tax is payable there, and there is no evidence of diversion, local supply, fictitious or mismatched documents, or mismatch of goods. Cross-empowerment is administrative and does not create an independent territorial taxable nexus.
Case Laws SEBI
Show AI Summary
Shareholder ratification cannot cure preferential-issue fund diversion when disclosed objectives are abandoned, triggering securities-market fraud and disclosure concerns.
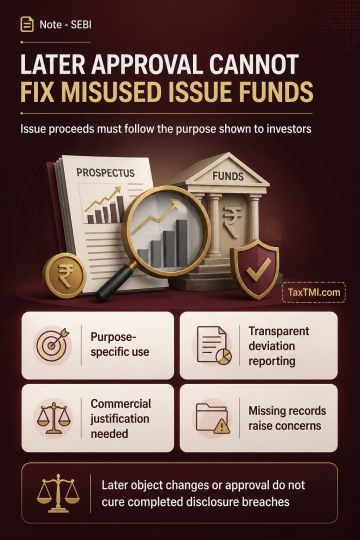
Post-facto shareholder approval cannot retrospectively validate diversion of preferential-issue proceeds contrary to issue-specific objects disclosed to shareholders and the market. A special resolution authorises the issue but does not permit unrestricted use of proceeds. Periodic deviation reporting, audit-committee review and utilisation disclosures promote transparency; they do not enable diversion followed by later regularisation. Immediate diversion, inadequate commercial justification and missing documentation may indicate that disclosed objects were not genuinely intended to be performed. Later amendment of corporate objects or shareholder ratification cannot cure a completed securities-market disclosure breach.
Case Laws Income Tax
Show AI Summary
Cross-border software payments require copyright-right, technical-service, and permanent-establishment analysis before withholding obligations are determined under applicable treaties.
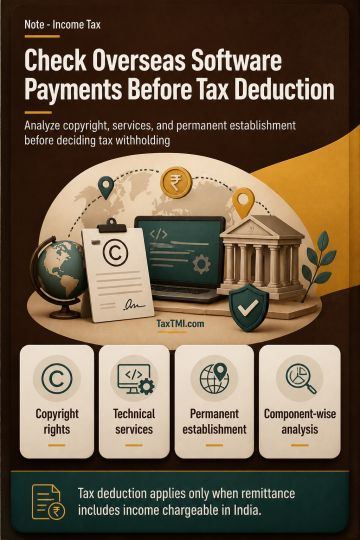
Section 195 requires withholding only from a remittance to a non-resident that includes income chargeable in India. For software, royalty depends on transfer of copyright rights, not merely the right to install, access, use, or distribute a copyrighted article under restrictive terms. Where a DTAA is more beneficial, its royalty and FTS definitions control; treaty FTS may require technology to be made available. Amounts that are neither royalty nor FTS require consideration as business profits, ordinarily taxable only where profits are attributable to a permanent establishment. Composite payments require component-wise allocation and analysis.
Case Laws GST
Show AI Summary
Personal GST penalty requires proof that the beneficiary retained benefit and directed a covered invoice or credit transaction.
Section 122(1A) may impose personal GST penalty on a registered or unregistered person only for a covered invoice or input tax credit transaction. Liability requires cumulative proof that the individual retained an identifiable personal benefit and that the transaction was conducted at that person's instance. Directorship, employment, registration, signature authority, or association with the taxable entity neither independently establishes nor excludes liability. Proceedings require transaction-specific and person-specific allegations and findings. The provision operates prospectively for underlying acts or transactions occurring on or after 01.01.2021.
Case Laws IBC
Show AI Summary
Proof of tenancy rights governs insolvency recovery of corporate-debtor premises from occupants lacking enforceable possessory interests.
Where premises form part of the corporate debtor's assets, Sections 18 and 25 of the Insolvency and Bankruptcy Code, 2016 require the resolution professional to take custody, control, preservation and protection measures. An occupant resisting recovery must prove a subsisting tenancy, leasehold interest or enforceable licence through reliable evidence of the parties' intended relationship and its essential terms. Permission to stock goods or conduct limited business activity, prolonged occupation, and business or utility records do not independently create rights in the premises. Section 60(5)(c) supports insolvency jurisdiction over asset-recovery measures connected with the insolvency estate.
Case Laws GST
Show AI Summary
GST portal service requires statutory validity and practical accessibility before ex parte adjudication can fairly proceed.
GST portal service is a statutory method under Section 169, but its use in an ex parte demand proceeding depends on effective accessibility and a meaningful opportunity to reply and be heard. Rule 142 requires electronic DRC-01 and DRC-07 summaries to operate alongside the underlying show-cause notice and reasoned order. Portal placement, complete communication, e-mail transmission, technical reliability and proof of actual access may determine whether service is effective, whether waiver applies, and whether appellate limitation begins.
Case Laws Income Tax
Show AI Summary
TNMM comparability requires consistent operating-cost treatment and FAR-based selection, while search matrices cannot replace evidence-led functional analysis.
TNMM requires consistent computation of operating profit and operating cost for the tested party and comparables. A provision for doubtful debts connected with sales and trade receivables may be an operating expense, as may routine business levies; income-tax on profits remains excluded. A search matrix is a disciplined evidentiary tool, not a statutory bar to an out-of-matrix comparable. Inclusion requires proof of functional fit, filter satisfaction and reasons for its absence, while rejection cannot rest solely on matrix absence. FAR analysis, segmental reliability and material scale differences govern comparability.
Case Laws Customs
Show AI Summary
Reasonable belief in gold seizure requires recorded objective grounds before the reverse burden for smuggling can arise.
Gold seizure under Section 110 requires the proper officer to hold, before seizure, objectively supportable reasons to believe that goods are liable to confiscation. For gold, Section 123 shifts the burden of disproving smuggling only after a lawful seizure made in reasonable belief that the gold is smuggled. A general panchnama recital, foreign markings, high purity, or an uncorroborated retracted statement cannot alone establish that foundation. Reasons must exist contemporaneously and cannot be supplied retrospectively through later investigation.
Case Laws Income Tax
Show AI Summary
Political contribution deductions require proof that payments are genuine, not merely bank transfers, receipts, and recipient registration.
Registration of the recipient political party, non-cash remittance, banking records and donation receipts are necessary evidentiary facts for a political-contribution deduction, but do not conclusively prove a genuine contribution. Where credible material indicates an accommodation-entry arrangement involving return of funds through intermediaries, the claimant must substantiate the transaction and address taxpayer-specific circumstances. General allegations about a recipient cannot alone displace a claim without a sufficient nexus to the taxpayer's own payment. Penalty initiation requires separate determination of under-reporting or misreporting and a reasonable opportunity of hearing.
Case Laws GST
Show AI Summary
Estate-limited GST recovery permits post-death assessment of legal representatives while protecting heirs' independent assets after business discontinuance.
Section 93 permits post-death GST determination against a legal representative where a liable person dies. If the business is discontinued, tax, interest and penalty may be recovered only from the deceased's inherited estate and only within its capacity; the heir's independent assets remain outside that limit. Proceedings may be initiated without a pre-death notice, but must be addressed to the legal representative in that capacity, follow the applicable adjudication process, and provide hearing and a reasoned order.
Case Laws FEMA
Show AI Summary
Recorded reasons to believe govern foreign-asset seizure; non-confirmation requires appellate resolution before contradictory adjudication proceeds.
Section 37A permits seizure of equivalent domestic assets only where the authorised officer records written reasons to believe that foreign assets are held in contravention of FEMA. The competent authority must examine the material after hearing both sides and either confirm or set aside seizure. A reasoned non-confirmation based on an absent statutory threshold is substantive on seizure, though it does not finally decide the underlying contravention. Pending appeal, the adjudicating authority cannot displace that finding or adopt a contrary premise; Section 37A(4) applies only to confirmed seizure.
Case Laws Companies Law
Show AI Summary
Unstayed tribunal dismissal leaves former directors without corporate authority while banks follow valid company instructions amid management disputes.
Where an oppression and mismanagement petition has been dismissed, a pending appeal without an appellate stay does not itself restore a former director's authority or suspend the dismissal's operative effect. Sections 241 and 242 require statutory prejudice and prescribed Tribunal findings; procedural irregularities in director removal may be relevant but do not alone establish oppression. Banks should ordinarily follow formally authorised company instructions rather than decide unresolved management disputes, unless a binding judicial or statutory restraint applies.
Case Laws Benami Property
Show AI Summary
Benami property claims cannot be recast through wills or employment-based trust when pleadings assert beneficial ownership.
Benami-property claims based on a claimant's payment for property titled in another person's name may fall within the statutory definition when the property is alleged to be held for that claimant's benefit. A Will, succession claim, or other later instrument does not provide an independent basis of title where the pleaded foundation is restoration of beneficial ownership. The statutory scheme prohibits benami arrangements, bars enforcement of claimed beneficial ownership, and treats prohibited re-transfers as invalid; self-acquired title in the named holder's name does not displace the pleaded funding arrangement.
Case Laws Income Tax
Show AI Summary
Reason to believe in reassessment requires tangible material, a live nexus, and recorded reasons; review of examined issues is barred.
Income-tax reassessment under Sections 147 and 148 is permissible only where recorded reasons, assessed at the time of notice, disclose a bona fide reason to believe that chargeable income escaped assessment. Final proof is unnecessary at that stage, but relevant tangible material must have a rational, live link to escapement. Reopening cannot be used to review an issue consciously examined and decided in the original scrutiny; nor can later or extraneous material supplement the recorded reasons. The taxpayer may seek the reasons, file focused objections, and receive a speaking order before reassessment continues.
Case Laws Income Tax
Show AI Summary
Political-donation deduction disallowance does not itself establish misreporting; enhanced penalty requires proof of a specific statutory default.
Disallowance of a political-contribution deduction under Section 80GGC and imposition of penalty under Section 270A are separate statutory inquiries. An adverse finding on genuineness or eligibility may raise assessed or reassessed income, but cannot alone establish misreporting. Enhanced penalty requires proof that the taxpayer's conduct falls within a specific Section 270A(9) category, supported by a precise notice and reasoned factual findings.
Case Laws Income Tax
Show AI Summary
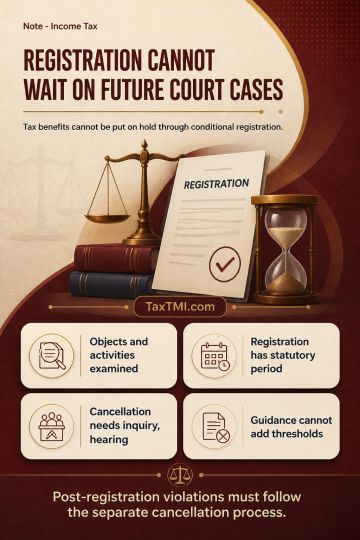
Conditional charitable registration cannot suspend tax benefits pending litigation outside the statutory grant and cancellation framework.
Section 12AB permits the authority, after inquiry into objects, genuine activities and material legal compliance, to grant registration for the statutory period or reject the application. It does not create a contingent form of registration whose tax consequences await future litigation. Post-registration violations must be addressed through the separate cancellation process, requiring inquiry and hearing. Conditions in prescribed forms or administrative guidance may operationalise statutory duties but cannot create extra-statutory eligibility thresholds, future-conduct obligations or anticipatory cancellation consequences. Binding jurisdictional rulings remain applicable unless stayed, modified or reversed.
Case Laws Customs
Show AI Summary
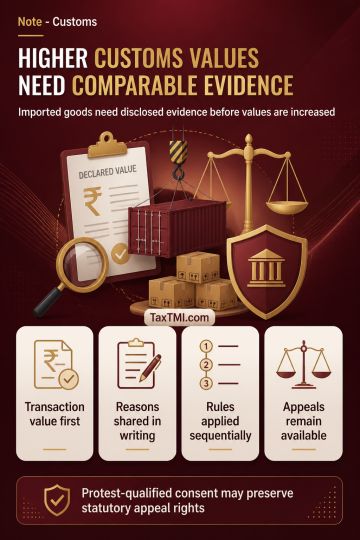
Transaction value reassessment requires disclosed comparable evidence, while protest-qualified consent preserves appellate rights against enhanced customs valuation.
Transaction value under Section 14 and Rule 3 is the primary basis for valuing imported goods. Rule 12 permits rejection only where an objectively sustainable reasonable doubt persists after considering further information; on request, the grounds must be disclosed in writing and a hearing afforded. Redetermination must follow Rules 4 to 9 sequentially and rely on demonstrably comparable import data. Written acceptance of reassessment may dispense with a speaking order under Section 17(5), but protest-qualified or provisional-clearance correspondence may preserve the statutory right to appeal.
Case Laws GST
Show AI Summary
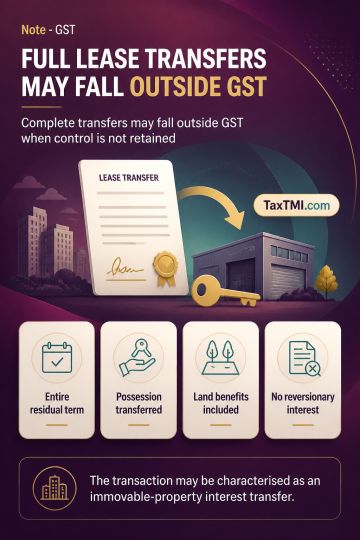
Leasehold rights assignment may fall outside GST when the lessee permanently transfers the entire proprietary estate.
GST treatment of assignment of leasehold rights turns on whether the lessee has made a complete transfer of its existing estate or continues to provide occupation or enjoyment. Where the assignor transfers the whole residual term, possession, building and associated rights, retains no reversionary or controlling interest, and the assignee succeeds directly to obligations towards the original lessor, the transaction may be characterised as transfer of benefits arising out of land rather than a supply of services. Labels such as premium, salami or transfer fee are not conclusive.
Case Laws Income Tax
Show AI Summary
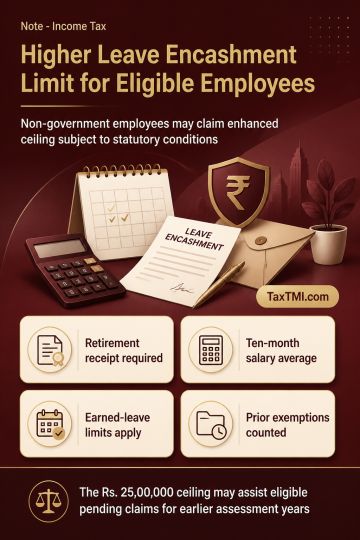
Leave encashment exemption: Non-government employees may claim the enhanced notified ceiling subject to statutory computation conditions.
Retirement leave encashment received by employees other than Central or State Government employees falls under Section 10(10AA)(ii). Exemption depends on retirement, the ten-month earned-leave limit, average salary for the preceding ten months, earned-leave entitlement restrictions, aggregate limits, and prior exempt receipts. The enhanced notified ceiling of Rs. 25,00,000, deemed to operate from 1 April 2023, is treated in the Tribunal approach discussed as a beneficial rationalisation available to eligible pending claims for earlier assessment years, without displacing the statutory computation conditions.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Back

All TMI Notes

Jurisdiction and Procedure for Tax Recovery : Clause 414 of the Income Tax Bill, 2025 Vs. Section 223 of the Income-tax Act, 1961

1 July, 2025

Contents
Acts
Rules & Regulations
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Clause 414 Tax Recovery Officer by whom recovery is to be effected.

Income Tax Bill, 2025

Introduction

The process of tax recovery is a critical aspect of revenue administration, ensuring that tax dues assessed and demanded are effectively realized by the authorities. Clause 414 of the Income Tax Bill, 2025, which deals with the "Tax Recovery Officer by whom recovery is to be effected", represents a core procedural provision for the enforcement of tax recovery. This clause determines the jurisdiction and powers of the Tax Recovery Officer (TRO) in cases where recovery of tax arrears is necessary, especially when the assessee has multiple connections to different jurisdictions or possesses assets spread across various locations. The provision is substantially similar to Section 223 of the Income-tax Act, 1961, and is operationalized in practice through Rule 117B of the Income-tax Rules, 1962, which prescribes the form and manner in which statements (certificates) for recovery are to be drawn up.

This commentary provides a detailed examination of Clause 414, analyzing its structure, legislative intent, and practical implications. A comparative analysis is undertaken with Section 223 of the Income-tax Act, 1961, highlighting similarities, changes, and their potential effects. The interaction with Rule 117B of the Income-tax Rules, 1962, is also explored, considering procedural aspects and compliance requirements. The analysis is structured to provide a comprehensive understanding for practitioners, policymakers, and taxpayers alike.

Objective and Purpose

The primary objective of Clause 414 is to provide a clear and efficient legal framework for the identification of the appropriate Tax Recovery Officer empowered to take action for recovery of tax dues under the Income Tax Bill, 2025. The provision is designed to address scenarios where the assessee's business activities, residence, or assets are located in multiple jurisdictions, thus requiring a coordinated approach to recovery.

The legislative intent is rooted in ensuring that the process of tax recovery is not hampered by jurisdictional ambiguities. By specifying the TRO's jurisdiction and providing for inter-jurisdictional cooperation, the provision seeks to expedite recovery, minimize administrative delays, and prevent evasion of tax dues through dispersal of assets.

The historical background of this provision can be traced to the need for robust enforcement mechanisms in tax statutes, particularly in the wake of increased mobility of assets and the complexity of business operations. The provision also reflects policy considerations of administrative efficiency, fairness to taxpayers, and accountability of the tax administration.

Detailed Analysis of Clause 414 of the Income Tax Bill, 2025

1. Sub-section (1): Determination of Jurisdiction

Clause 414(1) lays down the primary rule for determining which Tax Recovery Officer is competent to effect recovery u/s 413 (presumably the provision dealing with the issuance of recovery certificates or similar instruments under the new Bill).

  • Clause 414(1)(a): The TRO within whose jurisdiction the assessee carries on business or profession, or has the principal place of business or profession.
  • Clause 414(1)(b): The TRO within whose jurisdiction the assessee resides or any of his movable or immovable property is situated.

The provision further clarifies that the "jurisdiction for this purpose" is to be determined as per the orders or directions issued by the Board (Central Board of Direct Taxes), or by any income-tax authority not below the rank of Commissioner, who is authorized by the Board pursuant to Section 241.

Key Features and Interpretation:

  • The provision ensures that the TRO's jurisdiction is not arbitrary but is assigned according to formal orders, enhancing predictability and legal certainty.
  • The dual criteria-business/profession location and residence/property location-reflect the realities of modern taxpayers, whose business and personal assets may be geographically dispersed.
  • The reference to orders or directions of the Board or authorized Commissioner provides flexibility to adapt jurisdictional assignments as per administrative needs.

2. Sub-section (2): Multi-jurisdictional Recovery and Transfer of Certificate

Clause 414(2) addresses the situation where an assessee has property in more than one TRO's jurisdiction. It provides two triggers for inter-jurisdictional cooperation:

  • (a) Inability to recover the entire amount by sale of property within the original TRO's jurisdiction;
  • (b) Opinion that such transfer is necessary for expediting or securing recovery.

In such cases, the original TRO may send the certificate (or a certified copy specifying the amount to be recovered) to another TRO as specified in sub-section (1)(b). The receiving TRO is then empowered to recover the amount as if the certificate had been drawn up by him.

Key Features and Interpretation:

  • The provision is designed to ensure that the recovery process is not stymied by jurisdictional limitations, especially for high-value or complex cases involving multiple assets.
  • The transfer mechanism is triggered both by actual inability to recover (objective criteria) and by the opinion of expediency (subjective criteria), providing necessary discretion to the TRO.
  • The requirement of certification (in the prescribed manner) for partial recovery ensures procedural integrity and prevents duplication or over-recovery.
  • The provision maintains the chain of authority and accountability, as the receiving TRO acts under the same legal mandate as the original TRO.

3. Prescribed Certification and Form (Interaction with Rule 117B)

While Clause 414 does not itself prescribe the form or manner of certification, it references the need for certification "as prescribed". This is where Rule 117B of the Income-tax Rules, 1962, becomes relevant. Rule 117B mandates that statements u/s 222 or 223 (and by extension, under Clause 414) must be drawn up in Form No. 57.

Key Features:

  • The use of a standardized form ensures uniformity, completeness, and legal sufficiency of recovery certificates.
  • The form likely contains details such as the amount to be recovered, identification of the assessee, particulars of assets, and certification by the TRO.
  • This procedural safeguard is essential to prevent errors, omissions, or disputes regarding the amount or identity of assets to be recovered.

Comparative Analysis with Section 223 of the Income-tax Act, 1961

Textual and Structural Similarities

A close reading reveals that Clause 414 of the Income Tax Bill, 2025, is largely modeled on Section 223 of the Income-tax Act, 1961. Both provisions:

  • Define the competent TRO as the one in whose jurisdiction the assessee carries on business, resides, or has property.
  • Provide for transfer of recovery certificates in cases involving multiple jurisdictions.
  • Reference the assignment of jurisdiction by the Board or authorized officers.
  • Require certification in the prescribed manner for partial recovery.

The language and structure are nearly identical, reflecting a deliberate legislative choice to maintain continuity in the recovery framework.

Key Differences and Developments

  • Reference to Authorizing Authority: Section 223 refers to the "Principal Chief Commissioner or Chief Commissioner or Principal Commissioner or Commissioner" authorized u/s 120, whereas Clause 414 refers to "any income-tax authority not below the rank of Commissioner who is authorized in this behalf by the Board in pursuance of section 241". This may reflect a streamlining or updating of administrative hierarchy under the new Bill.
  • Reference to Related Provisions: Section 223 is linked to action u/s 222 (certificate for recovery), while Clause 414 refers to Section 413. This is a result of renumbering or restructuring in the 2025 Bill, but the substantive mechanism remains unchanged.
  • Terminology and Modernization: The Bill uses slightly modernized language (e.g., "the Tax Recovery Officer by whom the certificate is drawn up" instead of "competent to take action"), but the practical effect is the same.

Interaction with Rule 117B of the Income-tax Rules, 1962

Rule 117B prescribes the form (Form No. 57) for statements u/s 222 or 223. Although the 2025 Bill may update the numbering of sections, unless new rules are notified, the existing procedural rule and form would continue to apply mutatis mutandis.

  • Procedural Consistency: The continued use of Form No. 57 ensures that the administrative process for drawing up and transmitting recovery certificates remains consistent across legislative transitions.
  • Legal Sufficiency: Failure to use the prescribed form could render recovery proceedings vulnerable to challenge on grounds of procedural irregularity.
  • Potential for Update: The new Bill may necessitate updates to the Rules to align references and ensure clarity, but the substantive requirement for certification and formality is likely to be retained.

Ambiguities and Issues in Interpretation

  • Subjective Discretion: The provision empowers the TRO to form an "opinion" regarding the necessity of inter-jurisdictional transfer. While this is necessary for administrative flexibility, it could be subject to judicial scrutiny in cases of alleged arbitrariness or mala fide.
  • Jurisdictional Overlaps: In complex cases involving multiple businesses or widespread assets, there may be disputes regarding the appropriate TRO, especially where assets are transferred or relocated during the pendency of proceedings.
  • Procedural Lapses: Non-compliance with certification or form requirements could lead to legal challenges, potentially delaying recovery.

Practical Implications

1. For Tax Authorities

  • Administrative Efficiency: The provision allows for seamless transfer and coordination between TROs, reducing bottlenecks in recovery.
  • Discretion and Accountability: TROs are empowered with discretion to determine when inter-jurisdictional cooperation is necessary, but are bound by formal procedures and documentation.
  • Jurisdictional Clarity: The clear delineation of jurisdiction prevents overlapping actions and potential legal challenges from assessees based on procedural grounds.

2. For Taxpayers

  • Legal Certainty: Taxpayers are informed in advance about which TROs may take action, reducing the risk of arbitrary or multiple recovery proceedings.
  • Procedural Safeguards: The requirement of prescribed certification and formal transfer minimizes the risk of double recovery or procedural unfairness.
  • Potential for Multi-jurisdictional Proceedings: Taxpayers with assets in multiple locations may face recovery actions from more than one TRO, but within a structured and regulated process.

3. For Legal and Tax Advisors

  • Advisory Role: Advisors must analyze the location of clients' assets and business operations to anticipate possible jurisdictions for recovery actions.
  • Dispute Resolution: In case of disputes regarding jurisdiction or procedural compliance, advisors must scrutinize the adherence to prescribed procedures and forms.

Conclusion

Clause 414 of the Income Tax Bill, 2025, represents a continuation and refinement of the established legal framework for tax recovery in India. By clearly defining the jurisdiction of Tax Recovery Officers and providing a structured mechanism for inter-jurisdictional cooperation, the provision balances administrative efficiency with procedural safeguards for taxpayers. The close alignment with Section 223 of the Income-tax Act, 1961, ensures continuity and predictability, while minor updates reflect administrative modernization.

The interaction with Rule 117B and the prescribed forms underscores the importance of procedural compliance in enforcement actions. While the provision grants necessary discretion to tax authorities, it also embeds safeguards against abuse or error. As business structures and asset holdings become more complex, the importance of such clear, robust recovery mechanisms will only increase. Future reforms may focus on further clarifying administrative hierarchies, updating procedural rules, and leveraging technology for more efficient inter-jurisdictional cooperation in tax recovery.


Full Text:

Clause 414 Tax Recovery Officer by whom recovery is to be effected.

Topics

Acts Income Tax