 TaxTMI
Login
 TaxTMI

Login
Loading...
Press 'Enter' to add multiple search terms. Rules for Better Search
 of 3381

Press 'Enter' after typing page number.
of 3381 Press 'Enter' after typing page number.


No Folders have been created
Are you sure you want to delete "My most important" ?
NOTE:
of 3381 Press 'Enter' after typing page number.
of 3381 Press 'Enter' after typing page number.

All News
of 3381 Press 'Enter' after typing page number.
All News

Note

Bookmark

Share


It is a pleasure for me to be here at NCAER to speak on India’s current monetary policy framework. My remarks focus on how the existing framework has evolved over the past decade, where it stands today, and the issues that may shape its next iteration in five years from now.
2. As you know, the Government of India issued a Gazette notification on March 25, 2026, renewing the existing inflation target of 4 per cent with ±2 per cent tolerance band for five more years, extending the current inflation target (IT) mandate through March 2031. This renewal, wherein all the features of the framework were retained, invites reflection, not merely on continuity, but also on what a decade of experience has taught us and what refinements, if any, may be warranted in the future.
3. My remarks are organised as follows. I begin with a brief account of the framework’s architecture and a decade of monetary policy decisions and outcomes. I then turn to the public consultation process followed in the latest review, focusing on the four questions that structured it, presenting for each the national and international evidence, and the feedback received. Finally, I will touch on a few issues that may warrant consideration when the framework comes up for its next review in 2031.
1. Framework’s architecture and a decade of monetary policy decisions and outcomes
4. India’s monetary policy framework has evolved continuously during the past decades, responding to domestic macroeconomic realities as well as advances in global best practices.2 The impetus for a more fundamental rethink started to emerge around early 2010s in the context of high inflation that exceeded India’s own historical averages and other peer economies, highlighting the need for a strong and explicit nominal anchor for monetary policy.3 By this time, many countries had successfully implemented inflation targeting and their impacts were broadly assessed to be favourable. India, too, came to regard IT as the appropriate framework to adopt.4
5. Inflation targeting was formally institutionalised with the amendment of the Reserve Bank of India (RBI) Act, 1934 in May 2016. RBI was entrusted with the responsibility of conducting monetary policy in India with the primary objective “to maintain price stability while keeping in mind the objective of growth”.
6. Section 45ZA of the RBI Act, 1934 mandates that “The Central Government shall, in consultation with the Bank, determine the inflation target in terms of the Consumer Price Index, once in every five years”. The government initially notified the inflation target of 4 per cent with a tolerance band of +/- 2 per cent for the period 2016 to 2021. Following the review in March 2021, the target was retained for the subsequent five-year period from 2021 to 2026. In the second statutory review, through the Gazette notification dated March 25, 2026, the framework has been renewed again, for a five-year period through March 2031.5
7. Responsibility of monetary policy decisions is vested with the Monetary Policy Committee (MPC), which was specifically given the task of deciding the policy repo rate required to achieve the inflation target. The decisions of the MPC were to be taken by a majority of votes, with Governor having the casting vote in case of a tie - a provision that, notably, has not needed to be invoked ever during the past decade.
8. Clear communication and transparency are recognised as defining features of an effective inflation-targeting regime. India’s IT framework reflects this emphasis: the RBI publishes the resolution adopted by the MPC following each meeting; releases the minutes of the individual members of the MPC on the 14th day thereafter; Governor’s statement and press briefings are used effectively as the modes of policy communication; and the RBI publishes Monetary Policy Report (MPR) once every six months, providing a medium-term macroeconomic assessment of domestic and global macroeconomic and financial conditions and an analysis of inflation dynamics and outlook.
9. Indian experience with IT is rather recent as inflation targeting has a history spanning more than three decades at the global level. First adopted by New Zealand in the early 1990s, it has since become the benchmark monetary policy framework across advanced economies (AEs) and emerging market and developing economies (EMDEs). Today, 48 countries, comprising of 14 AEs and 34 EMDEs, operate under inflation-targeting framework. India was among the later adopters when it formally institutionalised the framework in 2016. No inflation targeting country has ever abandoned it after adoption, although countries have periodically revised their frameworks in line with their evolving economic structures. These point towards both durability and flexibility of the IT framework.
10. International evidence broadly associates inflation targeting with three outcomes. First, countries under inflation targeting have experienced measurably lower and more stable inflation.6 Second, the credibility of monetary policy has improved, and inflation expectations have become better anchored to the stated target in such countries.7 Third, fiscal dominance have receded, and coordination between monetary and fiscal policies has strengthened.8
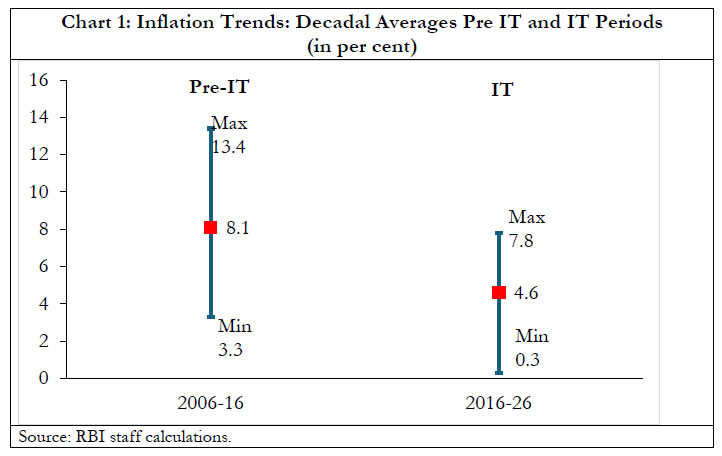
11. A broadly similar pattern has unfolded in India. Inflation has declined and stabilized. The average headline CPI inflation has declined from 8.1 per cent in the pre-IT decade (2006-16) to 4.6 per cent in the IT period (2016-26) - a decline of 3.5 percentage points. More importantly, the inflation variability has reduced as range of variation has lowered from 3.3-13.4 per cent in the pre-IT decade to 0.3-7.8 per cent during the IT period (Chart 1).9 Meanwhile, growth has been sustained and has become more stable.
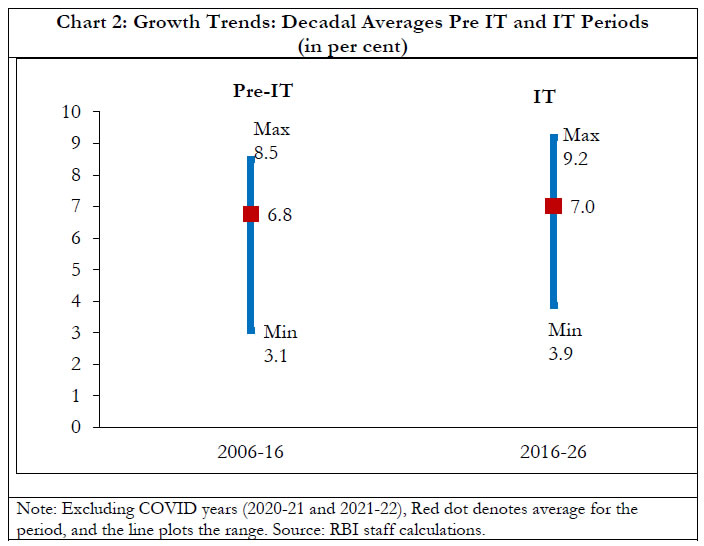
12. A concern sometimes raised about inflation targeting is that the single-minded pursuit of price stability may come at the cost of growth. India's experience does not bear this out. Average annual GDP growth actually edged up marginally from 6.8 per cent in the pre-IT decade to 7.0 per cent in the IT decade — excluding the COVID-affected years of 2020–21 and 2021–22 (Chart 2). Equally significant is the improvement in stability: the range of annual growth outcomes narrowed from 3.1–8.5 per cent pre-IT to 3.9–9.2 per cent post-IT, with the floor rising by nearly a full percentage point. Price stability and growth have thus proved complementary rather than conflicting objectives under the Indian framework.
13. India has achieved a stronger reduction in inflation relative to many other economies. Prior to the adoption of IT, India’s inflation was persistently above the world average and even the average of the EMDEs. During IT period, there has been a decisive reversal: India’s inflation has moderated to below that of EMDEs average and has converged towards the world average (Table 1). In 2025, India's headline inflation stood at 2.2 per cent, well below the EMDE average of 5.2 per cent and the world average of 4.1 per cent.
| Table 1: Average decadal Inflation in India, EMDEs and World | ||||
| 1996-2005 | 2006-15 | 2016-25 | 2025 | |
| India | 5.8 | 8.1 | 4.4 | 2.2 |
| EMDEs | 10.4 | 6.0 | 6.1 | 5.2 |
| World | 5.4 | 3.9 | 4.7 | 4.1 |
| Source: WEO database. | ||||
14. Inflation expectations have become more anchored since the inception of IT.10 This is a clear reflection of the fact that IT has helped countries not only navigate the persisting supply shocks, e.g., during the pandemic and the Ukraine war, without derailing expectations, but also ensured a faster convergence of inflation towards the target post these shocks. This happens to be the experience of India as well. Among other benefits, it is also seen to result in better coordination between monetary and fiscal policies; and more transparency and credibility of monetary policy.11
2. Five-year reviews of the IT Framework
15. In accordance with the provisions of the RBI Act, the first statutory review of the inflation target was conducted in March 2021. As a part of the process, the RBI published a report titled ‘Reviewing the Monetary Policy Framework’, which reviewed the practice and outcomes of IT during 2016–2021.12 Subsequent to this, the Government of India, via a Gazette notification dated March 31, 2021, retained the existing target for a further period of five years, up to March 2026.
16. The RBI adopted a different, more consultative approach in the second review. It published a Discussion Paper on August 21, 202513 surveying the practices, institutional designs, and emerging literature across economies with established IT frameworks; and presenting evidence in the Indian context. The paper sought comments and suggestions on the following four features that are central to the framework: (i) Whether headline CPI inflation or core inflation would better serve as the operative guide for monetary policy, given the evolving dynamics of food and core inflation and weight of food in the CPI basket? (ii) Whether the 4 per cent inflation target continues to remain optimal for the Indian economy, balancing the objectives of price stability and growth? (iii) Whether the tolerance band of ±2 per cent around the target warrants revision, through narrowing, widening, or elimination? and (iv) Whether the point target with a tolerance band inflation should be replaced by a range, so as to preserve operational flexibility without undermining the framework's credibility?
17. The discussion paper prompted wide-ranging discussions through seminars and coverage in the print and electronic media. The RBI received 75 direct responses on one or more of the four questions posed, though not every respondent responded to every question (Table 2).
Table 2: Responses to the four questions in the Discussion Paper
| Question | 1. Headline vs. Core | 2. Target to be 4% or something else | 3. Tolerance Band of +/- 2% or another one | 4. Point Target with tolerance band or a range |
| Number of Responses | 72 | 71 | 60 | 56 |
Source: Based on feedback obtained on the Review of Monetary Policy Framework Discussion Paper.
18. Let me now turn to each one of these questions.
Question 1: Headline or Core Inflation as the Policy Target?
19. The hypothetical case for retaining headline CPI rests on the following grounds. First, food and fuel inflation, which is included in headline but not in core, may not be considered a transient supply-side disturbance. For instance, persistently elevated food inflation can feed into core through second-round effects particularly via wage and cost indexation and could become entrenched. Second, the average citizen experiences and understands prices in totality, as in headline.14 Third, headline signifies institutional continuity, and a departure from it would need a reasonably high bar of justification.15
20. The case for core inflation, in turn rests on the following grounds. Food and fuel prices are inherently volatile and primarily driven by supply-side factors such as monsoon variability and global commodity cycles, on which monetary policy has limited traction.16 In India specifically, food carries a large weight in the CPI basket, which means that transitory supply shocks can produce sharp swings in headline inflation that may not warrant a monetary policy response.
21. In terms of the responses, over 90 per cent (66 out of 72) respondents, favoured retaining headline CPI inflation as the target (Chart 3).
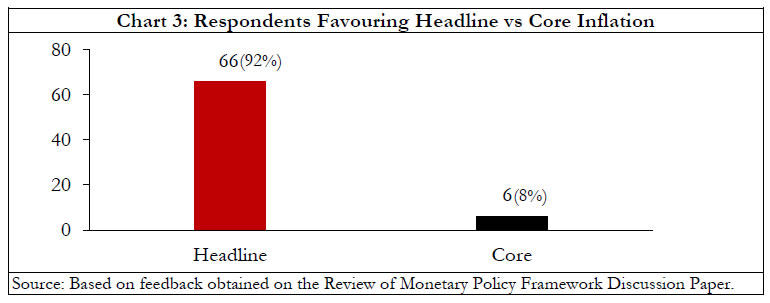
22. A disaggregated reading of the 66 respondents who favoured headline CPI reveals some nuance within the broad consensus (Table 3). While 41 of them supported headline as the sole and sufficient target, a significant minority of 25 felt that core inflation should play a complementary role-21 favoured headline as the formal target with core serving as an operational guide for policy deliberations; while 4 advocated for core to be accorded the status of an explicit additional target alongside headline.
Table 3: Views among Headline CPI Supporters
| Per cent of Total | |||
| Headline as Target | 41 | 63% | ||
| Headline as Target with Core as Operational Guide | 21 | 31% | ||
| Headline as Target with Core as Explicit Additional Target | 4 | 6% | ||
| Total | 66 | 100% |
Source: Based on feedback obtained on the Review of Monetary Policy Framework Discussion Paper.
23. Interestingly, international experience is quite definitive in the choice between headline and core. Of the 48 countries that currently operate under an inflation-targeting framework, 47 target headline inflation. Uganda stands as the sole exception in targeting core inflation. Notably, several countries that initially adopted core inflation as their target, including Thailand and Norway, subsequently transitioned to headline CPI (Table 4). The cross-country evidence thus reinforces the case for the headline.
24. Looking ahead, the structural distinction between the dynamics of headline and core inflation may be becoming less stark. Some evidence shows that Indian agriculture has become more resilient to rainfall shocks; and food prices volatility has moderated especially due to better management and narrowing of demand-supply gaps by the government. Besides, with the recent revision of the CPI basket by MoSPI, weight of food in overall CPI has declined, which means headline and core inflation are likely to track each other more closely going forward.
25. Thus, the suggestions received, the experience of the past ten years, and the international evidence all seem to favour retaining headline inflation as the target.
Question 2: Is the 4 per cent inflation target still optimal?
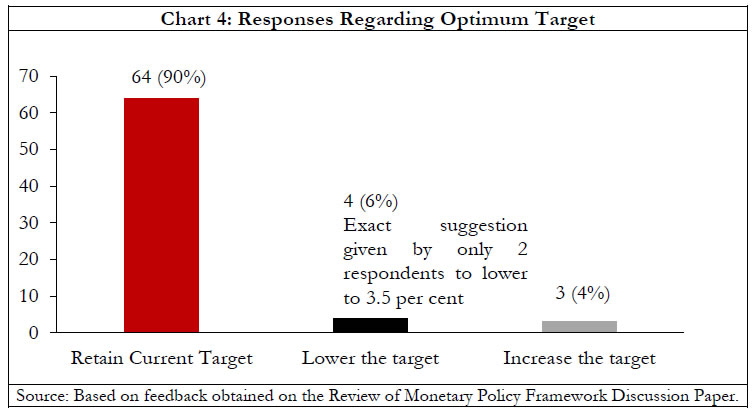
26. On the second question on the target rate of inflation, responses from public consultation indicated strong support for retaining the 4 per cent target (Chart 4).
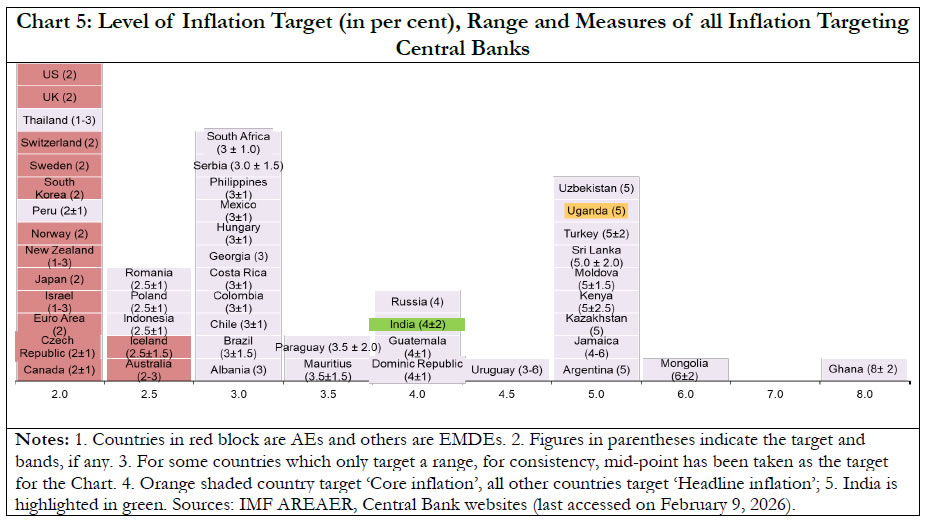
The case for retaining the 4 per cent target rests on several mutually reinforcing factors. First, 4 per cent target was as per the assessment of the RBI's Expert Committee in 2014. They established it as the rate at which macroeconomic conditions were deemed to be optimised with a zero-output gap. Subsequent re-estimations of trend inflation for India also reiterated this assessment.17 Second, current 4 per cent target is considered to be suitable to its stage of economic development when compared with other inflation-targeting economies. AEs, such as US, UK, Euro Area, Japan, Canada, and others, cluster around a 2 per cent target, reflecting the lower equilibrium inflation rates associated with their advanced and low-growth economies. EMDEs are placed at a higher range between 2.5 and 4 per cent (Chart 5). India's 4 per cent target places it at the upper end of the EMDEs.
27. Thus, the analytical arguments; suggestions received; and international experiences seem to favour 4 per cent target as optimal for India.
Question 3: Should the tolerance band be retained, narrowed, or redesigned?
28. Two-thirds of respondents favoured retaining the existing tolerance band of ±2 per cent (Chart 6). The remaining 21 respondents favoured a narrower band, on the grounds that tighter bounds would strengthen policy commitment, sharpen the signalling content of the target, and further anchor inflation expectations.
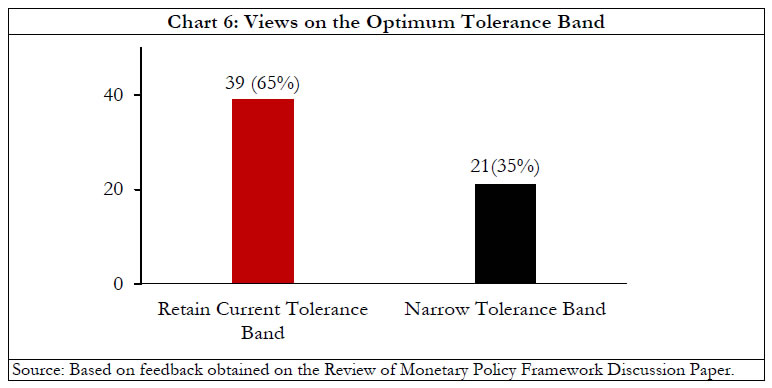
Among those who favoured narrowing the band, the proposals varied in specificity and design (Table 5). The most commonly recommended alternative was a symmetric band of ±1.5 per cent, favoured by 9 respondents. A further 4 respondents advocated for a tighter band of ±1 per cent, while 6 did not specify an exact width. A minority of 2 respondents proposed an asymmetric band, tolerance band being higher on the upper side and smaller on the lower side, say 3-6 per cent as the band around 4 per cent target which could allow greater accommodation of supply-side shocks on the upper side while maintaining a firmer floor.
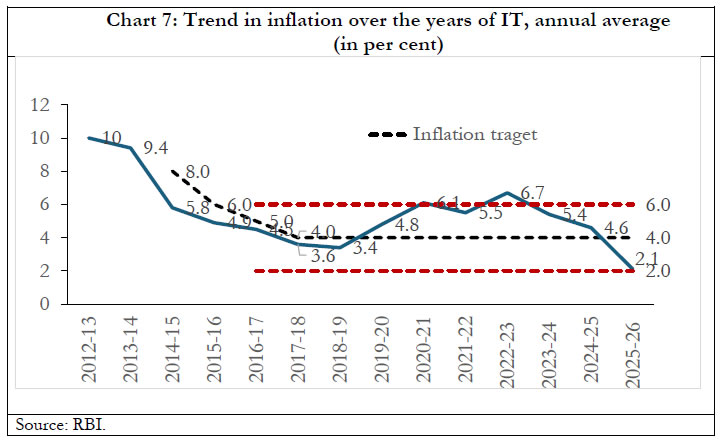
29. India's own IT experience has demonstrated the usefulness of the tolerance band. In the annual inflation data across the IT period, inflation exceeded the upper tolerance limit of 6 per cent in 2020-21 due to the COVID-19 pandemic and then again during the Russia-Ukraine war in 2022-23 (Chart 7). The lower tolerance band was not breached on an annual average basis although inflation remained below 2 per cent for a short period during 2025-26 due to very benign food price inflation.18
30. Internationally, advanced economies have generally moved to point targets, while tolerance bands are more prevalent and wider in emerging market and developing economies. Cross-country evidence suggests that target ranges or targets with bands are more successful in providing flexibility to address shocks while also maintaining credibility, aiding in inflation anchoring (Ehrmann, 2021). Most large emerging market economies have moved towards a 3 to 4 per cent target with a band of 1 to 1.5 per cent, leveraging their accumulated success with inflation targeting (Eichengreen and Gupta, 2024).
Taken together, the consultation responses and India's own IT experience converge on the same conclusion: the ±2 per cent tolerance band has served the framework well, providing the flexibility necessary to absorb large external shocks without sacrificing the credibility of the target itself.
Question 4: Point target with tolerance band, or pure range targeting?
31. The last question elicited fewest responses with only 56 respondents addressing it. While a pure range, instead of a point target with a tolerance band, could provide as much flexibility, the arguments against range targeting seem equally compelling. First, the midpoint of any range tends to be interpreted as the de-facto central target regardless of the central bank's stated intent. Second, under a point target, if MPC members differ in their preference for rate action, it can be straightly mapped to the differences in their assessment of the economy. Range targeting adds an additional layer of ambiguity as it could also be construed that the differences stem from their perception of the target itself. This may be true even for other stakeholders like markets and investors, thus, weakening the anchoring of expectations. Third, such a transition would defy the global trend and require a very compelling argument to be considered. Finally, in the absence of a compelling rationale, such a shift could be interpreted as a weakening of commitment and dent the hard-earned credibility of the existing framework.
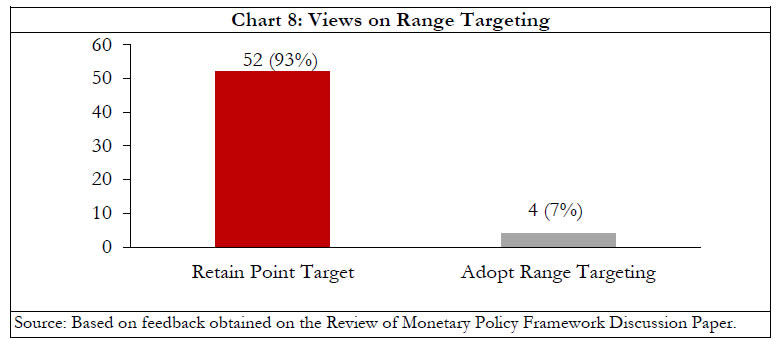
32. The public consultation reflected these considerations. Of the 56 respondents 52 favoured retaining the existing point target with a tolerance band. Only 4 respondents, supported moving to a pure range target (Chart 8).
33. Among inflation-targeting central banks, range targeting is not a popular choice. Countries such as the Czech Republic, New Zealand, South Korea and South Africa initially adopted range targets as transitional arrangements but subsequently moved to point targets with tolerance bands. Currently, only Australia, Israel and Thailand operate with a pure range, of 1 to 3 per cent, 1 to 3 per cent and 2 to 3 per cent respectively. The direction of travel among inflation targeters has been away from range targeting, not towards it.
3. Going forward
34. Renewal of India’s inflation targeting framework through March 2031, has come at a moment of considerable global uncertainty. Geopolitical tensions, supply chain disruptions, energy price volatility, and an uneven global growth outlook have made the macroeconomic environment more complex and less predictable. In this context, the decision to preserve the framework's core architecture including the headline CPI inflation target of 4 per cent and the ±2 per cent tolerance band is a policy choice of consequence. The review strengthens the framework precisely when it is most needed.
35. That said, the decision to continue with the existing framework is not to be construed as inertia towards change; the framework's durability over the past decade reflects a willingness to learn from experiences.
36. This begs the question of what might a future review look like? Would the same set of questions remain relevant in five years from now? Which new issues may surface at that time? Much would depend on the combination of inflation and growth outcomes as they evolve during the next five years; and the shocks, especially the global ones, that the economy may have to weather meanwhile. If growth-inflation mix evolves as it has in the past ten years: robust growth, and lower and more stable inflation, one could perhaps consider tweaking the level of inflation and the tolerance band a bit (keeping in view the international experiences, it would point towards a slightly lower inflation and a slightly narrower band). But if the global environment remains as challenging as it has been during the past six years, it would warrant both predictability and flexibility inherent in the existing framework.
37. On an ongoing basis, RBI too, on its part, can consider some further refinements, particularly with regard to more engagement on its core inflation measures. More, better, and timely communication has been a work in progress and will continue to remain so.
38. To conclude, the existing monetary policy framework has all the inherent features that can be duly leveraged to nudge the economy towards further improved macroeconomic outcomes. Calibrated refinements, backed by structural changes, if any, can continue to retain the relevance and appropriateness of the framework in the years ahead.
-------
1 Speech by Dr. Poonam Gupta, Deputy Governor, Reserve Bank of India delivered at Joint Seminar and Discussion - ‘India’s Inflation Targeting Framework’ and ‘Regional Economic Outlook for Asia and Pacific’, NCAER, New Delhi on May 5, 2026. Inputs from Sangita Misra, Somnath Sharma, and other colleagues are gratefully acknowledged.
2 India practiced a “multiple indicators approach” for a decade and a half prior to inflation targeting, when the objectives of monetary policy were stated to be price stability, growth, and financial stability. See Rakesh Mohan and Partha Ray (2018), “Indian Monetary Policy at the time of Inflation Targeting and Demonetisation” Brookings India, WP 4; Poonam Gupta (2016), ‘Capital Flows and Central Banking: The Indian Experience’ Policy Research Working Paper, World Bank, February. Das S (2020), ‘Seven Ages of India’s monetary policy’, RBI Bulletin, February; Dua P (2020), "Monetary policy framework in India," Indian Economic Review, Springer, vol. 55(1), pages 117-154, June.
3 Particularly in the post-Global Financial Crisis period when headline inflation hovered close to double digits for several years.
4 An Expert Committee was set up in September 2013 by the then Governor Dr Raghuram Rajan, under the chairmanship of Dr Urjit Patel, Deputy Governor, Monetary Policy. The Committee submitted its Report in January 2014. Against the backdrop of double-digit inflation, the Committee recommended a glide path of disinflation – reduction in inflation to 8 per cent by January 2015 and 6 per cent by January 2016. After various rounds of discussions between Government and Reserve Bank, the final agreement on adoption of IT framework was signed in February 2015.
5 Gazette Notification S.O.1580 (E) dated March 25, 2026.
6 Borio, C. E. (2024). Whither inflation targeting as a global monetary standard?. BIS Working Papers No 1230.
7 Ehrmann, M. (2021). Point targets, tolerance bands or target ranges? Inflation target types and the anchoring of inflation expectations. Journal of International Economics, 132, 103514.
8 Mishkin, F. S., and Kiley, M. (2025). The Evolution of Inflation Targeting from the 1990s to the 2020s: Developments and Challenges (No. w33585). National Bureau of Economic Research.
9 Based on the CPI (2012=100) series, average headline inflation declined from 7.4 per cent in April 2012 to August 2016 to 4.7 per cent in September 2016 to December 2025 in the post-IT period.
10 See Eichengreen, Gupta, and Choudhary (2021), Eichengreen and Gupta (2024), and RBI (2025).
11 Ben S. Bernanke, and Frederic S. Mishkin. (1997). Inflation targeting: A new framework for monetary policy? Journal of Economic Perspectives, 11(2), 97–116; Mishkin, F. S., & Kiley, M. (2025). The Evolution of Inflation Targeting from the 1990s to the 2020s: Developments and Challenges (No. w33585). National Bureau of Economic Research.
12 This report was published as an edition of the Report on Currency and Finance, 2020-21.
13 https://www.rbi.org.in/scripts/BS_PressReleaseDisplay.aspx?prid=61067
14 Das, S. (2024). at a forum at the Peterson Institute for International Economics in Washington D.C. on October 25, 2024.
15 RBI (2014). Report of the Expert Committee to Revise and Strengthen the Monetary Policy Framework (Chairman: Urjit R. Patel), January.
16 Data suggest that core inflation is not necessarily lower than headline inflation in India; though on average it is less volatile than headline inflation.
17 RBI Discussion Paper, August 2025, Annex 9.
18 The breach is more evident in the quarterly data. Out of the 38 quarters, inflation exceeded 6 per cent in 11 quarters and dropped below 2 per cent in 2 quarters.
