Loading...

βœ•
Top
Help
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedbackβœ•

Contact Us At :

E-mail: [email protected]

Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search βœ•
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
β•³
Add to...
You have not created any category. Kindly create one to bookmark this item!
βœ•
Create New Category
Hide
Title :
Description :
❮❮ Hide
Default View
Expand ❯❯
Close βœ•
🔎 News - Adv. Search
TEXT SEARCH:

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In:
Main Text + AI Text
  • Main Text
  • Main Text + AI Text
  • AI Text
Category: ?
Categorized by AI
---- All Categories ----
  • ---- All Categories ----
  • Income Tax
  • GST
  • Customs, DGFT & SEZ
  • FEMA & RBI
  • Corp. Laws, SEBI & IBC
  • PMLA, Black Money & ED
  • Budget
  • News and Press Release
  • PTI News
Month:
---- All Months ----
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ----
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

News
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
March 30, 2026
Show AI Summary
Rupee volatility and RBI forex exposure cap reshape market sentiment amid geopolitical tensions and dollar strength.
Rupee volatility in foreign exchange markets intensified amid geopolitical tensions, risk-off sentiment, elevated dollar demand and firmer crude prices, with the currency touching an intra-day low before settling lower against the US dollar. The Reserve Bank of India reduced the net open position that banks may maintain overnight and capped the Net Open Position (NOP-INR) for banks at USD 100 million, with compliance required by 10 April, as part of oversight of banks' foreign exchange exposure.
March 30, 2026
Show AI Summary
Quarterly reporting of non-resident client details through Form 092 requires online filing, declarations, and timely verification.
Quarterly reporting requirements apply to specified funds and stock brokers dealing with non-resident clients under Rule 157. Form 092 is the prescribed quarterly statement for furnishing non-resident client particulars, including name, contact details, country of residence, Tax Identification Number, and, where TIN is unavailable, the unique identification number issued by the foreign jurisdiction. The form must be filed online on the e-Filing portal within 15 days from the end of each quarter, and all non-resident clients dealt with during the quarter may be reported in the same return.
March 30, 2026
Show AI Summary
Public interest refusal to furnish information under income-tax law now uses electronic Form 91 with DIN authentication.
Form 91 is the statutory electronic form used by the designated Income-tax authority to refuse furnishing information requested under section 258(2)(a) of the Income-tax Act, 2025 where disclosure is not considered to be in the public interest. It is issued only by the competent authority, records the application reference, assessee details and relevant tax year, and states the refusal on public interest grounds. The form is authenticated through a system-generated DIN and electronic issuance details, creating a formal and traceable record distinct from forms used for furnishing information or intimation of non-availability.
March 30, 2026
Show AI Summary
Money laundering probe intensifies as Nepal widens scrutiny of former prime ministers and protests continue after arrests.
Protests continued in Nepal after the arrest of former Prime Minister K P Sharma Oli and former home minister Ramesh Lekhak in connection with the alleged suppression of the Gen Z protests, while the Department of Money Laundering Investigation and police intensified scrutiny of former prime ministers Sher Bahadur Deuba, K P Sharma Oli and Pushpa Kamal Dahal. The probe expanded after preliminary enquiries and the arrest of former minister Deepak Khadka in a money laundering case, with allegations of financial benefits for facilitating licences and contracts and forensic confirmation of burnt banknote fragments.
March 30, 2026
Show AI Summary
Public interest refusal for tax information requests through Form 091 by the designated Income-tax authority.
Form 091 is the prescribed income-tax form used by the designated Income-tax authority to refuse furnishing information sought under section 258(2)(a) of the Income-tax Act, 2025, where disclosure is not considered to be in the public interest. It is issued only after an information request is received and declined, applies separately for each tax year, and is authenticated by the authority's signature, name, and designation without requiring an official seal.
March 30, 2026
Show AI Summary
Insolvency code amendments tighten timelines, add creditor-initiated resolution, and curb frivolous delays in the process.
Insolvency and Bankruptcy Code amendments introduce stricter timelines, an out-of-court creditor-initiated resolution mechanism, and an enabling framework for group and cross-border insolvency. The revised framework replaces the underutilised fast-track route with a creditor-initiated insolvency process based on debtor-in-possession and creditor-in-control principles, subject to safeguards and defined timelines. The amendments also provide deterrent measures against abuse of process, including penalties for vexatious and frivolous proceedings, and seek to protect the integrity of the resolution system by discouraging delay-causing litigation.
March 30, 2026
Show AI Summary
Non-availability of information intimation under Form 90 is issued electronically after record verification and DIN authentication.
Form 90 is the electronic intimation issued by the designated Income-tax authority under section 258(2)(a) of the Income-tax Act, 2025, where requested information is unavailable in departmental records or no assessment has been made for the relevant tax year. It is generated after verification of records, authenticated through the Department's system with DIN, and includes the application reference, assessee name, and mandatory tax year. The form is event-based, has no fixed periodicity or due date, and standardises the term tax year for clear and traceable communication.
March 30, 2026
Show AI Summary
Non-availability of information intimation under income tax law through Form 090 communicates missing records, not rejection.
Form 090 is the prescribed intimation used by the designated Income-tax authority to communicate that information sought under section 258(2)(a) of the Income-tax Act, 2025 is not available in departmental records for the specified tax year. It is issued electronically after verification of records, is event-based, and must be furnished separately for each tax year. The form requires the exact tax year, recipient details, DIN and date, application reference, assessee name, and a statement confirming non-availability of information or that no assessment has been made.
March 30, 2026
Show AI Summary
Electronic information disclosure under the Income-tax Act, 2025 uses Form 89 for structured, traceable furnishing or refusal.
Form 89 is the electronic statutory form used by the designated Income-tax authority to furnish permissible information in response to a valid application by an authorised public authority under section 258(2)(a) of the Income-tax Act, 2025, for a specified assessee and a single tax year. It is an event-based form, furnished through the Department's system with DIN and system-generated authentication, and is linked to the corresponding application in Form 88. The form contains assessee particulars in Part A and disclosure-limited information details in Part B, and it also allows recording of refusal, wholly or partly, where disclosure is not considered to be in the public interest.
March 30, 2026
Show AI Summary
Taxpayer information disclosure under authorised application governs Form 089, with electronic furnishing and limited, confidential disclosure.
Form 089 is the statutory online form used by designated income-tax authorities to furnish taxpayer-related information in response to a valid application made by an authorised public authority under section 258(2)(a) of the Income-tax Act, 2025. It is tax-year specific, furnished electronically, and may be used only for information available in departmental records and within the permissible scope of disclosure. The authority may refuse disclosure for unauthorised, invalid, incomplete, or overbroad requests, and the reasons must be recorded electronically.
March 30, 2026
Show AI Summary
Assessee information requests under the Income-tax Act now require online Form 88 filing by authorised public authorities only.
Form 88 is the prescribed application for obtaining information about an assessee under Section 258(2)(a) of the Income-tax Act, 2025. It is available only to authorised public authorities, including regulatory and law-enforcement agencies, government departments authorised under Rule 155, and other competent authorities empowered by the Central Government. A separate application is required for each assessee and each tax year; consolidated requests are not allowed. The form must be filed online through the e-Filing portal with electronic verification and supporting documents uploaded electronically.
March 30, 2026
Show AI Summary
E-commerce duty moratorium ends unresolved as WTO members defer tariff and TRIPS safeguards talks.
The World Trade Organization meeting ended without consensus on extending the moratorium on customs duties on electronic transmissions, leaving the issue of tariffs on digital downloads and streaming unresolved. The lapse of the moratorium also coincided with the expiry of the TRIPS non-violation complaint safeguard, increasing the possibility of challenges to WTO-compliant measures and reducing policy space for developing countries. Related WTO reform and e-commerce work programme discussions were also deferred for continued negotiation in Geneva.
March 30, 2026
Show AI Summary
Insolvency and bankruptcy reform drives banking health, with proposed changes aimed at faster admission of resolution applications.
The Insolvency and Bankruptcy Code is described as a central mechanism for improving banking sector health through recovery of non-performing assets under the insolvency resolution process. The proposed amendment Bill seeks further changes to the framework, including measures to reduce the time taken for admission of insolvency resolution applications, while the resolution process is said to have coincided with better company performance and improved corporate governance.
March 30, 2026
Show AI Summary
Taxpayer information requests under Form 088 require authorised filing, specific grounds, separate tax year submissions, and electronic portal authentication.
Form 088 is the online application used by authorised public authorities, regulatory bodies, law-enforcement agencies, and other competent authorities to seek specific taxpayer information under Section 258(2)(a) of the Income-tax Act, 2025. It must be filed separately for each taxpayer and each tax year through the e-Filing portal, with narrowly framed particulars, stated reasons, and supporting authorisation where necessary. Incomplete, overbroad, or unauthorised requests may be returned or rejected, and communications are issued electronically with portal-based status tracking.
March 30, 2026
Show AI Summary
Tonnage Tax Scheme audit report filing requires accountant certification, supporting annexures, and electronic submission within the specified date.
Form No. 81 is prescribed for furnishing the audit report under section 232(21) for a company that has opted for taxation under the Tonnage Tax Scheme. The report, prepared and certified by an accountant, verifies books of account, computation of shipping income, compliance with charter-in limits, and other statutory conditions. It is to be furnished on or before the specified date and may include annexures such as charter arrangement certificates, related party notes, asset notes, and loss statements.
March 30, 2026
Show AI Summary
Tonnage Tax Scheme reporting requires accountant certification, separate books, and detailed disclosure of shipping income and compliance.
Form 81 is an accountant's report for a company opting for the Tonnage Tax Scheme, certifying the correctness of books of account and income computation for qualifying ships. It requires separate books, disclosure of charter-in compliance, shipping income, statutory reserve details, ship-wise tonnage income, related party transactions, depreciation, non-exclusive assets, and losses, with mandatory annexures where applicable and reasons for any negative or qualified answers.
March 30, 2026
Show AI Summary
Tonnage Tax Scheme option filing requires Form 80, supporting vessel documents, and electronic verification of eligibility.
Form No. 80 is the prescribed electronic application for an Indian company engaged in operating ships or inland vessels to exercise or renew the option to be governed by the Tonnage Tax Scheme. It requires particulars of the applicant, ships or inland vessels, supporting certificates and approvals, and is used to verify whether the statutory conditions for coverage under Chapter XII-G are satisfied.
March 30, 2026
Show AI Summary
Tonnage tax scheme application rules govern Form 80 filing, renewal, verification, completeness, and false statement liability.
Form 80 is the mandatory application for an eligible Indian company engaged in the operation of ships or inland vessels to exercise or renew the option under the tonnage tax scheme. The form must be filed within the prescribed time, includes Part A for all cases and Part B only for renewal, and requires detailed ship-wise particulars with supporting annexures. It is filed with the jurisdictional Joint Commissioner and must be signed by the authorised signatory. Incomplete applications may be treated as invalid, and false statements in the form or annexures attract prosecution.
March 30, 2026
Show AI Summary
Pass-through taxation reporting for investment funds through Form 79, with unit holder income disclosure and auto-generated statements.
Form 79 is the consolidated annual statement for Investment Funds to report income paid or credited to unit holders under the pass-through taxation framework. Eligible Category I or Category II AIFs, and comparable IFSCA-regulated funds subject to the stated conditions, must file it annually by 15 June with detailed fund-level income, loss, set-off, and unit holder-wise distribution particulars. The form requires verification by both an authorised person and a qualified accountant, and its filing triggers auto-generation of Form 78 statements for unit holders.
March 30, 2026
Show AI Summary
Investment fund income distribution reporting requires Form 79 filing online with supporting records and prescribed timelines.
Form 79 is the statement of income paid or credited by an investment fund to persons liable to tax on such income, and it must be filed by the person responsible for making the payment or credit on behalf of the fund. The statement is to be submitted online through the Income Tax e-filing portal by 15 June of the financial year following the tax year, with supporting records including audited financial statements, unit holder details, income distribution data, loss set-off computations, and the relevant registration certificate.

News

Back

All News

Showing Results for :
Reset Filters
No Records Found

News

Back

All News

Showing Results for : Reset Filters
News and Press Release

Flash Report on Central Sector Infrastructure Projects worth ₹150 crore and above

April 25, 2026

Contents
Summary
Note

Note

-

Bookmark

Print

Print

PAIMANA Portal Tracks 1,941 Infrastructure Projects worth ₹41.50 lakh crore as of March 2026

The Ministry of Statistics and Programme Implementation (MoSPI) continues to strengthen monitoring of Central Sector infrastructure projects through its PAIMANA platform, enabling improved tracking, timely reviews, and data-driven decision-making across Ministries. The portal tracks 1,941 Infrastructure Projects worth of ₹41.50 lakh crore as of March 2026.

Key Highlights

  • As of March 2026, 1,941 ongoing infrastructure projects, with a total revised cost of ₹41.50 lakh crore, are being monitored across 17 Central Ministries/Departments. The cumulative expenditure incurred on these projects stands at ₹19.93 lakh crore, accounting for approximately 48.02 per cent of the revised project cost, indicating steady progress in project implementation.
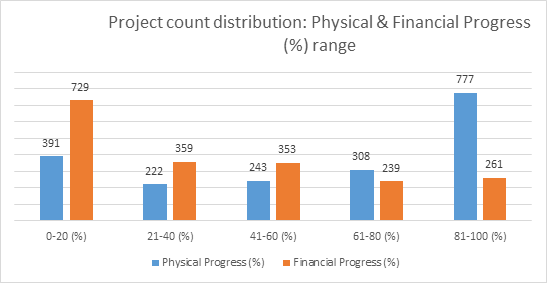
  • A significant proportion of projects are at advanced stages, with 777 projects (~40%) achieving over 80% physical progress, while 261 (~13%) have crossed 80% financial completion. The data also reflects a balanced pipeline, with projects distributed across early and advanced stages of implementation.
  • The Transport & Logistics sector (as per the DEA’s Harmonized Master List) accounts for the highest number of ongoing projects (1428 projects), with revised estimates of ₹22.66 lakh crore underscoring priority to connectivity-driven infrastructure growth.
  • 1,941 ongoing infrastructure projects include 786 Mega projects (project cost of ₹1,000 crore & above) with an original cost of ₹30.48 lakh crore, and 1,155 Major projects (project cost below ₹1,000 crore and up to ₹150 crore) amounting to ₹5.41 lakh crore.
  • Physical and financial progress broadly move in tandem, with a large number of projects clustered at the initial (0–20%) and advanced (81–100%) stages, indicating a pipeline of newly-started projects alongside many nearing completions. While physical progress exceeds financial progress in the 81–100% range, financial progress is relatively higher in the early stages, reflecting upfront expenditure patterns in project implementation.
2.   Ministry/ Departments-wise progress of Infrastructure Projects

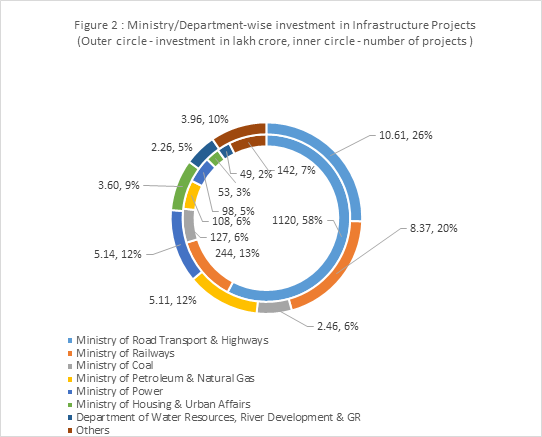
  • Ministry of Road Transport & Highways accounts for the highest number of projects, with 1120 projects (58%), and a share of total revised project cost of ₹10.61 lakh crore (26%), highlighting its central role in national infrastructure development.
  • Ministry of Railways is implementing 244 projects (13%), and also commands the largest share of total revised project cost at ₹8.37 lakh crore (20%).
  • Ministry of Coal accounts for implementing 127 projects (6%), with a total revised project cost of ₹2.46 lakh crore (6%).
  • The Ministry of Petroleum & Natural Gas, Ministry of Power, Ministry of Housing & Urban Affairs, and the Department of Water Resources, River Development & GR are implementing 108, 98, 53, and 49 projects, with associated revised costs of ₹5.11 lakh crore, ₹5.14 lakh crore, ₹3.6 lakh crore, and ₹2.26 lakh crore, respectively.
  • The remaining 142 projects (7%), with a total revised cost of ₹3.96 lakh crore (10%), are distributed across various Ministries/Departments including Higher Education, Civil Aviation, Steel, Telecommunications, Labour & Employment, Ports, Shipping & Waterways, Health & Family Welfare, Mines, DPIIT, and Sports. (Refer Annexure I)
3.   Sector-wise (as per DEA’s Harmonized Master List of Infrastructure) Progress of Infrastructure Projects

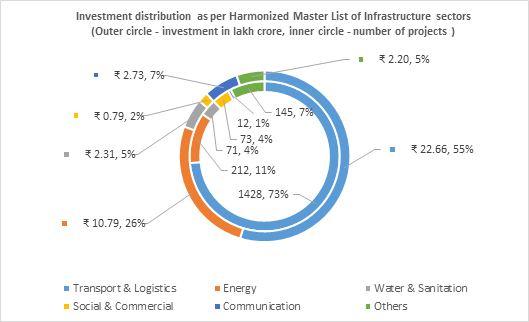
  • Transport & Logistics remains the dominant sector, accounting for 55% of total revised cost (₹22.66 lakh crore) across 1,428 projects (73 % of the total Projects), underscoring the central role of Roads & Highways, Railways, Aviation, Urban Public Transport, Shipping, and Inland Waterways in economic integration and logistics efficiency.
  • The Energy sector follows with 26% of aggregated revised cost (₹10.79 lakh crore) across 212 projects, reflecting sustained emphasis on Oil & Gas infrastructure, electricity generation, transmission and distribution networks, and energy storage systems.
  • Communication infrastructure, with a revised cost of ₹2.73 lakh crore (7%) across 12 projects, represents targeted interventions aimed at strengthening digital connectivity.
  • Water & Sanitation projects account for ₹2.31 lakh crore (5%) across 71 projects, highlighting continued focus on essential urban services.
  • Social & Commercial infrastructure, comprising 73 projects with a revised cost of ₹0.79 lakh crore (2%), reflects selective investments in education, healthcare, real estate, and tourism, hospitality and wellness.
  • Projects classified under ‘Others’, amounting to ₹2.20 lakh crore (5%) across 145 projects, indicate diversification across sectors such as coal, steel, metals, and mining.

(Refer Annexure II)
4.   Completed Projects and New Additions

  • During March 2026, 25 projects were commissioned, including major assets in Road Transport & Highways, Petroleum & Natural Gas, Housing & Urban Affairs, Railways, Power, Ports, Shipping and Waterways, Telecommunications, Steel and Labour and Employment. Notable commissioned projects include the “Delhi-Ghaziabad-Meerut Regional Rapid Transit System [RRTS] corridor” (₹ 30,274 crore) from Ministry of Housing & Urban Affairs, and the “Tehri Pumped Storage Plant Project [4x250 MW] (₹ 8,339 crore) from Ministry of Power.
  • During March 2026, 12 additional projects from MoRTH were brought under the monitoring of PAIMANA.

5.    Next date of Press Release: Flash Report for the month of April 2026 would be released on 25th May 2026.

Note

  1. The press release summarizes highlights from the MoSPI’s Flash Report (March 2026) on Central Sector Infrastructure Projects (₹150 crore and above), available at https://www.ipm.mospi.gov.in/ or via the QR code.
 

  1. PAIMANA is a centralized web-based portal for monitoring of Central Sector Infrastructure Projects worth ₹150 crore and above. Operating on the "one data, one entry" principle, it integrates with DPIIT’s IPMP portal via APIs to automatically update more than 70% of project data from various Ministries/Departments. PAIMANA also serves as a national repository designed to standardize infrastructure monitoring and support informed decision-making for nation-building.

Annexure I

Ministry/ Departments-wise progress of Central Sector Infrastructure Projects

S. No

Ministry/ Department

Project Count

Revised Cost

(₹ Lakh cr.)

Cumulative Expenditure           (₹ Lakh cr.)

1

Ministry of Road Transport & Highways

1120

10.61

3.52

2

Ministry of Railways

244

8.37

5.69

3

Ministry of Coal

127

2.46

0.80

4

Ministry of Petroleum & Natural Gas

108

5.11

2.99

5

Ministry of Power

98

5.14

1.94

6

Ministry of Housing & Urban Affairs

53

3.60

1.98

7

Department of Water Resources, River Development & GR

49

2.26

1.61

8

Department of Higher Education

29

0.14

0.08

9

Ministry of Civil Aviation

26

0.23

0.11

10

Ministry of Health & Family Welfare

23

0.21

0.08

11

Ministry of Steel

19

0.23

0.10

12

Ministry of Labour and Employment

12

0.03

0.02

13

Department of Telecommunications

12

2.73

0.77

14

Ministry of Ports, Shipping and Waterways

11

0.22

0.15

15

Ministry of Mines

6

0.10

0.07

16

Department for Promotion of Industry & Internal Trade

3

0.05

0.01

17

Department of Sports

1

0.01

0.01


Total

1941

41.50

19.93


Annexure II

Sector-wise (as per DEA’s Harmonized Master List of Infrastructure) progress of Central Sector Infrastructure Projects

S. No

HML Category

Project Count

Revised Cost      (₹ Lakh cr.)

Cumulative Expenditure      (₹ Lakh cr.)

1

Transport & Logistics

1428

22.66

11.28

2

Energy

212

10.79

5.21

3

Water & Sanitation

71

2.31

1.65

4

Communication

12

2.73

0.77

5

Social & Commercial

73

0.79

0.34

6

Others

145

2.21

0.67


Total

1941

41.50

19.93


Topics

Acts Income Tax

