 TaxTMI
Login
 TaxTMI

Login
Loading...
Press 'Enter' to add multiple search terms. Rules for Better Search
 of 3382

Press 'Enter' after typing page number.
of 3382 Press 'Enter' after typing page number.


No Folders have been created
Are you sure you want to delete "My most important" ?
NOTE:
of 3382 Press 'Enter' after typing page number.
of 3382 Press 'Enter' after typing page number.

All News
of 3382 Press 'Enter' after typing page number.
All News

Note

Bookmark

Share


The sixtieth meeting of the Monetary Policy Committee (MPC), constituted under Section 45ZB of the Reserve Bank of India Act, 1934, was held during April 6 to 8, 2026.
2. The meeting was chaired by Shri Sanjay Malhotra, Governor and was attended by all the members – Dr. Nagesh Kumar, Director and Chief Executive, Institute for Studies in Industrial Development, New Delhi; Shri Saugata Bhattacharya, Economist, Mumbai; Professor Ram Singh, Director, Delhi School of Economics, Delhi; Dr. Poonam Gupta, Deputy Governor in charge of monetary policy and Shri Indranil Bhattacharyya, Executive Director (the officer of the Reserve Bank nominated by the Central Board under Section 45ZB(2)(c) of the Reserve Bank of India Act, 1934).
3. According to Section 45ZL of the Reserve Bank of India Act, 1934, the Reserve Bank shall publish, on the fourteenth day after every meeting of the Monetary Policy Committee, the minutes of the proceedings of the meeting which shall include the following, namely:
the resolution adopted at the meeting of the Monetary Policy Committee;
the vote of each member of the Monetary Policy Committee, ascribed to such member, on the resolution adopted in the said meeting; and
the statement of each member of the Monetary Policy Committee under sub-section (11) of section 45ZI on the resolution adopted in the said meeting.
4. In the light of evolving developments on the global and domestic front, the MPC reviewed in detail the staff’s macroeconomic projections that included inputs from survey results and stakeholder consultations. The MPC also reviewed alternative scenarios around various risks to the outlook. Drawing on the above and after extensive discussions on the stance of monetary policy, the MPC adopted the resolution that is set out below.
Resolution
5. The Monetary Policy Committee (MPC) held its 60th meeting from April 6 to 8, 2026, under the chairmanship of Shri Sanjay Malhotra, Governor, Reserve Bank of India. The MPC members Dr. Nagesh Kumar, Shri Saugata Bhattacharya, Prof. Ram Singh, Dr. Poonam Gupta and Shri Indranil Bhattacharyya attended the meeting.
6. After a detailed assessment of the evolving macroeconomic and financial developments and the outlook, the MPC voted unanimously to keep the policy repo rate under the liquidity adjustment facility (LAF) unchanged at 5.25 per cent. Consequently, the standing deposit facility (SDF) rate remains at 5.00 per cent and the marginal standing facility (MSF) rate and the Bank Rate remains at 5.50 per cent. The MPC also decided to continue with the neutral stance.
Growth and Inflation Outlook
Global Outlook
7. The outbreak of the conflict in West Asia has led to severe disruption of global supply chains. This poses an unprecedented challenge for the global economy – higher prices and lower global growth. In this environment, monetary policy faces a difficult trade-off – anchoring inflation expectations through policy tightening while minimising its impact on growth forgone. Sovereign bond yields, already high from long-run fiscal sustainability concerns across major economies, have further hardened, driven by inflation fears. Additionally, equity valuations have corrected. As a result of the turmoil in global financial markets, the US dollar has rallied, buoyed by safe-haven demand that has exerted pressure on currencies of major economies. Further intensification of the conflict, its prolongation and widening geographical spread remain the key downside risks to the global outlook.
Domestic Outlook
8. On the domestic front, the Indian economy remained resilient in 2025-26. Real gross domestic product (GDP) is estimated to grow by 7.6 per cent (y-o-y) during the year, as per the Second Advance Estimates (SAE) of the new GDP series (base year 2022-23). Private consumption and fixed investment contributed significantly to overall growth, while net external demand remained soft. On the supply side, estimated real GVA growth of 7.7 per cent was driven by buoyant services sector and robust manufacturing activity.
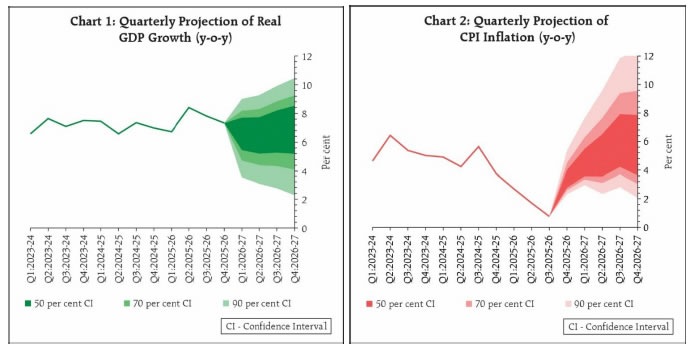
9. Looking ahead, elevated energy and other commodity prices coupled with supply shock due to disruptions in the Strait of Hormuz would act as a drag on domestic production in 2026-27. Heightened volatility in global financial markets with its spillover on domestic financial conditions would weigh on growth prospects. On the external front, merchandise exports may be adversely impacted from disruptions to key shipping routes and the concomitant rise in freight and insurance costs in case the conflict is long-drawn. On the other hand, sustained momentum in services sector, persisting impact of GST rationalisation, rising capacity utilisation in manufacturing, and healthy balance sheets of financial institutions and corporates should continue to support domestic demand. In this milieu, the Government’s focus on scaling up domestic manufacturing in several strategic and frontier sectors announced in the Union Budget 2026-27 bodes well for India’s ensuing growth trajactory. Taking all these factors into consideration and on the assumption that the adverse impact of the conflict would remain contained in the near term, real GDP growth for 2026-27 is projected at 6.9 per cent, with Q1 at 6.8 per cent; Q2 at 6.7 per cent; Q3 at 7.0 per cent; and Q4 at 7.2 per cent (Chart 1). Further escalation of the conflict, its continuation over a wider geographical spread and uncertainty regarding the damage to the energy infrastructure, apart from weather related events, pose downside risks to the domestic growth outlook.
10. As per the new CPI series (2024=100), headline inflation increased to 3.2 per cent in February 2026 from 2.7 per cent in January. The uptick was primarily driven by unfavourable base effects even as the momentum remained muted. While food inflation increased in February, core (excluding food and fuel) inflation remained unchanged. Excluding precious metals, core inflation remained moderate at 2.1 per cent in January and February, suggesting subdued underlying inflation pressures.
11. The ongoing conflict has led to large volatility in international energy and other commodity prices imparting considerable uncertainty to the near-term inflation outlook. The pass-through of higher global energy prices has resulted in price increases in select fuels such as premium petrol and LPG and diesel for industrial use. On the other hand, the near-term food supply prospects have been boosted by robust rabi crop providing some comfort. Considering all these factors, CPI inflation for 2026-27 is projected to be at 4.6 per cent with Q1 at 4.0 per cent; Q2 at 4.4 per cent; Q3 at 5.2 per cent; and Q4 at 4.7 per cent. Persistently elevated energy prices due to the West Asia conflict and possible El Niño conditions (which could have a negative impact on southwest monsoon) pose upside risks to inflation (Chart 2). Core inflation is projected at 4.4 per cent for 2026-27 and, excluding precious metals, it is even lower indicating that underlying inflation pressures are expected to remain contained.
Rationale for Monetary Policy Decisions
12. Since the last policy meeting, geopolitical uncertainties have heightened significantly. Headline inflation remains contained and below the target, but upside risks to the inflation outlook have increased, driven by increased energy price pressures and probable weather disturbances affecting food prices. Core inflation pressures remain muted, although supply chain dislocations and the risk of second-round effects render the future inflation trajectory uncertain.
13. High frequency indicators till February 2026 suggest the continuation of strong momentum in economic activity. Growth impulses continue to be supported by robust private consumption and investment demand. However, the West Asia conflict will adversely impact growth. Higher input costs associated with increase in energy prices and international freight and insurance costs along with supply-chain disruptions could constrain availability of key inputs for downstream sectors, thus impairing growth. The Government has taken several measures targeted at supporting exports and protecting supply chains, which should mitigate the adverse impact of the conflict.
14. The MPC noted that the intensity and the duration of the conflict in West Asia and the resultant damage to the energy and other infrastructure add risk to the inflation and growth outlooks. However, the fundamentals of the Indian economy are on a stronger footing, providing it with greater resilience to withstand shocks now than in the past. The economy is confronted with a supply shock. It is prudent to wait and watch the changing circumstances and the evolving growth-inflation outlook. Accordingly, the MPC voted to keep the policy rate unchanged even as it remains vigilant, closely monitoring incoming information and assessing the balance of risks. The MPC also decided to continue with the neutral stance, retaining the flexibility to respond judiciously to incoming information.
15. The minutes of the MPC’s meeting will be published on April 22, 2026.
16. The next meeting of the MPC is scheduled for June 3 to 5, 2026.
Voting on the Resolution to keep policy repo rate unchanged at 5.25 per cent
| Member | Vote |
| Dr. Nagesh Kumar | Yes |
| Shri Saugata Bhattacharya | Yes |
| Prof. Ram Singh | Yes |
| Shri Indranil Bhattacharyya | Yes |
| Dr. Poonam Gupta | Yes |
| Shri Sanjay Malhotra | Yes |
Statement by Dr. Nagesh Kumar
17. The April 2026 MPC Meeting is taking place against the backdrop of the West Asia conflict dramatically clouding the economic outlook for the global economy with significant spillovers for the Indian economic outlook for 2026-27. At the time of the February 2026 MPC meeting, the outlook for the Indian economy seemed to have brightened considerably with the conclusion of the long-pending EU-India FTA negotiations on 27 January, the withdrawal of high Trump tariffs on exports to the US in February, and boosted by the Union Budget 2026-27 proposals, while inflation remained benign. The Indian economy appeared poised to sustain the so-called ‘goldilocks’ phase for longer and the move from 7.6% GDP growth expected in 2025-26, to a higher growth trajectory touching 8% in the near term seemed feasible.
18. While the domestic engines of India’s economic growth, namely private consumption and investments, and government consumption and capex, remain robust, with some concerns on the agriculture front arising from a possible El Niño phenomenon affecting the monsoons, the West Asia conflict has affected the Indian economy through several channels. India’s high dependence on crude oil, natural gas and fertilizer imports from the Middle East is the most important channel for transmission of spillovers. The blockage of the Strait of Hormuz has disrupted the supplies and has sent the crude prices through the roof. The crude oil prices are important factor affecting India’s economic growth and inflation outlook. The Gulf region is also an important destination for India’s exports and a major source of remittances. The overall economic sentiment is also affected, with international agencies lowering the global GDP growth projections for 2026 by 40 basis points to 2.9% from 3.3% in 2025. The rupee has come under pressure due to the combined effect of rising oil prices, short-term capital outflows, and the strengthening of the dollar.
19. With the weak global economy affecting the growth of exports and crude prices pushing the import bill, the current account deficit, which has stayed in the comfortable range of 1.5% of GDP in the past, is likely to worsen. The natural gas shortages have affected many MSMEs that use it as a fuel. The government has taken action to contain the damage to ease the supply of crude and natural gas through diplomacy while containing the retail prices from rising through lowering the excise duty. India also needs to diversify its sources of imports and export markets, especially by taking advantage of the new FTAs with European countries, among others. This would require preparing the Indian industry to deepen its penetration in European markets, especially in labour-intensive sectors like textiles and garments, leather goods and footwear, gems and jewellery, and marine products with enhanced scales of production and compliance with standards, etc.
20. With the assumption of crude prices averaging $85 per barrel for the year, the growth projections for the Indian economy for FY 2027 have been lowered by 70 basis points to 6.9% from an estimated 7.6% in FY2026. With the combined effect of rising crude prices, exchange rate movements, possible effect of input costs on food prices, among others, the headline inflation is projected to rise to 4.6% in FY 2027 from a very benign level of 2.1% in FY 2026. The dramatic rise in inflation, however, is clearly resulting from a supply shock and not a demand-push one.
21. In the current highly uncertain economic environment, prudence requires a status quo on monetary policy action. One needs to keep an eye on the evolving geopolitical situation in West Asia and its implications for the Indian economic outlook. Hence, I vote for the status quo on the repo rate and support retaining the neutral stance.
Statement by Shri Saugata Bhattacharya
22. In my February 2026 statement, I had noted not just higher forecast inflation, but the risk of accumulating inflationary pressures. In addition, the impending release of the new economic data series following base revisions, were anticipated to provide indicators better reflecting the present economic environment. Hence, I had voted for status quo.
23. Two months later, in April 2026, the balance of risks, due to the conflict in West Asia and related geopolitical repercussions, has changed materially. Consequently, at this point, for the reasons outlined below, the evolution of the growth–inflation trade-off in India, a primary concern for my own response, remains clouded.
Despite tentative indications of a cessation of hostilities in the West Asia conflict and a consequent easing of tight global financial conditions, uncertainty regarding persisting dislocations of global supply chains remains heightened.
Energy prices are unlikely, in the near or even the medium term, to return to their pre-conflict levels. Global supply chains have been repeatedly disrupted in the past few years, adding to output costs. Persisting disruptions will result in a non-linear escalation of cumulative macroeconomic consequences.
On growth, recent high frequency indicators of economic activity show continued resilience in March, although “nowcast” metrics are showing early signs of a slowdown. The forthcoming Q4 FY26 company results will provide an updated picture for the larger listed companies and this will signal the effects down the supply chains into smaller enterprises.
On inflation, we note the preliminary forecasts by some private meteorological organisations, on the likelihood of hotter summers and the likely onset of El Niño. These might add to the ongoing supply shocks.
More worrying, inflation expectations signal risks of rising inflation. While one-year ahead expectations in the March 2026 RBI Household Inflation Expectations Survey remain relatively anchored, 3-month ahead expectations rose sharply by 60 basis points (bps). Perceptions of annual inflation in rural and semi-urban households rose by 50 basis points. The IIM Ahmedabad Business Inflation Expectations Survey (BIES) shows a very sharp increase in one year ahead inflation.
Given the extant uncertainty, quantitative forecasts of growth and inflation, while useful for guidance, have limited traction for informing policy decisions.
India’s balance of payments and trade are likely to be impacted. Domestic production disruptions and logistics bottlenecks are likely to impact merchandise exports. Trade in IT services might also be hit as discretionary spends on technology are cut. Remittances from the Gulf countries might be at risk.
The capital account remains potentially vulnerable to global geo-economic developments. With rising global inflationary pressures, the space for major global central banks to further ease rates seems to have shrunk, likely inducing spill-over effects on capital flows into India.
Layered on this are the effects of amorphous US tariff notifications and the outcomes of various bilateral trade agreements.
A reading of past episodes suggests that there is no standard prescription on how to respond to oil price shocks, whether standalone or triggered by war.1
24. As has been noted, monetary policy cannot influence energy prices but can facilitate the process of economic adjustment in a way that sustainably achieves inflation targets.
25. For me, the risks of a policy mistake have heightened amidst this uncertainty. Arguments for increasing the policy rate in anticipation of higher inflation are as risky as cutting rates in response to a fear of lower growth. Quantifying the glide path along a precise timeline is not an exact science. The challenge is to determine the extent of the shocks being transitory versus persistently percolating through the economy, and the time expected for both inflation and growth to revert to targets.
26. I am also guided by domestic financial conditions having tightened significantly, which amounts to a de facto policy tightening. Hence, a status quo at this time is likely to have the lowest cost. Hence, I vote to keep the repo rate unchanged at this meeting. Given the fluidity of the macro-financial environment, it is also appropriate to retain the neutral stance.
Statement by Prof. Ram Singh
27. The West Asia conflict could likely shift the Indian growth-inflation trade-offs from a Goldilocks state (low inflation and high growth) in February 2026 to the opposite extreme. Brent crude oil prices have surged over 40%, from around $76–$77/bbl at the beginning of March to cross above $104/bbl by the end of the month, with peaks reaching over $110/bbl. Consequently, the macroeconomic environment has changed drastically over the last month. Today, the Growth-Inflation-Risk triad - balancing economic growth, controlling inflationary pressures, while managing the associated risks – presents an unusual challenge for the Indian economy.
28. The turmoil in the Strait of Hormuz is a drag on growth directly through oil supply disruptions and their effect on demand. This, along with disruptions in key shipping lines, has dampened the growth prospects of the global economy and Indian exports. As of April 2026, the real GDP growth forecast for 2026-27 in Q1 is at 6.8 per cent, Q2 at 6.7 per cent, Q3 at 7.0 per cent, and Q4 at 7.2 per cent. The real GDP growth for 2026-27 is projected at 6.9 per cent, with downside risks increasing as the conflict persists. As per my assessment, the growth forecast is lower by 50-60 bps as of now due to the West Asia conflict.
29. In contrast, the inflation forecast is being revised upward. The supply disruptions caused by the conflict and the resulting spike in freight and insurance costs have led to sharp increases in global energy and other commodity prices. Increased fuel prices raised transportation costs, and fertiliser prices added to the pressure on core inflation. For FY 2026-27, CPI inflation is forecasted at 4.6 per cent - 4.0 per cent for Q1; 4.4 per cent for Q2; 5.2 per cent for Q3; and 4.7 per cent for Q4. Weather-related events - El Niño disturbances - pose downside risks to the domestic growth outlook, and an upside risk for the inflation trajectory.
30. While the direction of impacts of the West Asia conflict and El Niño disturbances on growth and inflation is clear, the quantum of impact will depend on how long it lasts. The overall effects on growth and inflation are expected to be highly sensitive to the duration of the conflict. A swift resolution, combined with fiscal and administrative measures to limit the passthrough of petroleum product prices, can see inflation pressures subside to quickly manageable levels.
31. Despite a rise, the inflation trajectory is well within the tolerance band at this point. Core inflation is projected at 4.4 per cent for 2026-27 and is even lower if we exclude precious metals. Thanks to the administrative price control over retail petrol, diesel, and LPG, the inflationary impulse from the sharp escalations in crude prices is not expected to be a sudden spike followed by a slow downward movement, but rather a gradual, moderate rise. High reservoir levels and food stocks will help moderate pressure on food prices due to El Niño disturbances.
32. In this background, there is a case for a dovish pause. The estimated growth cost of the West Asia conflict so far is estimated to be about 50-60 bps, widening the output gap. The underlying inflation, core inflation excluding precious metals, suggests that demand pressure in the coming quarters is expected to remain contained. On the other hand, high input costs driven by energy spikes and supply-side disruptions have disproportionately affected the MSME sector, which lacks the working capital bandwidth to tide over these shocks. A dovish pause in the repo rate, along with adequate fiscal measures, can help these firms deal with the shock. Accordingly, I vote for a pause in the policy repo rate under the liquidity adjustment facility (LAF) at 5.25 per cent.
33. It is true that a dovish pause is not going to help on the external front, especially when the INR has been depreciating, and the Current Account Deficit (CAD) data has been generating mixed signals. In the coming months, CAD is likely to be under added pressure due to high crude and precious metal prices. While the West Asia conflict has increased immediate volatility in both, the persistence of these issues reflects structural challenges facing the economy, such as asymmetric reliance on foreign energy sources and other critical supplies. These problems have to be addressed at a different level. In the short term, administrative and regulatory measures can also help stem the developments related to CAD and INR.
34. The level of uncertainty on the external front in general and the West Asia conflict in particular is high at this point. There seem to be many unknown unknowns whose direct and indirect economic impacts are unquantifiable. Under these circumstances, it seems prudent for the Monetary Policy to be data driven with a focus on keeping inflation expectations anchored. To maintain enough elbow room to move the repo rate in either direction should we end up with an unexpected situation.
35. Therefore, I change my stand on the monetary policy stance from ‘accommodative’ to ‘neutral’.
Statement by Shri Indranil Bhattacharyya
36. Global economic outlook, which was buoyant till the February MPC meeting, has deteriorated significantly after the outbreak of the West Asia conflict. The consequent disruption in logistics network has not only triggered a sharp increase in international energy prices, it has also choked global trade flows, particularly those transiting through the Strait of Hormuz that accounts for about half of India’s energy imports. The macroeconomic impact of the conflict on the global economy, however, would depend on its longevity, scale and the subsequent pace and timeline for normalisation of global supply chains.
37. In the Indian context, the agriculture sector’s prospects remain favourable although it may get somewhat moderated by potential El Niño conditions. Business sentiment, however, suggests continued resilience in both manufacturing and services. Although supply disruptions constrain input availability for downstream sectors, the Government has undertaken several measures to safeguard supply chains and alleviate stress. On the demand side, private consumption is expected to remain robust while investment activity would be supported by sustained spending on public infrastructure. Although merchandise exports may face pressures from subdued global demand and elevated shipping and freight costs, services exports are expected to remain resilient. Taking cognizance of all these factors, real GDP growth is projected to moderate from 7.6 per cent in 2025-26 to 6.9 per cent in 2026-27.
38. Based on the new CPI series, headline inflation remained well within the target in the first two months of 2026 with core inflation remaining contained. For 2026-27, however, the risks to inflation have increased in the wake of the conflict, which has rendered prices highly volatile and extremely sensitive to geo-political news. Although the impact of higher energy prices on domestic inflation has remained muted so far as retail fuel prices remain unchanged, the increase in input costs could exert pressure on prices, going forward. Food inflation outlook remains comfortable although weather disturbances from El Niño conditions remain a key risk. Core inflation is also expected to pick-up due to the pass-through of input cost pressures. In view of the above, annual average inflation is projected at 4.6 per cent in 2026-27, up from 2.1 per cent realised in 2025-26.
39. Due to the conflict, monetary policy is confronted with a supply shock that poses upside risks to inflation and downside risks to growth, as illustrated by the asymmetric fan charts in the MPC resolution. In this context, it is pertinent to note that supply-driven inflation warrants a distinctly different policy response than a demand-driven one.2 Monetary policy has limited ability to quell the direct effects of a supply-induced inflation shock; it only has operational relevance once second-round effects are apparent. These effects are manifested in rising prices and wages when inflation expectations get un-anchored, which is not evident at present. Whether it would materialise and to what extent depends on the durability and geographical spread of the conflict and its attendant impact on inflation expectations. As long as expectations remain anchored, looking through the shock is optimal since any pre-emptive response merely sacrifices output without delivering any significant gain on the inflation front.3 Therefore, it is prudent to wait for more incoming information before taking any definitive course of action. Accordingly, I vote to pause on the policy rate while retaining the neutral stance.
Statement by Dr. Poonam Gupta
40. The Indian economy, along with many other economies in the world, has been subject to multiple external shocks in the last few years. These have included Covid in 2020; Russia-Ukraine war in 2022; and a bruising rate of unilateral tariff by the US in 2025. Just when these shocks seemed to be receding a bit, the West Asia conflict has afflicted the global and Indian economies with significant intensity.
41. It is to the credit of the existing policy frameworks and the timely policy actions that the Indian economy has navigated through all the past shocks. And the same factors shall help in the current shock too.
42. An important development in the last few months has been the release of the revised CPI and GDP series. Having analysed both the series carefully, we believe that the revised series will yield more stable numbers, likely necessitating less significant revisions in the GDP series; and less volatile and more accurate inflation figures.
43. Using the new series, and accounting for ongoing developments at national and global levels, we have made our forecasts for the year 2026-27 along with the quarterly path. These indicate that inflation could increase to 4.6 per cent in 2026-27, but would remain well within the tolerance band. A large part of the projected increase in inflation is due to the base effect, and higher oil prices. The projected inflation is more benign when food, fuel and volatile precious metals are stripped out from headline inflation.
44. Growth is projected to be slightly milder at 6.9 per cent for 2026-27. The current rate of capacity utilisation, and the fact that the high growth of the past years has coincided with benign inflation indicate that India’s growth has been driven by improving fundamentals. Healthy investment rates, both public and private, point to the fact that even as existing capacity is being well utilised, new capacity is being created.
45. What should be the role of monetary policy under the current milieu when global uncertainty has risen from already high levels; the external shock is supply driven; inflation, albeit expected to increase, is likely to remain close to the target; and growth is expected to be subdued? I feel that under the circumstances, central banks need to continue to play a conducive role in supporting the productive requirements of the economy. Constant vigil is warranted while waiting to ascertain the persistence of the supply shock, if any.
46. Hence, I vote for the status quo, i.e., to keep the policy repo rate unchanged at 5.25 per cent. I also propose to retain the stance at neutral, i.e., the future course of policy action ought to be data dependent.
Statement by Shri Sanjay Malhotra
47. Real economic activity in the country, driven by healthy consumption and investment demand and supported by conducive financial conditions and accommodative policies, remained robust in 2025–26.
48. The West Asia conflict poses challenges to the Indian economy through a number of channels – exports, supply of critical commodities, elevated energy and other commodity prices, remittances, uncertainty, subdued global demand, etc. Despite these challenges, the outlook for 2026-27 remains cautiously positive with services, agriculture, and healthy balance sheets continuing to support growth. Private consumption and investment are expected to remain resilient, aided by improving rural demand, sustained public spending, and a pickup in private capex. Merchandise exports are likely to get affected by logistics disruptions, rising freight and insurance costs. On the other hand, despite subdued global demand, services exports and recent trade agreements are expected to provide support. While real GDP growth for 2026-27 is projected at 6.9 per cent, there are risks skewed to the downside from global and weather-related uncertainties.
49. As regards inflation, in the first two months of 2026, headline inflation remained well within the target. While food inflation increased after being in deflation in the preceding four months, fuel inflation was moderate. Various measures of core inflation also remained benign suggesting that underlying inflation pressures remain contained.
50. In terms of the outlook for inflation, retail prices of petrol and diesel have remained unchanged so far and the near-term outlook for food prices remains favourable. While CPI inflation for 2026–27 is projected at 4.6 per cent, escalating global energy prices, elevated input costs and the possible emergence of El Niño conditions pose upside risks.
51. Overall, geopolitical uncertainties have intensified with the conflict widening its spread over the last month. As a result, supply chain disruptions, that may take longer to subside fully and restore the logistics network, pose downside risks to growth and upside risks to inflation. Nevertheless, the Indian economy is on a much stronger footing at the current juncture than at any time before to withstand these shocks.
52. As for monetary policy, this represents a supply shock. The underlying inflation pressures, minus the shock, are contained. If the conflict remains unresolved for a long duration, it can make the task of central banks arduous in their endeavour to rein in inflation expectations while minimising growth sacrifice. With the announcement of the temporary ceasefire, however, there is a possibility of an early resolution of the conflict and normalisation of supply chains. In such a situation, it is prudent to wait and watch, before making any decisive move.
53. Taking all these factors into account, I vote to keep the policy rate unchanged at 5.25 per cent while retaining the neutral stance. Going ahead, one needs to remain circumspect and vigilant, closely monitoring all incoming information to decode its ramifications for the wider economy.
(Brij Raj)
Chief General Manager
1 https://www.riksbank.se/globalassets/media/rapporter/pov/artiklar/engelska/2022/221216/2022_2-monetary-policy-and-inflation-in-times-of-war.pdf
2 Hofmann, B., Manea, C. and Mojon, B. (2024). Targeted Taylor Rules: Monetary Policy Responses to Demand- and Supply-Driven Inflation. BIS Quarterly Review, December.
3 Bandera, N., Barnes, L., Chavaz, M., Tenreyro, S. and von dem Berge, L. (2023). Monetary Policy in the Face of Supply Shocks: The Role of Inflation Expectations, ECB Forum on Central Banking, Sintra.
