 TaxTMI
Login
 TaxTMI

Login
Loading...
Press 'Enter' to add multiple search terms. Rules for Better Search
 of 3381

Press 'Enter' after typing page number.
of 3381 Press 'Enter' after typing page number.


No Folders have been created
Are you sure you want to delete "My most important" ?
NOTE:
of 3381 Press 'Enter' after typing page number.
of 3381 Press 'Enter' after typing page number.

All News
of 3381 Press 'Enter' after typing page number.
All News

Note

Bookmark

Share


The fifty-nineth meeting of the Monetary Policy Committee (MPC), constituted under Section 45ZB of the Reserve Bank of India Act, 1934, was held during February 4 to 6, 2026.
2. The meeting was chaired by Shri Sanjay Malhotra, Governor and was attended by all the members – Dr. Nagesh Kumar, Director and Chief Executive, Institute for Studies in Industrial Development, New Delhi; Shri Saugata Bhattacharya, Economist, Mumbai; Professor Ram Singh, Director, Delhi School of Economics, Delhi; Dr. Poonam Gupta, Deputy Governor in charge of monetary policy and Shri Indranil Bhattacharyya, Executive Director (the officer of the Reserve Bank nominated by the Central Board under Section 45ZB(2)(c) of the Reserve Bank of India Act, 1934).
3. According to Section 45ZL of the Reserve Bank of India Act, 1934, the Reserve Bank shall publish, on the fourteenth day after every meeting of the Monetary Policy Committee, the minutes of the proceedings of the meeting which shall include the following, namely:
the resolution adopted at the meeting of the Monetary Policy Committee;
the vote of each member of the Monetary Policy Committee, ascribed to such member, on the resolution adopted in the said meeting; and
the statement of each member of the Monetary Policy Committee under sub-section (11) of section 45ZI on the resolution adopted in the said meeting.
4. The MPC reviewed in detail the staff’s macroeconomic projections, and alternative scenarios around various risks to the outlook. The MPC also reviewed the surveys conducted by the Reserve Bank to gauge consumer confidence, households’ inflation expectations, corporate sector performance, credit conditions, the outlook for the industrial, services and infrastructure sectors, and the projections of professional forecasters. Drawing on the above and after extensive discussions on the stance of monetary policy, the MPC adopted the resolution that is set out below.
Resolution
5. The Monetary Policy Committee (MPC) held its 59th meeting from February 4 to 6, 2026, under the chairmanship of Shri Sanjay Malhotra, Governor, Reserve Bank of India. The MPC members Dr. Nagesh Kumar, Shri Saugata Bhattacharya, Prof. Ram Singh, Dr. Poonam Gupta and Shri Indranil Bhattacharyya attended the meeting.
6. After a detailed assessment of the evolving macroeconomic and financial developments and the outlook, the MPC voted unanimously to keep the policy repo rate under the liquidity adjustment facility (LAF) unchanged at 5.25 per cent. Consequently, the standing deposit facility (SDF) rate remains at 5.00 per cent and the marginal standing facility (MSF) rate and the Bank Rate remains at 5.50 per cent. The MPC also decided to continue with the neutral stance.
Growth and Inflation Outlook
7. The global economy showed remarkable resilience in 2025, aided and supported by trade front‑loading, a milder‑than‑anticipated impact of tariffs, broad fiscal stimulus and accommodative monetary policy. Inflation is on a path of gradual decline, although it remains above target in several advanced economies. US yields are trading with an upward bias amidst receding expectations of imminent rate cuts underpinned by firm economic data. Equities, supported by sustained investment in tech stocks, have advanced, even as fiscal strains, geopolitical uncertainty and monetary policy divergence continue to impart volatility to financial markets.
8. On the domestic front, real gross domestic product (GDP), as per the First Advance Estimates (FAE), is estimated to grow at 7.4 per cent (y-o-y) in 2025-26. Private consumption and fixed investment contributed significantly to overall growth. Net external demand, however, continued to be a drag, with imports outpacing exports. On the supply side, real GVA growth of 7.3 per cent is driven by buoyant services sector, resilient agricultural sector and revival in manufacturing activity.
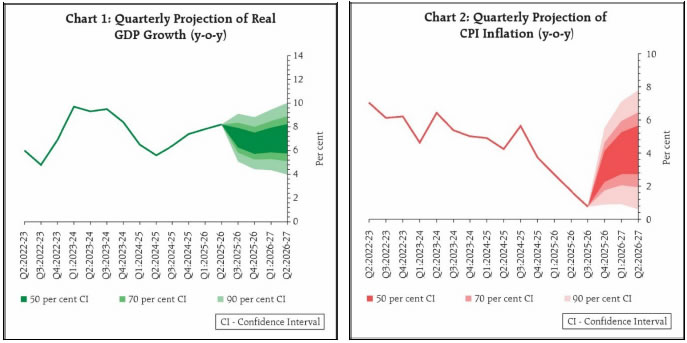
9. Looking ahead, sustained buoyancy in services sector, GST rationalisation, healthy rabi prospects, monetary easing and benign inflation environment should support private consumption. Investment activity, supported by high capacity utilisation, conducive financial conditions, healthy balance sheets of financial institutions and corporates, robust credit growth and Government’s continued thrust on capital expenditure, is expected to maintain its momentum. Moreover, robust domestic demand is likely to attract fresh investments by the private sector. While services exports are expected to remain strong, merchandise exports will get a boost from the prospective trade deal with the US. The landmark comprehensive trade pact with the European Union coupled with trade deals with New Zealand and Oman should help diversify exports and strengthen the external sector. On the other hand, headwinds from geopolitical tensions, uncertain global trade environment, volatility in global financial markets and international commodity prices continue to pose downside risks to the outlook. Taking all these factors into consideration, real GDP growth projections for Q1:2026-27 and Q2 are revised upwards to 6.9 per cent and 7.0 per cent, respectively (Chart 1).1 The risks are evenly balanced.
10. Headline CPI inflation remained low at 0.7 per cent in November and 1.3 per cent in December, 2025. While food group continued to be in deflation, inflation within the fuel group remained moderate in November and December. Core inflation (CPI excluding food and fuel) too remained benign, despite the pick-up in prices of precious metals. Excluding gold, core inflation remained stable at 2.6 per cent in December.
11. Near-term outlook suggests that food supply prospects remain bright on the back of healthy kharif production, adequate buffer stocks of foodgrains and favourable rabi sowing. Core inflation, barring potential volatility induced by prices of precious metals, is expected to be range-bound. Geopolitical uncertainty coupled with volatility in energy prices and adverse weather events are other possible upside risks to inflation. In terms of headline inflation trajectory, unfavourable base effects stemming from large decline in prices observed in Q4:2024-25 would lead to an uptick in y-o-y inflation in Q4:2025-26, despite the anticipated momentum being muted. Considering all these factors, CPI inflation for 2025-26 is now projected at 2.1 per cent with Q4 at 3.2 per cent. CPI inflation for Q1:2026-27 and Q2 are projected at 4.0 per cent and 4.2 per cent, respectively (Chart 2). Excluding precious metals, the underlying inflation pressures remain muted. The risks are evenly balanced.
Rationale for Monetary Policy Decisions
12. The MPC noted that since the last policy meeting, external headwinds have intensified though the successful completion of trade deals augurs well for the economic outlook. Overall, the near-term domestic inflation and growth outlook remain positive.
13. Headline inflation during November-December remained below the tolerance band of the inflation target. The outlook for CPI inflation in Q1:2026-27 and Q2 continues to be benign and near the inflation target. The slight upward revision in the inflation outlook is primarily due to increase in prices of precious metals, which contribute about 60-70 basis points. The underlying inflation continue to be low.
14. On the growth front, economic activity remains resilient. The First Advance Estimates suggest continuing growth momentum, driven by domestic factors amidst a challenging external environment. The growth outlook remains favourable.
15. Based on a comprehensive review of the domestic macroeconomic conditions and the outlook, the MPC is of the view that the current policy rate is appropriate. Accordingly, the MPC voted to continue with the existing policy rate. The MPC also agreed to retain the neutral stance. However, Prof. Ram Singh retained his view that the stance be changed from neutral to accommodative. Going forward, the MPC will be guided by the evolving macroeconomic conditions and the outlook based on data from the new series in charting the future course of monetary policy.
16. The minutes of the MPC’s meeting will be published on February 20, 2026.
17. The next meeting of the MPC is scheduled for April 6 - 8, 2026.
Voting on the Resolution to keep policy repo rate unchanged at 5.25 per cent
| Member | Vote |
| Dr. Nagesh Kumar | Yes |
| Shri Saugata Bhattacharya | Yes |
| Prof. Ram Singh | Yes |
| Shri Indranil Bhattacharyya | Yes |
| Dr. Poonam Gupta | Yes |
| Shri Sanjay Malhotra | Yes |
Statement by Dr. Nagesh Kumar
18. The economic outlook for the Indian economy has brightened considerably since the December 2025 MPC Meeting. The conclusion of the long-pending EU-India FTA negotiations on 27 January, followed quickly by the announcement of the US-India trade deal have helped to lift the sentiment, which had been depressed by the imposition of 50% tariffs on India’s exports by the US since August 2025. The first advance estimates for 2025-26 suggest continued growth momentum. This momentum has been further boosted by the Union Budget 2026-27 proposals, including for fostering the manufacturing sector, tourism, services, including the new Data Centres policy, while sustaining the big thrust to the infrastructure capex. Together, these developments have lifted India’s economic outlook significantly.
19. The economic outlook has also been looking up even before these recent events, with improved manufacturing performance and accelerated growth of IIP manufacturing in Q3: 2025-26, a strong infrastructure pipeline, and continued robust rural consumption, which is now complemented by a turnaround of urban demand. These improvements happened against the backdrop of the fact that high US tariffs did hit India’s exports of non-exempted goods, especially the labour-intensive goods. However, we were able to diversify our exports to alternative markets. Hence, the loss of export earnings was minimised. Having expressed my concerns at previous MPC meetings about the implications of potential loss of export opportunities in the US due to high tariffs, particularly in labour-intensive goods such as textiles and garments, leather goods, gems & jewellery and shrimp, among other food products, I am very impressed by the ability of our exporters to diversify to other markets with the government support measures. The diversification of export markets should not stop now that we have the market access in the US back, with the trade deal.
20. The most important implication of the new trade deals is that India is back at the table as the most promising destination for China+1 supply chain restructuring, given its large and fast growing domestic market, abundant skills, a robust and stable economic framework, fast improving infrastructure and logistics, with zero duty access to virtually entire European market (considering the EFTA, UK and EU deals), Australia, UAE, Japan, Korea, among other markets, and access to the US market at 18% tariff level, which is comparable to its peers, if not better. This brightens the outlook for FDI inflows and for manufacturing.
21. The inflation outlook continues to remain benign, with headline CPI remaining low at 1.3% in December 2025, and the inflation outlook not showing any concerns of overheating. With the opening up of Venezuelan oil supplies for India, brightening of the prospects of the Iran deal, the oil prices are likely to remain in check. The upshot of these trends, namely brightening economic growth outlook amid a continued benign inflationary trend, provides an opportunity for India to stay in the ‘goldilocks’ zone for longer.
22. This leads to a possible changed narrative for monetary policy discussion. The monetary policy actions in the recent past were addressed to curb the inflationary pressures or to help support economic recovery. Now, with the continued benign inflationary outlook opening up some policy space and with growth rates looking up, the monetary policy may turn its focus to support the acceleration of economic growth rates from around 7% to around 8%, complementing the fiscal policy, in tune with the Viksit Bharat vision.
23. However, at this juncture, maintaining the status quo is a prudent action, as we await the new data series on both CPI and growth rates, and the transmission of the December policy rate cut is still happening. Hence, I vote for the status quo on both the repo rate and the stance.
Statement by Shri Saugata Bhattacharya
24. The RBI Governor’s statement post the February 2026 policy review provides a comprehensive and detailed coverage and analysis of the present domestic and global macroeconomic environment and outlook. This does not bear repetition here. The following just briefly emphasises some specific trends.
25. Overall, high frequency indicators signal resilience in economic activity. Bank credit growth to non-retail sectors has gradually increased, which, together with a stable manufacturing capacity utilisation and signs of fiscal stimulus-led consumption demand boost, might be a harbinger of a gradual revival in private sector capex.
26. At the same time, the resolution projects CPI inflation to rise to the target in H1 FY27. In my assessment, not just higher inflation, the risks of further inflationary pressures are accumulating. Despite this, the good news is that household inflation expectations remained anchored.
27. The new GDP, CPI inflation and IIP series, derived from economic structures of the new base years, are pending. These incorporate revised methodologies, classifications and data sources, which are designed to better capture economic activity and price formation. These data series will provide a clearer lens on the growth – inflation balance.
28. Assessing the macro-financial environment, while awaiting the new economic data series, I think the policy rate is appropriate. Hence, I vote to keep the repo rate at 5.25%. Moreover, taking into account the continuing uncertainty on various geo-economic dimensions, it is prudent to continue with the neutral stance.
Statement by Prof. Ram Singh
29. The real GDP (FAE) is estimated to grow by 7.4 per cent in 2025-26, with private consumption and fixed investment contributing significantly to the growth. On the supply side, buoyant services sector, the resilient agricultural sector, and the revival in manufacturing activity are expected to deliver real GVA growth of 7.3 per cent. Looking ahead, real GDP growth is projected to be 6.9 per cent and 7.0 per cent for Q1:FY27 and Q2: FY27, respectively.
30. Despite the 7 per cent plus growth rate, there are no signs of overheating in the economy. CPI inflation for 2025-26 is expected to be 2.1 per cent, with Q4 at 3.2 per cent. CPI inflation for Q1and Q2 of FY27 is projected to be a tad higher at 4.0 per cent and 4.2 per cent, respectively. Filtering out the effect of increases in prices of precious metals (60-70 bps), the underlying inflation pressures are expected to remain muted.
31. Going ahead, robust domestic demand in conjunction with improved capacity utilisation is likely to attract fresh private-sector investment. Conducive financial conditions, healthy balance sheets of banks, NBFCs, and corporates, a pick-up in credit growth, and the central government capex provide resilience to the growth outlook. However, geopolitical tensions, uncertainty around the global trade environment, and volatility in global financial markets continue to pose downside risks to the growth outlook.
32. Overall, the growth momentum is steady, and the transmission of the 125 bps repo rate cut is still underway. So, the current policy rate seems appropriate at this time. Accordingly, I vote to keep the repo rate at 5.25 per cent.
33. An important question is: At this point, will a growth-supportive monetary policy risk fuel inflation? The extent and timing of further repo rate cuts will largely be determined by the incoming data. However, a few trends on inflation and growth fronts are noticeable for a forward-looking monetary policy.
34. On the price front, a review of the headline CPI and CPI-Core inflation data suggests that in the recent years the two have diverged quite significantly. In recent quarters, it is the headline CPI that seems to be swinging around CPI-Core inflation; the latter has been moderate and range-bound The expected rise in the headline CPI to 4.0% in Q1 and 4.2% in Q2 of FY26-27 is not entirely driven by domestic demand-pull factors; precious metals prices have also played a significant role. Further, the CPI core (excluding gold) has been well below 4 per cent over the last 8-9 quarters, even though the economy is expected to register average growth of above 7.4% over the last 5 quarters.
35. It seems the economy is entering a structural phase where a 7 per cent-plus growth rate and moderate inflation can coexist. If anything, the output gap might still be negative. As I have argued in the past, a growth rate above 7.5% appears realistic without building up price pressure. The potential growth rate seems to have inched up aided by productivity and efficiency gains from infrastructure and the technological advances in the last few years. Going forward, impact of AI is expected to be supportive on growth as well as inflation front.
36. These data points and developments suggest room for further rate cuts at an appropriate time. The forecast also suggests that the CPI core (excluding gold) will remain benign in the near term, with GDP growth around 7%. The World Bank’s CPF has projected commodity prices, except for some precious metals, to be moderate in 2026. If we use the CPI core (excluding gold and silver) as a reference point, there is a case for a growth-supportive stance, given that the economy’s fundamentals – BOP, Forex, fiscal deficit, debt-to-GDP ratio, corporate and bank balance sheets, inflation, and growth dynamics – are robust.
37. The Centre’s Fiscal Deficit for FY25-26 is on track to meet the below 4.5% of GDP target as promised in 2021-22, with a clear roadmap towards reducing debt levels to 50 per cent (+/- 1%) by 2030-31 as given in FY26-27 Budget. The CAD is expected to remain at a highly sustainable 1.1% of GDP for FY26, supported by buoyant service exports and robust private remittances. The recent announcement of trade deals with the EU and the US is expected to improve the trade and capital accounts, thereby supporting the INR.
38. In view of the reduced volatility underlying headline CPI and the dormancy of the CPI core (excluding gold and silver), it cannot be the end of the current easing cycle. Moreover, the convergence of internal price stability, robust economic fundamentals, and developments on the trade and investment fronts has created a rare window for monetary policy, in which remaining "neutral" is not appropriate at a moment that demands a proactive signal to the economy.
39. The exact quantum and timing of the further rate cut will depend on the incoming data, but a growth-supporting stance is very much consistent with a stable inflation outlook. Moreover, given the stable inflation and fiscal outlooks, a change in stance to “accommodative” will facilitate transmission of the rate cuts so far by putting downward pressure on market rates, yields for sovereign and corporate bonds and the rate spread between the two.
40. Therefore, I vote for a status quo in policy rate and am in favour of the stance being “accommodative”.
Statement by Shri Indranil Bhattacharyya
41. Notwithstanding an escalation of geo-political strife amidst intensifying tariff wars between transatlantic allies, global growth projections for 2026 has been revised upwards. At the same time, economic activity in India remained robust with various high frequency indicators bearing testimony to the continued resilience of the economy in Q3:2025-26. Accordingly, real GDP growth for 2025-26, driven by consumption and investment, is estimated to be robust at 7.4%, despite external headwinds. Even as domestic demand continues to be buoyant, the recently concluded trade deals with major trading partners have considerably improved the external outlook for the ensuing year. Besides boosting merchandise exports and strengthening the current account, these deals would support India’s labour-intensive sectors while drawing higher investments. As the fine print of various trade deals is yet to be comprehended fully, our preliminary assessment suggests an improvement in growth by about 20 basis points each in Q1 and Q2 of 2026-27 – to 6.9 per cent and 7.0 per cent, respectively.
42. Since the last MPC meeting, developments on the inflation front have been largely on expected lines barring the significant increase in prices of precious metals, viz., gold and silver. CPI headline inflation has inched up from its historical low levels although it remains below the lower tolerance threshold. While assessing headline inflation, its underlying trends as well as its likely trajectory going forward, the key elements of its major constituents would have to be delineated. While food has generally recorded deflation in six of the last seven prints, core inflation rose to 4.6 per cent in December, driven by prices in precious metals. Excluding such items, core inflation remained considerably low at 2.3 per cent indicating muted demand pressures. Going forward, food inflation is expected to pick-up and turn positive in the coming months while non-food inflation (excluding precious metals) will continue to remain benign. Supply side developments remain favourable as international commodity prices, barring metals, remain largely contained while higher rabi sowing for most crops augurs well for agricultural production. The baseline forecasts for inflation indicate that headline inflation is likely to remain around the target of 4 per cent during H1:2026-27, ruling out the risks of both undershooting the lower tolerance threshold as well as significant upward deviation from the target. The marginal upward revision in inflation forecasts essentially reflect the impact of higher prices of precious metals, and do not alter my assessment made in the December MPC meeting that the benign inflation scenario is likely to persist for long. The impending release of the new CPI series is expected to provide greater clarity on inflation developments as the weighting diagram of the new index will reflect a more updated consumption basket.
43. With headline inflation remaining well below the target throughout 2025-26 and projected at around the target in H1:2026-27, the current policy rate and the stance offers scope for remaining growth-supportive without stoking inflation. The flexible inflation targeting (FIT) framework supports maintaining the current stance as long as inflation expectations remain well-anchored. The efficacy of monetary policy transmission also depends critically on the persistence and consistency of the policy signal.2 The modest upward revision in projected inflation, till it remains within the tolerance band of the FIT framework and do not unhinge inflation expectations, does not warrant a change in the policy rate. Given that inflation, excluding precious metals, is expected to remain benign for the foreseeable future, I vote for retaining the current policy rate at its present level. I also support retaining the neutral stance as it provides the flexibility to respond appropriately to the evolving situation.
Statement by Dr. Poonam Gupta
44. The global environment remains uncertain, with economies, financial markets, and commodity markets facing varied levels of volatility and risks. Yet, from the Indian perspective, the announcement of a trade deal with the US and the signing of a major free trade agreement (FTA) with the EU have resulted in a more favorable external sector outlook.
45. In addition to receding external uncertainty, domestic growth-inflation mix continues to remain favorable for India. GDP growth is turning out to be quite robust, with the First Advance Estimates for 2025-26 at 7.4 per cent. GDP growth is supported by both private consumption and fixed investment, with their respective growth rates estimated at 7.0 per cent and 7.8 per cent in 2025-26, and momentum likely to continue in 2026-27.
46. Underpinned by the continued buoyancy of high frequency indicators, and model-based projections, preliminary estimates of growth for 2026-27 by various agencies have been revised upwards. RBI has also slightly raised the real GDP growth projections for Q1 and Q2 of 2026-27, guided by the positive near-term outlook and the trade deals.
47. Low inflation continues to be a boon. Barring precious metals, inflation in most components of the CPI basket has remained low, with full year projection for 2025-26 at 2.1 per cent. Importantly, core inflation excluding precious metals (often known as core-core) remains at 2.3 per cent (as per the latest print for December 2025) and is projected to remain benign in the next two quarters (Q1 and Q2 of 2026-27).
48. Professional forecasts and RBI’s own analyses indicate that inflation is likely to remain benign across sectors, going into 2026-27. As of now, risk to inflation from external sources (e.g. oil prices, commodity prices, or pass through of the exchange rate depreciation) is perceived to be limited as well. With capacity utilization rates steady at 74 per cent, there does not seem to be a risk of buoyant economic activity resulting in higher inflation.
49. Having already lowered the policy rate by a cumulative 125 bps in four of the last six meetings; with transmission of the last rate cut announced in December 2025 still unfolding; and as the data from the new series is awaited for both GDP and inflation, another rate cut does not seem warranted at this point in time.
50. Hence, I vote for the status quo, i.e., to keep the policy repo rate unchanged at 5.25 per cent. I also propose to retain the stance at neutral, i.e., the future course of policy action ought to be data dependent.
Statement by Shri Sanjay Malhotra
51. Despite escalating geopolitical tensions and increasing trade frictions posing huge challenges, global growth, supported by a surge in technology-related investments, conducive fiscal and monetary policies, and accommodative financial conditions, is expected to be marginally higher in 2026. Inflation outcomes may remain divergent across countries; accordingly, central banks are likely to tread dissimilar policy paths while approaching the end of their easing cycles. In the backdrop of large fiscal stimulus and geopolitical uncertainty, global investor sentiments are nervous and financial markets remain volatile.
52. In India, economic activity, driven primarily by domestic factors, remained resilient with real GDP growth in 2025-26 projected to be higher by 90 bps from 6.5 per cent in 2024-25. The outlook for the ensuing year is also expected to be strong. Domestic drivers of growth continue to be robust. Several growth-supportive measures announced in the Union Budget should further boost growth. Moreover, the recent trade agreements /deals with our major trading partners – particularly, the European Union and the United States – have also considerably brightened the external sector outlook. Accordingly, we have increased our projection of real GDP growth by 20 bps each in Q1 and Q2 of 2026-27. These trade deals will not only strengthen exports and the current account but also bring in higher investments.
53. Inflation in November and December 2025 continued to remain low and below the lower tolerance threshold. In terms of the overall trajectory, inflation, as projected earlier too, is expected to remain benign. Headline inflation is projected at 2.1 per cent for 2025-26. The revised outlook for inflation, with headline CPI inflation in Q1:2026-27 and Q2 at 4.0 per cent and 4.2 per cent, respectively, is also near the inflation target. From the perspective of monetary policy, it is germane to mention that, while we target headline inflation, the composition of inflation too is important as monetary policy has varying impact on different constituents of inflation. Excluding precious metals, inflation outlook is even lower. Precious metals contribute about 60-70 basis points to inflation. The underlying inflation continues to be low.
54. Overall, India’s macroeconomic fundamentals over the medium-term, including the external sector, remain healthy and robust. In terms of the inflation-growth dynamics, we are in a similar or slightly better position than at the last policy. Growth prospects are looking up while inflation outlook remains broadly unchanged. Moreover, several recent developments on the external front have provided room for greater optimism. Given the present state of the economy and its outlook – buoyant growth and benign inflation – I feel the current policy rate is appropriate. Accordingly, I vote for continuation of the policy repo rate at 5.25 percent and retain the neutral stance.
(Brij Raj)
Chief General Manager
------
1 Projections for full year 2026-27 will be set out in the Monetary Policy Resolution to be announced in April 2026 after incorporating the new GDP and CPI series (base 2024=100) to be released on February 27 and February 12, 2026, respectively.
2 Caballero, J. and B. Gadanecz. (2024). "Did Interest Rate Guidance in Emerging Markets Work?" Journal of International Money and Finance, Vol. 149.
