Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
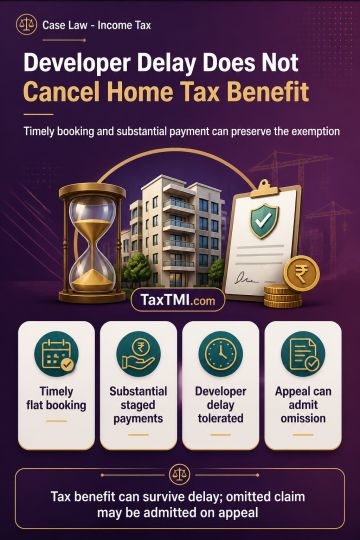
Capital-gains exemption for investment in an under-construction residential flat is discussed as available where the taxpayer books the flat promptly, substantially invests the consideration within the statutory period, and the developer's later delay causes delayed completion or registration. Allotment and staged payments are treated as construction through the developer, and a beneficial exemption is described as requiring liberal interpretation where the taxpayer has met obligations. The note also explains that an exemption claim omitted from the return may be admitted on appeal when supporting computation, booking and payment records are already on record; the restriction on fresh claims applies to the Assessing Officer, not appellate authorities.
Capital-gains exemption for investment in an under-construction residential flat is discussed as available where the taxpayer books the flat promptly, substantially invests the consideration within the statutory period, and the developer's later delay causes delayed completion or registration. Allotment and staged payments are treated as construction through the developer, and a beneficial exemption is described as requiring liberal interpretation where the taxpayer has met obligations. The note also explains that an exemption claim omitted from the return may be admitted on appeal when supporting computation, booking and payment records are already on record; the restriction on fresh claims applies to the Assessing Officer, not appellate authorities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916