Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
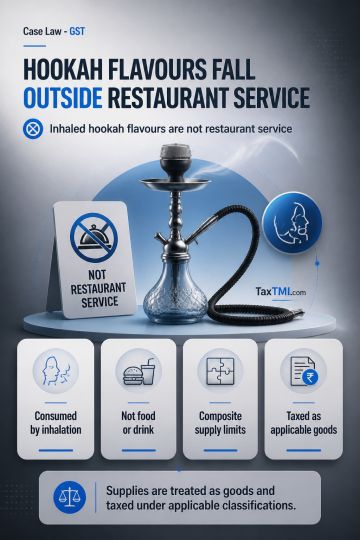
Hookah flavours supplied through a hookah apparatus in a restaurant are described as falling outside "restaurant service" under paragraph 6(b) of Schedule II to the GST Acts. The expression "food or any other article for human consumption or any drink" is analysed using common parlance, ejusdem generis and noscitur a sociis: hookah is consumed by inhalation and is not food, drink, or an article of the same class. Composite supply provisions determine tax liability only after the relevant supply category is established and cannot expand the statutory scope of restaurant service. Rate notifications likewise cannot enlarge that scope. Such supplies are treated as goods and taxed under their applicable classification and rate notifications.
Hookah flavours supplied through a hookah apparatus in a restaurant are described as falling outside "restaurant service" under paragraph 6(b) of Schedule II to the GST Acts. The expression "food or any other article for human consumption or any drink" is analysed using common parlance, ejusdem generis and noscitur a sociis: hookah is consumed by inhalation and is not food, drink, or an article of the same class. Composite supply provisions determine tax liability only after the relevant supply category is established and cannot expand the statutory scope of restaurant service. Rate notifications likewise cannot enlarge that scope. Such supplies are treated as goods and taxed under their applicable classification and rate notifications.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI