Related-party creditor exclusion bars CoC participation where lender rights show policy-making involvement, and post-CIRP assignment cannot cure ineli...
Rectification of apparent typographical errors may proceed without hearing when tax liability, input tax credit, and ruling substance remain unchanged...
Self-certified Origin Declarations under the India-UK CETA may...
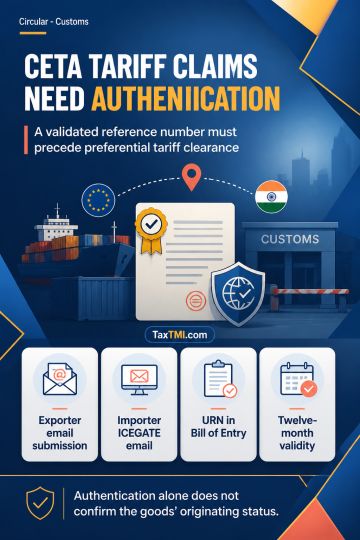
Origin Declaration authentication governs preferential tariff claims under India-UK CETA, requiring a validated reference number before import clearance.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Self-certified Origin Declarations under the India-UK CETA may support preferential tariff claims only after authentication and assignment of a Unique Reference Number. UK exporters or producers must send the declaration to the designated CBIC email address and the importer's ICEGATE-registered email; importers must quote the URN in the relevant Bill of Entry. Authentication confirms the declaration's genuineness, not the originating status of goods, which remains subject to separate verification. Declarations are valid for twelve months and generally apply to a single shipment, with specified flexibility for warehoused goods cleared through multiple ex-bond Bills of Entry. Transitional claims are permitted for eligible goods arriving or remaining under customs control when the Agreement takes effect.
Self-certified Origin Declarations under the India-UK CETA may support preferential tariff claims only after authentication and assignment of a Unique Reference Number. UK exporters or producers must send the declaration to the designated CBIC email address and the importer's ICEGATE-registered email; importers must quote the URN in the relevant Bill of Entry. Authentication confirms the declaration's genuineness, not the originating status of goods, which remains subject to separate verification. Declarations are valid for twelve months and generally apply to a single shipment, with specified flexibility for warehoused goods cleared through multiple ex-bond Bills of Entry. Transitional claims are permitted for eligible goods arriving or remaining under customs control when the Agreement takes effect.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI