Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Self-certified Origin Declarations under the India-UK CETA may...
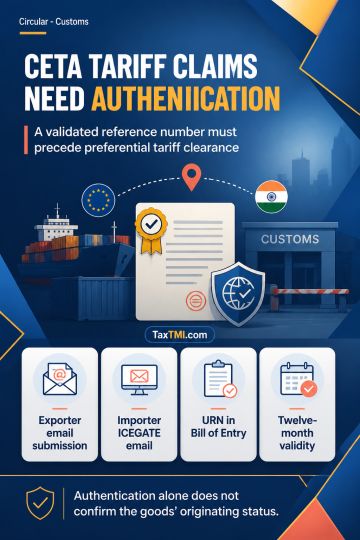
Origin Declaration authentication governs preferential tariff claims under India-UK CETA, requiring a validated reference number before import clearance.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Self-certified Origin Declarations under the India-UK CETA may support preferential tariff claims only after authentication and assignment of a Unique Reference Number. UK exporters or producers must send the declaration to the designated CBIC email address and the importer's ICEGATE-registered email; importers must quote the URN in the relevant Bill of Entry. Authentication confirms the declaration's genuineness, not the originating status of goods, which remains subject to separate verification. Declarations are valid for twelve months and generally apply to a single shipment, with specified flexibility for warehoused goods cleared through multiple ex-bond Bills of Entry. Transitional claims are permitted for eligible goods arriving or remaining under customs control when the Agreement takes effect.
Self-certified Origin Declarations under the India-UK CETA may support preferential tariff claims only after authentication and assignment of a Unique Reference Number. UK exporters or producers must send the declaration to the designated CBIC email address and the importer's ICEGATE-registered email; importers must quote the URN in the relevant Bill of Entry. Authentication confirms the declaration's genuineness, not the originating status of goods, which remains subject to separate verification. Declarations are valid for twelve months and generally apply to a single shipment, with specified flexibility for warehoused goods cleared through multiple ex-bond Bills of Entry. Transitional claims are permitted for eligible goods arriving or remaining under customs control when the Agreement takes effect.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI