Human-probability test defeats political donation deductions where banking records mask accommodation-entry fund layering rather than genuine contribu...
Electronic evidence and search statements in tax assessments require authenticity review and corroboration, while procedural manuals lack statutory fo...
Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
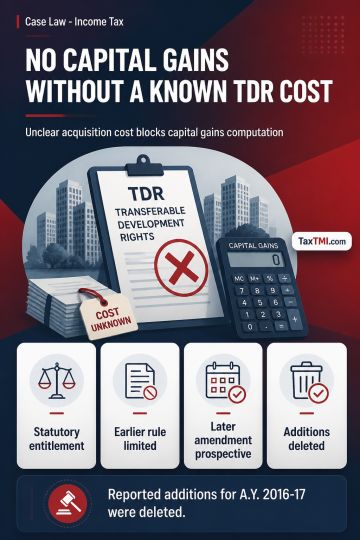
Capital gains on transfer of TDR/FSI credit may not arise where the applicable law provides no ascertainable cost of acquisition and the computation mechanism therefore fails. The charging and computation provisions operate as an integrated code, consistent with the principle in CIT v. B.C. Srinivasa Setty. TDR/DRC granted under development regulations in lieu of compensation was treated as a statutory entitlement acquired without monetary expenditure, whose value remained indeterminate until utilisation. The pre-amendment deeming provision did not cover such rights, while the later inclusion of other intangible assets and rights applied only from A.Y. 2024-25 and could not retrospectively cure the gap. The land and TDR were distinct assets, so the land's value could not be treated as the TDR's cost. The reported additions for A.Y. 2016-17 were deleted.
Capital gains on transfer of TDR/FSI credit may not arise where the applicable law provides no ascertainable cost of acquisition and the computation mechanism therefore fails. The charging and computation provisions operate as an integrated code, consistent with the principle in CIT v. B.C. Srinivasa Setty. TDR/DRC granted under development regulations in lieu of compensation was treated as a statutory entitlement acquired without monetary expenditure, whose value remained indeterminate until utilisation. The pre-amendment deeming provision did not cover such rights, while the later inclusion of other intangible assets and rights applied only from A.Y. 2024-25 and could not retrospectively cure the gap. The land and TDR were distinct assets, so the land's value could not be treated as the TDR's cost. The reported additions for A.Y. 2016-17 were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920