Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Refund of Unutilised Input Tax Credit by SEZ Units under Section 54 and Rule 89
    Case Laws Customs
    Private Bonded Warehouse Licence: Penalty-Based Disqualification under Regulation 3(2)(c)
    Refund of Accumulated Compensation Cess on Zero-Rated Supplies under Section 54 and Rule 89
    Penalty for Wrongful Availment of Input Tax Credit: The Distinction Between Sections 73 and 74
    Input Tax Credit on Resort Construction After Retrospective Substitution in Section 17(5)(d): Except...
    Shareholder Locus Standi under Section 61 in Challenges to Resolution-Plan Approval
    GSTR-2A Mismatch, Supplier Certification (of tax payment) and the Burden of Proving Input Tax Credit...
    Concessional GST on Works Contracts for Co-operative Spinning Mills: Government Entity Status and Pr...
    Case Laws Customs
    Abetment and Knowing Use of False Import Documents under Sections 112(a) and 114AA
    Subcontracted Services on Own Account and the Intermediary Exclusion under Section 2(13)
    Case Laws Customs
    Classification of Two-Ton Ductless Split Air Conditioners under Tariff Item 8415 82 10
    Case Laws Income Tax
    Transfer Pricing of Pre-Conversion Interest on Compulsorily Convertible Debentures
    Case Laws Customs
    Clubbing of Contrived Split Consignments under Rule 2(a) and Valuation of a Dismantled Motorcycle
    GST on Corporate Guarantees: Substantive Liability, Deemed Valuation and Judicial Relief
    Case Laws Income Tax
    Employee Secondment under the India-USA DTAA: Employment Rights, Reimbursements and Included Service...
    Pre-deposit Under Section 112 and Independent Compliance with Tribunal Filing Fees
    Case Laws Income Tax
    TDS on Interest Paid by Co-operative Banks to Non-Member Co-operative Societies under Section 194A(3...
    Input Tax Credit and Supplier Non-Payment: Statutory Limits on Mechanical Reversal Under Section 16(...
    Case Laws Customs
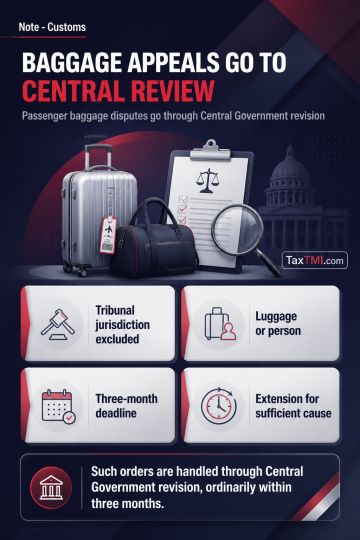
    Appellate Jurisdiction over Goods Imported as Baggage under Sections 129A and 129DD of the Customs A...
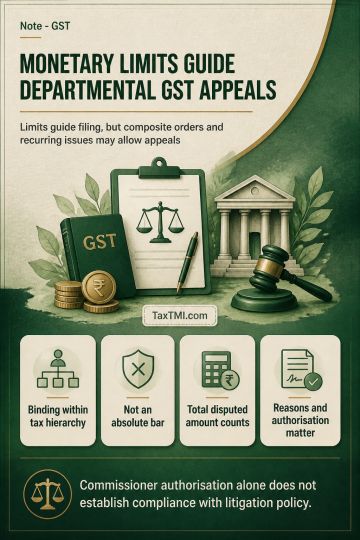
    Monetary Limits for Departmental GST Appeals under Section 120 and Circular No. 207/1/2024-GST
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
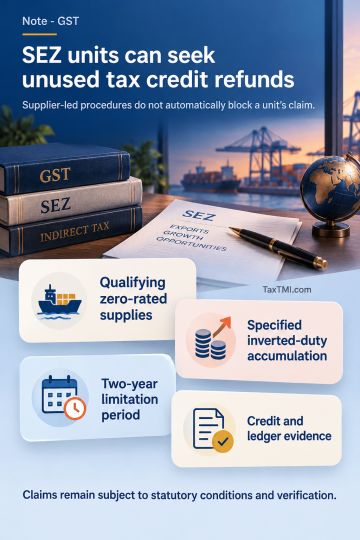
SEZ refund eligibility extends to unutilised input tax credit despite supplier-specific procedures, subject to statutory conditions and verification.
SEZ units are not categorically excluded from claiming refunds of unutilised input tax credit merely because Rule 89 prescribes a supplier-led procedure for supplies to SEZs. That procedure governs the supplier's claim for the relevant inward supply; it does not exclude a unit's own claim under the statutory refund framework. Section 54 of the CGST Act permits registered persons to claim refunds of unutilised credit subject to substantive conditions, including those governing zero-rated supplies made without payment of tax and specified inverted-duty accumulation. Refund applications must identify the applicable statutory basis, relevant date and two-year limitation period, and support the claim with evidence of qualifying supplies, credit sources, ledger balances and computation.
Case Laws Customs
Show AI Summary
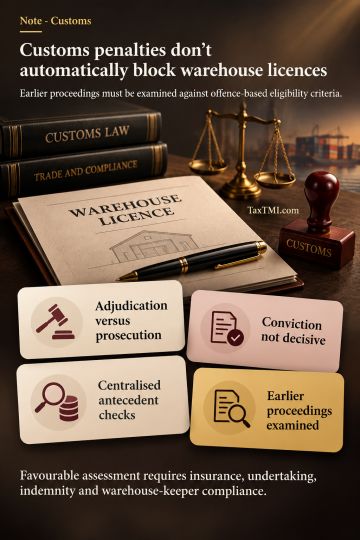
Warehouse licensing disqualification requires more than a prior customs monetary penalty and depends on offence-based eligibility criteria.
Penalisation for an offence under Regulation 3(2)(c) is not established merely by the existence of a customs monetary penalty. The legal basis and character of the earlier proceedings must be examined against the distinction between adjudicatory penalties and the offences-and-prosecutions framework. The absence of conviction alone does not resolve every disqualification ground. Antecedent verification follows a centralised process, while a favourable eligibility assessment must be followed by the insurance, undertaking, indemnity and warehouse-keeper requirements under Regulation 4.
Case Laws GST
Show AI Summary
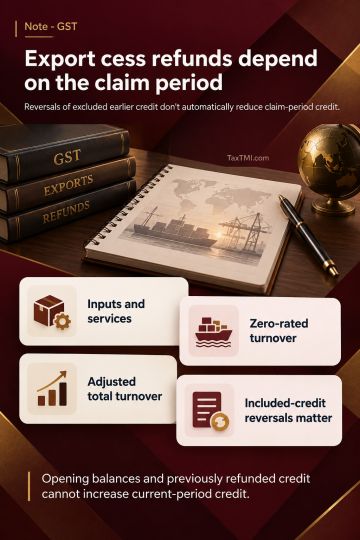
Compensation cess refunds on exports depend on period-specific credit attribution, not automatic deductions for unrelated earlier-period reversals.
Under Rule 89(4), the refund formula applies Net ITC to zero-rated turnover and adjusted total turnover. Period-specific Net ITC depends on credit availed on inputs and input services during the period for which the claim is filed. A reversal reported during that period does not automatically reduce Net ITC if it relates to residual earlier-period credit excluded from the current computation. Reversals affecting credit included in the computation remain relevant, and opening balances or previously refunded credit cannot be added to current-period Net ITC.
Case Laws GST
Show AI Summary
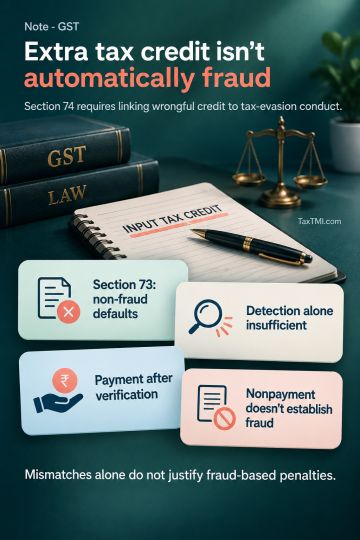
Input tax credit mismatches alone do not justify fraud-based penalties, even when excess credit is paid after verification.
Section 74 requires a factual connection between the wrongful credit and fraud, wilful misstatement or suppression of facts to evade tax; a mismatch or eligibility failure alone does not establish that connection. Section 73 covers defaults without those elements. Departmental detection, an admission of excess credit and payment after verification do not by themselves establish why the excess arose or prove the conduct necessary for Section 74. Failure to pay the pre-notice penalty cannot itself establish the fraud-related basis for Section 74.
Case Laws GST
Show AI Summary
Resort construction credit depends on immovability, own-account use, and the statutory distinction between buildings and plant and machinery.
Input tax credit on resort construction is subject to the blocked-credit restriction for goods and services received to construct immovable property on a taxable person's own account, including property used in the course or furtherance of business. The general business-use entitlement under section 16 does not displace this restriction in section 17(5)(d). The Finance Act, 2025 retrospectively substituted plant and machinery for "plant or machinery" from 1 July 2017, with the relevant provision commencing on 1 October 2025. The defined expression covers apparatus, equipment and machinery fixed to the earth by foundation or structural support and used for making outward supplies, including those foundations and supports. It excludes land, buildings and other civil structures, telecommunication towers and pipelines laid outside factory premises.
Case Laws IBC
Show AI Summary
Shareholder standing in insolvency appeals depends on legal capacity, not merely allegations of fraudulent changes to creditor-approved plans.
Individual shareholder standing to appeal against approval of a resolution plan is distinct from the legality of the plan itself. Under Section 61(1) of the Insolvency and Bankruptcy Code, 2016, an appellant must qualify as a person aggrieved. The applicable judicial interpretation restricts an appeal pursued exclusively in an individual shareholder capacity, even where equity interests are affected. Section 61(3) separately specifies permissible grounds of challenge: a plan's contravention of law and material irregularity in the resolution professional's exercise of powers are distinct grounds. Pleading either ground does not itself establish standing.
Case Laws GST
Show AI Summary
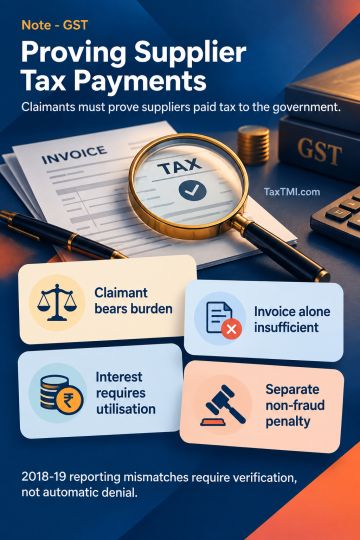
Input tax credit requires proof of supplier tax payment; reporting mismatches call for verification rather than automatic denial.
Supplier payment of tax to the Government is a condition of input tax credit eligibility under section 16(2)(c), and the claimant bears the burden of proving eligibility under section 155. Payment of the invoice and tax to the supplier, receipt of the supply and possession of an invoice do not themselves establish the supplier's remittance. For 2018-19, a GSTR-2A mismatch calls for verification and does not alone prove ineligibility. Interest under section 50(3) requires credit to have been both wrongly availed and utilised; its calculation follows Rule 88B(3). Non-fraud penalty operates under a separate statutory trigger and is not automatically excluded by the absence of fraud or utilisation.
Case Laws GST
Show AI Summary
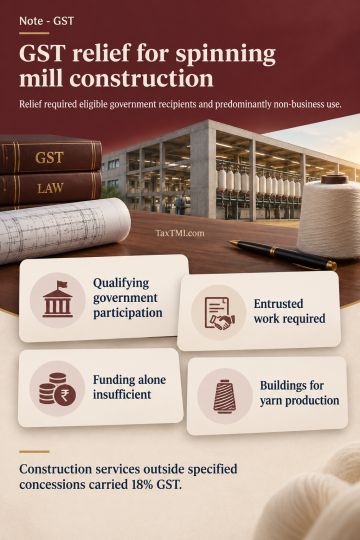
Non-business construction concessions for spinning mills require eligible recipient status and predominantly non-industrial use of the constructed buildings.
For the disputed period, the works-contract concession required both an eligible governmental recipient and structures predominantly meant for use other than commerce, industry, business or profession. Government Entity status required evidence of the recipient's constitution and qualifying governmental participation, while procurement had to relate to entrusted work. Project funding, tender approval and supervision did not by themselves establish governmental constitution or control. The spinning-mill factory buildings and allied works were intended for yarn production and related commercial activities. The residual construction-services entry carried aggregate GST of 18% for services outside the specified concessional entries.
Case Laws Customs
Show AI Summary
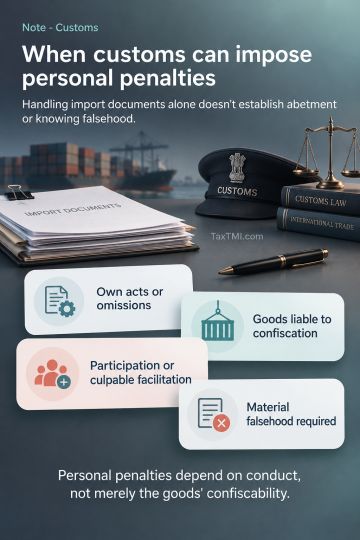
Import document handling alone does not establish customs abetment or knowing use of materially false declarations.
Personal customs penalties depend on the person's own conduct, not merely on the confiscability of imported goods. Under Section 112(a) of the Customs Act, 1962, liability may arise from a person's own act or omission rendering goods liable to confiscation or from abetment of such conduct. The direct limb can operate on a strict-liability basis where a person's own act or omission renders goods confiscable; an allegation of abetment instead requires evidence of participation or culpable facilitation. Section 114AA requires knowing or intentional making, signing or use, or causing the making, signing or use, of a declaration, statement or document that is materially false or incorrect in customs business.
Case Laws GST
Show AI Summary
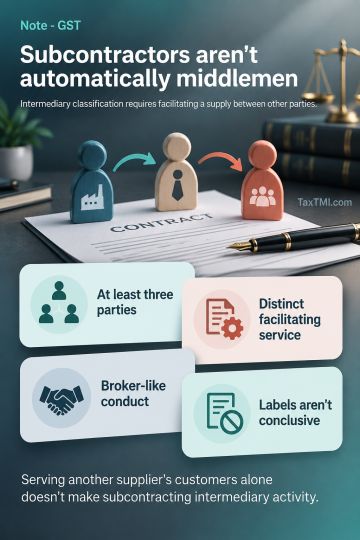
Subcontracted services performed on own account are not intermediary services merely because they support overseas recruitment and customer-facing activities.
Intermediary classification under Section 2(13) of the IGST Act distinguishes arranging or facilitating supplies between other persons from supplying services on one's own account. The intermediary framework requires at least three parties, a main supply and a distinct ancillary facilitating supply, with conduct resembling that of a broker or agent. Subcontracting the whole or part of a service is not intermediary activity merely because performance supports another supplier's business or involves its customers. Neither a bilateral agreement, contractual label nor remuneration method is conclusive.
Case Laws Customs
Show AI Summary
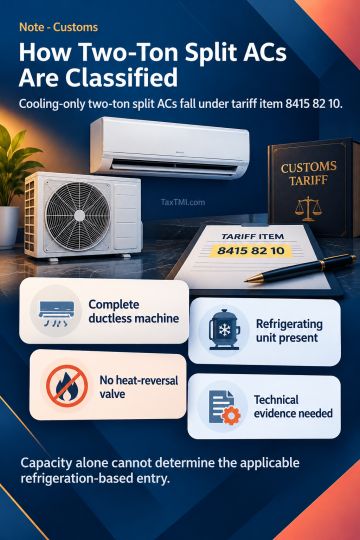
Split air conditioner classification requires capacity and refrigeration features to be assessed against the applicable tariff hierarchy.
Classification of ductless split air conditioners depends on the complete tariff description and the machine's technical characteristics. A complete, cooling-only, two-ton split air conditioner incorporating a refrigerating unit and lacking a heat-reversal valve falls within tariff item 8415 82 10 rather than the general split-system item 8415 10 10. Item 8415 82 10 inherits its parent subheading's refrigerating-unit requirement, while item 8415 83 10 requires the absence of such a unit. Capacity alone does not establish the applicable refrigeration-based entry. Technical evidence should establish whether the goods are a complete machine and identify their capacity and operating features.
Case Laws Income Tax
Show AI Summary
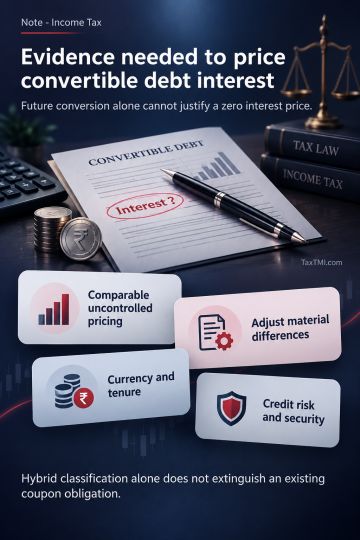
Convertible debenture interest requires evidence-based pricing before conversion; future equity conversion alone cannot establish a nil arm's length price.
Pre-conversion interest on compulsorily convertible debentures (CCDs) issued to a non-resident associated enterprise requires arm's length pricing. Compulsory future conversion and hybrid classification do not, by themselves, establish a nil price or extinguish an existing coupon obligation. Rule 10AB's Other Method requires a price charged, paid or expected in comparable uncontrolled circumstances, with reasonably accurate adjustments for material differences under Rule 10B. Currency, benchmark date, tenure, credit risk, security, non-redemption and conversion benefits affect comparability; a conventional bank lending rate is not automatically comparable to a long-tenor CCD.
Case Laws Customs
Show AI Summary
Split motorcycle consignments require evidence of deliberate fragmentation for composite classification, with valuation assessed independently of classification.
Clubbing of split consignments for customs classification depends on proof that apparently separate imports form one deliberately fragmented transaction, not merely on the possibility of assembly. Rule 2(a) extends a tariff heading to an incomplete article possessing the essential character of the complete article and also covers a complete article presented disassembled. A change of tariff heading alone does not establish that the transaction value is inaccurate; substantive misdescription of the goods requires separate evidentiary consideration. Replacement value must follow the prescribed sequence of methods.
Case Laws GST
Show AI Summary
Corporate guarantee taxation depends on distinguishing taxable supply from valuation, particularly for unpaid support between related businesses.
GST on corporate guarantees requires separate consideration of whether a taxable supply exists and how that supply is valued. Section 7(1)(c) and Schedule I encompass qualifying supplies between related or distinct persons without consideration when made in the course or furtherance of business. Rule 28(2) deems the value of a guarantee furnished to a banking company or financial institution for a related recipient in India to be one per cent of the guaranteed amount per annum or actual consideration, whichever is higher. Where the recipient is eligible for full input tax credit, the proviso treats the value declared in the invoice as the value of the supply.
Case Laws Income Tax
Show AI Summary
Employee secondment taxation depends on employment rights, service consideration and demonstrable transfer of technical capability to host entities.
Local operational control and a stated suspension of foreign employment do not, by themselves, resolve whether underlying foreign employment rights survive. Under Article 12(4)(b) of the India-USA DTAA, technical or consultancy services must make technical knowledge, experience, skill, know-how or processes available, or involve development and transfer of a technical plan or design. Under the knowledge-transfer limb, the recipient must acquire a capability it can use independently; the mere application of expertise or presence of qualified personnel is insufficient. Recovery at actual cost and absence of markup do not, by themselves, establish that a foreign enterprise's receipt is non-taxable.
Case Laws GST
Show AI Summary
GST appellate pre-deposits may be satisfied by verified earlier payments after demand reduction, but filing fees remain independently payable.
When the first appellate authority substantially reduces the disputed tax demand, an earlier deposit may be sufficient to satisfy the Tribunal-stage requirement, subject to verification. Sufficiency depends on the reduced liability, the applicable appellate requirements and the amount actually deposited; a first appellate payment does not automatically eliminate the additional obligation. Tribunal filing fees under Section 112(7) operate independently of pre-deposit. Where a fee shortfall and earlier deposit require verification, proof of fee payment and verification of the deposit precede consideration of admission.
Case Laws Income Tax
Show AI Summary
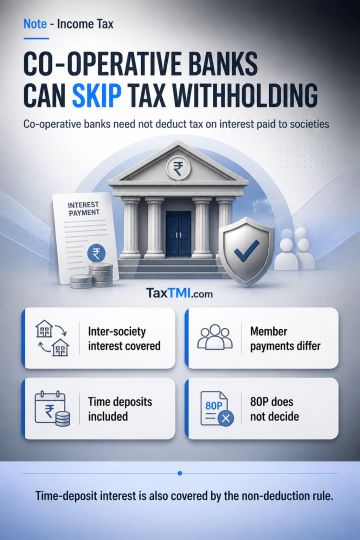
Inter-co-operative society interest exemption preserves non-deduction by co-operative banks when depositors are co-operative societies under the statutory withholding framework.
Section 194A(3)(v) separately addresses interest paid by a co-operative bank to a member and interest paid by a co-operative society to another co-operative society. The exclusion of co-operative banks is confined to the member-payment limb; a co-operative bank remains a co-operative society for the inter-co-operative society limb. Paragraph 42.7 of Circular No. 19/2015 preserves non-deduction, including time-deposit interest, where the depositor is a co-operative society. Section 80P does not determine this withholding obligation.
Case Laws GST
Show AI Summary
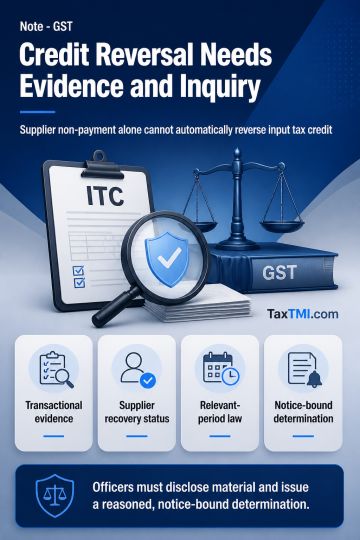
Input tax credit reversal requires evidence linking supplier non-payment to recipient ineligibility and a reasoned statutory inquiry.
Input tax credit under Section 16(2)(c) remains conditional on actual payment of tax to Government, but supplier non-payment or retrospective cancellation cannot by itself justify reversal. The recipient must establish eligibility through transactional evidence, while the proper officer must investigate the particular supply, disclose supplier-default and recovery material, apply the law applicable to the relevant period, and issue a reasoned, notice-bound determination. Supplier recovery status and protection against duplicate collection are material considerations.
Case Laws Customs
Show AI Summary
Baggage-related customs appeals proceed through statutory revision when the jurisdictional exclusion applies to passenger imports.
The first proviso to section 129A(1) excludes Appellate Tribunal jurisdiction over an order under section 128A relating to goods imported or exported as baggage. The decisive issue is the order's connection with baggage, not disputes concerning confiscation, declaration, duty, personal effects, concealment, concession, or penalty. Articles carried by an international passenger in luggage or on the person may constitute baggage. Section 129DD provides revision before the Central Government, ordinarily within three months, subject to a further period on sufficient cause.
Case Laws GST
Show AI Summary
Departmental GST appeal monetary limits regulate officers, while composite orders and proven recurring issues may permit appeals.
Sections 120 and 168 of the Central Goods and Services Tax Act, 2017 make monetary-limit directions binding within the Central tax hierarchy, while they regulate the executive decision to file rather than create an inflexible jurisdictional bar before the Tribunal. In a composite order disposing of multiple appeals or demand notices, the relevant amount is the total disputed tax, interest, penalty or late fee, as applicable. The recurring or interpretative-issue exclusion requires a reasoned, case-specific basis, and Commissioner authorisation does not itself establish compliance with the litigation policy.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

E-Way Bills, Expiry and Intent (Mens Rea): Reassessing GST Penalties: Reading Sections 129 and 130 in Tandem

20 November, 2025

Contents
Acts
Plus +
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Deciphering Legal Judgments: A Comprehensive Analysis of Judgment

Reported as:

2025 (10) TMI 545 - ALLAHABAD HIGH COURT

2024 (1) TMI 1150 - ALLAHABAD HIGH COURT

2024 (2) TMI 363 - ALLAHABAD HIGH COURT

2022 (1) TMI 954 - SC ORDER

Introduction

The set of decisions under consideration - one from the Supreme Court of India (2022) and three from the Allahabad High Court (2024 and 2025) - lie at the intersection of GST compliance and constitutional constraints on tax administration. Each case arises from detention of goods and imposition of tax and penalty u/s 129 of the CGST/State GST regime on account of defects or lapses in e-way bills (non-generation, partial generation, or expiry). Collectively, these judgments develop a coherent doctrinal stance that:

  • technical or procedural lapses in e-way bills do not, by themselves, justify detention and penalty; and
  • an intention to evade tax (mens rea) is a necessary precondition for invoking the drastic consequences of Section 129 and related provisions.

The decisions thus have significance beyond individual fact situations. They shape the contours of permissible enforcement under GST, reinforce the proportionality and reasonableness requirements of Article 14, and signal judicial intolerance of abusive or mechanical invocation of Section 129 where the underlying tax is not in jeopardy.

Key Legal Issues

1. Whether expiry or non-availability of an e-way bill, by itself, justifies inference of tax evasion and initiation of proceedings u/s 129

Across all four decisions, the central issue is whether the mere fact of an e-way bill having expired, or not being generated/updated in time, is enough to treat the movement of goods as being "in contravention" of the GST law so as to invite detention, seizure and penalty u/s 129.

This is essentially an issue of legal interpretation of Sections 68, 129 and 130 of the CGST/State GST Acts, read with Rule 138 on e-way bills - and of their interrelationship. The courts treat it as both a substantive and constitutional question, as it bears on arbitrariness and abuse of power under Article 14.

2. Whether intention to evade tax is a sine qua non for invoking Section 129

The Allahabad High Court, particularly in the 2024 decisions, frames the core doctrinal issue as whether proceedings u/s 129 (detention, seizure and penalty) can be sustained in the absence of established mens rea, or whether in such circumstances, at most a minor/technical infraction provision (e.g. Section 122) may be attracted.

This is a question of application of precedent and statutory construction, with repeated reliance on earlier High Court judgments and the Supreme Court's approach in the 2022 decision.

3. Scope of judicial review and the writ of certiorari in GST detention/penalty cases

In Falguni Steels [2024 (1) TMI 1150 - ALLAHABAD HIGH COURT], the High Court also addresses the breadth of supervisory jurisdiction under Article 226 to correct "errors of jurisdiction" and patent errors of law apparent on the face of the record, when authorities impose penalties without establishing intent to evade tax.

This is a procedural and constitutional question relating to standards for interference with administrative/quasi-judicial tax orders.

Detailed Issue-wise Analysis

1. Expiry / technical lapse in e-way bill and presumption of evasion

The 2025 Allahabad High Court decision (involving a vehicle tracking service provider transporting GPS devices to a government entity) concerned goods that were accompanied by a genuine tax invoice and a valid e-way bill; during transit, the vehicle broke down, goods were shifted to another vehicle, and the e-way bill expired before delivery. New e-way bills were generated before the Section 129(3) order was passed. The sole ground for interception was expiry of the e-way bill.

The State contended that:

  • an e-way bill must be valid at the time of interception;
  • a fresh e-way bill should have been generated before resuming movement after the breakdown; and
  • the lapse itself justified presumption that, but for interception, tax evasion would have occurred.

The Court rejected this approach, emphasizing:

  • the genuineness of the transaction (contract with a Government of India department for vehicle tracking devices);
  • non-dispute regarding invoices and original e-way bill; and
  • non-dispute that a mechanical breakdown delayed movement and that fresh e-way bills were in fact generated before the penalty order.

Referring to a "catena of judgments" (including those subsequently reproduced in Falguni Steels and Globe Panel), the Court reiterated its settled view that:

"expiry of e-way bill will not attribute to intention to evade payment of tax."

This view is squarely aligned with the Supreme Court's 2022 decision in Assistant Commissioner (ST) v. Satyam Shivam Papers. There, the e-way bill had expired one day before, but the delay was demonstrably due to traffic blockage caused by anti-CAA/NRC agitation. The Telangana High Court had found:

  • the explanation about traffic blockage and holidays (Saturday, Sunday) was not disputed;
  • the detaining officer offered no reasoned basis to infer evasion "merely because the e-way bill has expired"; and
  • there was no evidence of any attempt to divert or sell the goods elsewhere.

The Supreme Court endorsed this reasoning "meticulously examined" by the High Court, and characterized the inference of evasion from mere expiry as "baseless" and the conduct of the officer as a "blatant abuse of power". It held that:

  • no question of law arose on these facts; and
  • non-extension of the e-way bill within the prescribed time could not, without more, support a presumption of intent to evade tax.

The 2024 decisions of the Allahabad High Court further consolidated this line:

  • In Falguni Steels [2024 (1) TMI 1150 - ALLAHABAD HIGH COURT], the e-way bills were generated slightly late due to alleged technical glitches and movement restrictions during the Kumbh Mela. Tax invoices clearly mentioned all particulars including vehicle number, taxes had already been charged by a public sector manufacturer, and no discrepancy in quantity, description or parties was found. The Court held that:
    • mere delay/non-availability of an e-way bill at the exact moment of interception, where later produced before passing of a Section 129(3) order and coupled with complete, consistent commercial documentation, cannot justify penalty;
    • the authorities erred in ignoring the later-generated e-way bills and the explanation for delay; and
    • no intention to evade tax could be inferred on such facts.
  • In Globe Panel [2024 (2) TMI 363 - ALLAHABAD HIGH COURT], only one of two e-way bills had expired; invoices and e-way bills otherwise matched the goods, consignor and consignee were undisputed, and the transporter produced evidence of vehicle breakdown and fastag movement. The Court held that a technical violation (an expired e-way bill not renewed in time) without any material indicating repeated misuse or diversion cannot, by itself, sustain penalty.

Thus, all four decisions converge on the principle that the e-way bill mechanism is a compliance tool, not a self-standing basis to presume evasion absent corroborative indicia of tax risk.

2. Requirement of mens rea / intention to evade tax u/ss 129 and 130

The Allahabad High Court's 2024 judgments undertake the most systematic doctrinal work on this question.

In Falguni Steels, the Court synthesizes earlier case law (including VSL Alloys, Shyam Sel and Power, J.K. Cement, Roli Enterprises, Modern Traders and Axpress Logistics) to derive the following propositions:

  1. Sections 129 and 130 of the CGST/UPGST Acts are to be read together, because both deal with consequences of movement in contravention of the law, and confiscation/penalty u/s 130 expressly hinges on "intention to evade tax".
  2. A purposive reading of these provisions makes "intent to evade tax" a sine qua non for initiation of proceedings u/s 129 as well, not merely for Section 130.
  3. Where the facts do not disclose such intention, but reveal only a minor technical breach (e.g. incomplete e-way bill, delayed generation, expiry during transit), the proper course - if at all - is recourse to Section 122 (minor penal infractions) rather than the more draconian Section 129.

The Court quotes earlier authority to emphasize that:

  • a mere "small technical fault" in carrying e-way bills, with no discrepancy in the accompanying documents and no indication of diversion, cannot justify penalty; and
  • the essence of penal imposition is intrinsically linked to mens rea - particularly where serious economic consequences and seizure/detention powers are involved.

This reasoning is expressly carried over in Globe Panel, where the Court observes that previous decisions (Hindustan Herbal Cosmetics and Falguni Steels) have already settled that mens rea to evade tax is "essential for imposition of penalty" u/s 129(3). The Court notes that:

"Indubitably, there is a technical violation that has been committed by the petitioner. However, the authorities have not been able to indicate in any manner ... an intention to evade tax... such a technical violation by itself without any intention to evade tax cannot lead to imposition of penalty u/s 129(3)."

The 2025 Allahabad decision (Trimble) does not elaborate the doctrine afresh but simply applies the already crystallized rule: expiry of an e-way bill, in the face of undisputed genuineness of transaction and timely generation of a fresh e-way bill before the penalty order, cannot be treated as evidence of evasion.

The Supreme Court's [2022 (1) TMI 954 - SC ORDER] approach in Satyam Shivam Papers is consistent in substance, though it does not articulate the "Sections 129 and 130 must be read together" formula. It endorses the High Court's rejection of any presumption of evasion from mere expiry, highlights absence of any attempt to sell/divert goods, and treats the officer's conduct as arbitrary and abusive. While framed as a fact-based dismissal of a misconceived SLP, the decision reinforces the requirement that material indicative of evasion - beyond mere procedural lapse - must exist to justify Section 129 action.

3. Judicial review and writ of certiorari in GST detention/penalty matters

Falguni Steels devotes considerable analysis to the availability and scope of a writ of certiorari to quash orders u/s 129(3) and appellate orders u/s 107. The Court holds that both the primary and appellate authorities:

  • failed to consider material explanations (portal glitches, administrative barriers during Kumbh Mela, timely subsequent generation of e-way bills);
  • failed to record any finding on intention to evade tax; and
  • proceeded on an incorrect legal assumption that the CGST/UPGST Acts do not require any showing of intent to evade tax, unlike the earlier VAT regime.

These, the Court characterizes as "errors of jurisdiction" and errors of law apparent on the face of the record, warranting issuance of a writ of certiorari. It relies on leading Supreme Court decisions on certiorari - notably Central Council for Research in Ayurvedic Sciences v. Bikartan Das and the Constitution Bench in Nagendra Nath Bora - to restate that:

  • certiorari is a supervisory, not appellate, remedy, but lies where an inferior tribunal exceeds its jurisdiction or fails to act in accordance with the essential requirements of law; and
  • patent legal errors going to jurisdiction or the legal standard applied are corrigible under Article 226 even absent a statutory appeal on merits.

By framing the misapplication of Section 129 (without considering mens rea) as a jurisdictional defect, the Court underscores that GST authorities cannot insulate such orders behind the facade of "factual appreciation"; incorrect understanding of the legal preconditions for penalty is itself reviewable.

Key Holdings and Reasoning

Ratio decidendi

Taken together, the core operative principles emerging from these decisions can be summarized as:

  1. Expiry or non-generation of an e-way bill, per se, does not establish intent to evade tax. Absent additional material showing diversion, mis-declaration, fictitious parties, or other indicia of evasion, penal proceedings u/s 129 cannot be sustained.
  2. Mens rea is a necessary ingredient for Section 129 / 130 proceedings. Section 130's explicit requirement of "intention to evade tax", read purposively with Section 129, makes intent to evade tax a sine qua non for detention, seizure and penalty u/s 129 as well. Technical lapses alone may at most fall u/s 122.
  3. Presence of genuine commercial documentation negates presumption of evasion. Where goods are accompanied by proper tax invoices, correct particulars (including vehicle details) and, even if belatedly, duly generated e-way bills, and where taxes have been duly charged and no physical discrepancy is found, the presumption must be against evasion.
  4. Authorities must give reasoned findings on intent; mere recitation of contravention is insufficient. Penalty orders must explicitly engage with explanations offered and record some material basis to infer intent to evade tax. Failure to do so is arbitrary and legally unsustainable.
  5. Misapplication of Section 129 without considering mens rea is a jurisdictional error reviewable in certiorari. Such misapplication can be corrected under Article 226 as an error of law apparent on the face of the record and as an excess of jurisdiction.
  6. Abusive or mala fide use of Section 129 invites judicial censure and costs. As in Satyam Shivam Papers, where goods were stored in the officer's relative's house and penalty was imposed on a baseless theory of evasion, courts may not only set aside orders but also impose personal/departmental costs.

Obiter dicta and broader observations

Several broader observations, although not strictly necessary for disposal, reinforce the jurisprudential direction:

  • In Falguni Steels, the Court elaborates at length on the philosophy of tax penalties, emphasizing that taxation statutes are not meant to punish inadvertent or technical errors and that proportionality and mens rea are inherent in legitimate enforcement.
  • The Court in Falguni Steels and Globe Panel explicitly rejects the notion that the shift from VAT to GST removed the requirement of intent for serious penalty provisions, terming such a view "palpably erroneous".
  • The Supreme Court in Satyam Shivam Papers stresses that where State action (e.g., traffic blockage during agitation) itself causes delay, the State cannot then rely on the resulting expiry of the e-way bill to penalize taxpayers.

Relationship with earlier precedents

The decisions heavily cross-refer and build upon one another:

  • The 2025 Allahabad decision explicitly follows earlier Allahabad rulings such as Falguni Steels and Globe Panel, and relies on the Supreme Court's approval in Satyam Shivam Papers.
  • Falguni Steels consolidates and affirms earlier Allahabad decisions including VSL Alloys, Shyam Sel & Power, J.K. Cement, Modern Traders, Axpress Logistics, and Hindustan Herbal Cosmetics, and distinguishes any approach that would allow penalty without mens rea.
  • Globe Panel then expressly applies the ratio of Falguni Steels and Hindustan Herbal Cosmetics to a pure "expired e-way bill" fact situation.

At the apex level, the Supreme Court's refusal to interfere in Satyam Shivam Papers, coupled with enhancement of costs, effectively gives national-level endorsement to the High Courts' scepticism toward mechanical reliance on e-way-bill lapses as proof of evasion.

Conclusion

The jurisprudence reflected in these decisions significantly recalibrates the balance between GST enforcement and taxpayer rights. On the one hand, the statutory framework mandates compliance with e-way bill procedures; on the other, the courts insist that these procedures cannot become a self-standing basis for punitive action divorced from underlying tax risk and intent.

Practically, these rulings mean that:

  • transporters and dealers who can demonstrate genuine transactions, complete invoices, payment of tax, and plausible reasons for e-way bill lapses (technical glitches, breakdowns, movement restrictions, etc.) possess a strong defence against Section 129 penalties;
  • officers must carefully document material suggesting diversion or evasion and cannot rely on "expiry" or "non-generation" simpliciter; and
  • mechanical or mala fide use of detention and penalty powers exposes the department to quashing of orders, refund directions, and even personal cost recovery.

Going forward, these decisions invite further doctrinal refinement in at least two directions: first, clearer administrative guidelines distinguishing "technical" from "substantive" violations, with an appropriate mapping to Sections 122, 129 and 130; and second, internal accountability mechanisms to curb overreach and ensure that Section 129 is invoked only where a demonstrable risk of evasion exists. If such reforms are undertaken in light of these precedents, GST administration would be more consistent with constitutional guarantees of fairness, proportionality and non-arbitrariness, while still preserving the State's ability to combat genuine tax evasion.


Full Text:

2025 (10) TMI 545 - ALLAHABAD HIGH COURT

2024 (1) TMI 1150 - ALLAHABAD HIGH COURT

2024 (2) TMI 363 - ALLAHABAD HIGH COURT

2022 (1) TMI 954 - SC ORDER

Topics

Acts Income Tax