Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
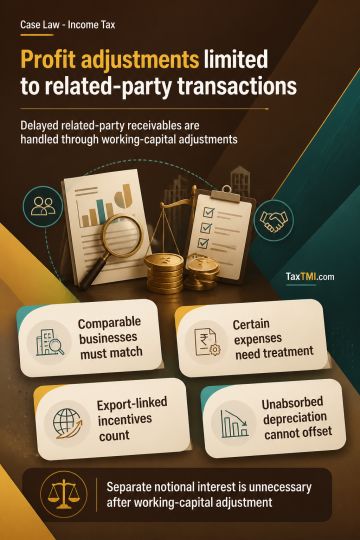
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Assessee received funds from four parties, which were not considered by the Assessing Officer (AO) during assessment proceedings u/s 147 read with Section 144. The Principal Commissioner of Income Tax (PCIT) cancelled the assessment framed by AO and directed to frame assessment afresh after verifying the funds received. However, the Appellate Tribunal held that the assessment framed by AO cannot be considered erroneous or prejudicial to the revenue's interest as the AO was unaware of these funds during assessment proceedings. Invoking Section 263 by PCIT is invalid as per the Supreme Court's judgment in Malabar Industries Limited case, which mandates that for invoking Section 263, the assessment order must be erroneous and prejudicial to revenue's interest. Assessee's appeal allowed.
Assessee received funds from four parties, which were not considered by the Assessing Officer (AO) during assessment proceedings u/s 147 read with Section 144. The Principal Commissioner of Income Tax (PCIT) cancelled the assessment framed by AO and directed to frame assessment afresh after verifying the funds received. However, the Appellate Tribunal held that the assessment framed by AO cannot be considered erroneous or prejudicial to the revenue's interest as the AO was unaware of these funds during assessment proceedings. Invoking Section 263 by PCIT is invalid as per the Supreme Court's judgment in Malabar Industries Limited case, which mandates that for invoking Section 263, the assessment order must be erroneous and prejudicial to revenue's interest. Assessee's appeal allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899