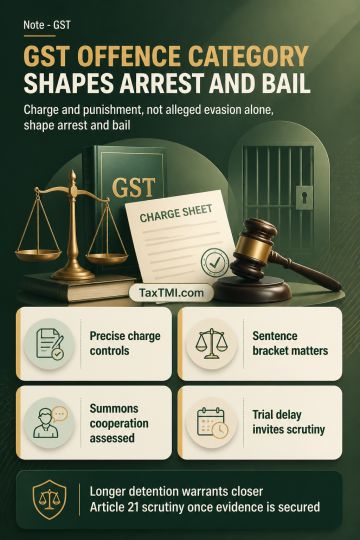
GST offence classification determines whether arrest and bail restrictions apply, while continued custody requires an individualised necessity assessm...
Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Page of 4921
Press 'Enter' after typing page number.
341 to 360 of 98414 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
The issue pertains to the disallowance of excess Minimum Alternate Tax (MAT) credit u/s 115JAA and whether the amount of surcharge and education cess should be reduced from the tax determined on total income while considering the MAT credit available from earlier years. The Tribunal found that the assessee had furnished details of MAT credit available and utilized in different assessment years. It noted that the assessee had utilized the total MAT credit. The Tribunal followed the decision in Consolidated Securities Ltd., wherein it was held that the amount of MAT credit available from earlier years, inclusive of surcharge and education cess, should be reduced from the tax determined on total income of the current year after adding surcharge and education cess. Consequently, the Tribunal affirmed the order of the Commissioner of Income Tax (Appeals) and dismissed the revenue's appeal.
The issue pertains to the disallowance of excess Minimum Alternate Tax (MAT) credit u/s 115JAA and whether the amount of surcharge and education cess should be reduced from the tax determined on total income while considering the MAT credit available from earlier years. The Tribunal found that the assessee had furnished details of MAT credit available and utilized in different assessment years. It noted that the assessee had utilized the total MAT credit. The Tribunal followed the decision in Consolidated Securities Ltd., wherein it was held that the amount of MAT credit available from earlier years, inclusive of surcharge and education cess, should be reduced from the tax determined on total income of the current year after adding surcharge and education cess. Consequently, the Tribunal affirmed the order of the Commissioner of Income Tax (Appeals) and dismissed the revenue's appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921