Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
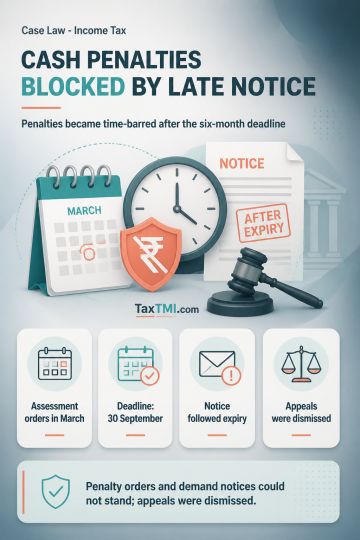
Limitation for penalties arising from alleged cash receipts contrary to section 269ST remains subject to differing views on when the limitation period under section 275(1)(c) begins. Under either approach, penalty proceedings under section 271DA were time-barred because the assessment orders were passed in March 2024, the six-month period ended on 30 September 2024, and the show-cause notice was issued later. The penalty orders and consequential demand notices were therefore unsustainable, and the appeals were dismissed.
Limitation for penalties arising from alleged cash receipts contrary to section 269ST remains subject to differing views on when the limitation period under section 275(1)(c) begins. Under either approach, penalty proceedings under section 271DA were time-barred because the assessment orders were passed in March 2024, the six-month period ended on 30 September 2024, and the show-cause notice was issued later. The penalty orders and consequential demand notices were therefore unsustainable, and the appeals were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916