Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
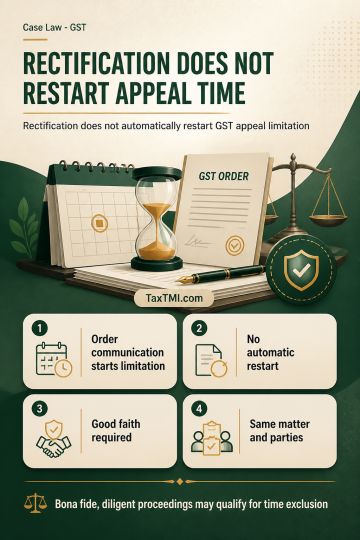
For GST appeals, limitation under Section 107 runs from communication of the specific order challenged and is not automatically suspended or restarted by a rectification petition. Statutory condonation limits cannot be enlarged through principles underlying Section 5 of the Limitation Act. Principles underlying Section 14 may nevertheless permit exclusion of time spent pursuing a rectification petition where it concerns the same parties and matter and was pursued with due diligence and good faith. Good faith requires an arguable rectification basis, not a meritless attempt to introduce material absent from the original proceedings. Where exclusion is established, the appeal period is computed after excluding the rectification period; otherwise, reconsideration may be subject to agreed remittance conditions.
For GST appeals, limitation under Section 107 runs from communication of the specific order challenged and is not automatically suspended or restarted by a rectification petition. Statutory condonation limits cannot be enlarged through principles underlying Section 5 of the Limitation Act. Principles underlying Section 14 may nevertheless permit exclusion of time spent pursuing a rectification petition where it concerns the same parties and matter and was pursued with due diligence and good faith. Good faith requires an arguable rectification basis, not a meritless attempt to introduce material absent from the original proceedings. Where exclusion is established, the appeal period is computed after excluding the rectification period; otherwise, reconsideration may be subject to agreed remittance conditions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888