Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
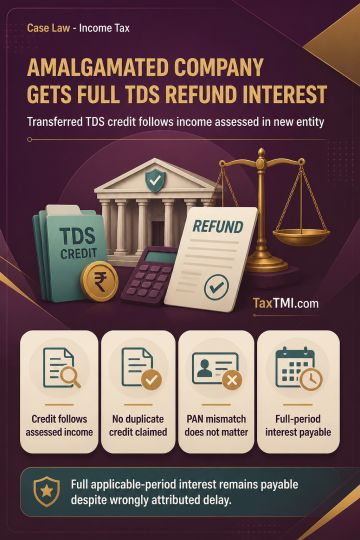
TDS credit transferred following amalgamation must be granted to the amalgamated entity where the related income is substantively assessed in its hands and the amalgamating entity has not claimed that credit. Section 199 read with Rule 37BA applies despite the TDS appearing under the amalgamating entity's PAN. Where the credit was claimed in the original and revised returns and subsequently allowed, refund interest under section 244A(1) is payable for the full applicable period. Delay cannot be excluded under section 244A(2) merely because the Assessing Officer wrongly attributes default to the taxpayer.
TDS credit transferred following amalgamation must be granted to the amalgamated entity where the related income is substantively assessed in its hands and the amalgamating entity has not claimed that credit. Section 199 read with Rule 37BA applies despite the TDS appearing under the amalgamating entity's PAN. Where the credit was claimed in the original and revised returns and subsequently allowed, refund interest under section 244A(1) is payable for the full applicable period. Delay cannot be excluded under section 244A(2) merely because the Assessing Officer wrongly attributes default to the taxpayer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886