Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Page of 4894
Press 'Enter' after typing page number.
381 to 400 of 97862 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
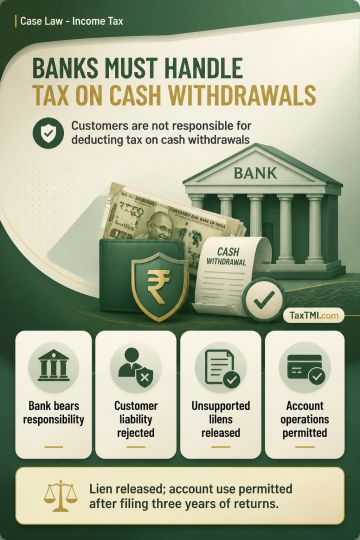
Section 194N places the obligation to deduct tax at source on the banking company making a cash payment, not on the customer withdrawing cash. Failure to deduct attracts the statutory consequence under section 271C against the person responsible for deduction. A bank cannot impose a lien on a customer's current account for an alleged TDS liability without statutory authority or a direction from the income-tax authorities. The lien was directed to be released and account operations permitted after the customer furnished income-tax returns for the relevant three consecutive years, without limiting lawful action by tax authorities.
Section 194N places the obligation to deduct tax at source on the banking company making a cash payment, not on the customer withdrawing cash. Failure to deduct attracts the statutory consequence under section 271C against the person responsible for deduction. A bank cannot impose a lien on a customer's current account for an alleged TDS liability without statutory authority or a direction from the income-tax authorities. The lien was directed to be released and account operations permitted after the customer furnished income-tax returns for the relevant three consecutive years, without limiting lawful action by tax authorities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894