Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
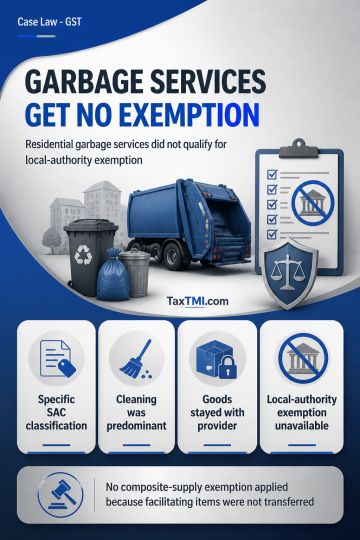
Residential waste collection classification under SAC 999423 defeats composite-supply exemption where facilitating goods are not transferred to the local authority.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Residential housing-unit sweeping, cleaning, collection, segregation and storage of garbage are classified as general waste collection services under SAC 999423, which is more specific than the residuary category for other services not elsewhere specified. The arrangement is not eligible for the exemption available for composite supplies of goods and services to a local authority in relation to municipal functions. Cleaning and garbage removal formed the predominant supply, while welfare kits, bins, tools and consumables merely facilitated service performance and were procured at the service provider's cost. As ownership or possession of those items was not transferred to the local authority, no supply of goods occurred and the composite-supply condition was not met.
Residential housing-unit sweeping, cleaning, collection, segregation and storage of garbage are classified as general waste collection services under SAC 999423, which is more specific than the residuary category for other services not elsewhere specified. The arrangement is not eligible for the exemption available for composite supplies of goods and services to a local authority in relation to municipal functions. Cleaning and garbage removal formed the predominant supply, while welfare kits, bins, tools and consumables merely facilitated service performance and were procured at the service provider's cost. As ownership or possession of those items was not transferred to the local authority, no supply of goods occurred and the composite-supply condition was not met.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894