Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
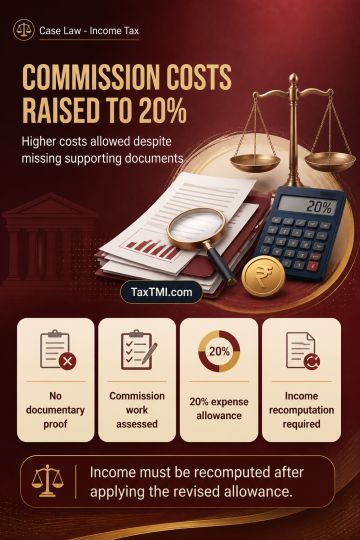
Unsupported claims for expenditure against commission income cannot be accepted solely on the taxpayer's assertions. The text explains that, despite the absence of documentary evidence, the nature of commission activities, the taxpayer's age, cash withdrawals and the scale of commission receipts indicated that substantial expenditure on assistance, administrative needs and incidental items was inevitable. It considers an estimate of 10 per cent of gross commission receipts inadequate and prescribes allowance of expenditure at 20 per cent, requiring consequential recomputation of income.
Unsupported claims for expenditure against commission income cannot be accepted solely on the taxpayer's assertions. The text explains that, despite the absence of documentary evidence, the nature of commission activities, the taxpayer's age, cash withdrawals and the scale of commission receipts indicated that substantial expenditure on assistance, administrative needs and incidental items was inevitable. It considers an estimate of 10 per cent of gross commission receipts inadequate and prescribes allowance of expenditure at 20 per cent, requiring consequential recomputation of income.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918