Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Refund of Unutilised Input Tax Credit by SEZ Units under Section 54 and Rule 89
    Case Laws Customs
    Private Bonded Warehouse Licence: Penalty-Based Disqualification under Regulation 3(2)(c)
    Refund of Accumulated Compensation Cess on Zero-Rated Supplies under Section 54 and Rule 89
    Penalty for Wrongful Availment of Input Tax Credit: The Distinction Between Sections 73 and 74
    Input Tax Credit on Resort Construction After Retrospective Substitution in Section 17(5)(d): Except...
    Shareholder Locus Standi under Section 61 in Challenges to Resolution-Plan Approval
    GSTR-2A Mismatch, Supplier Certification (of tax payment) and the Burden of Proving Input Tax Credit...
    Concessional GST on Works Contracts for Co-operative Spinning Mills: Government Entity Status and Pr...
    Case Laws Customs
    Abetment and Knowing Use of False Import Documents under Sections 112(a) and 114AA
    Subcontracted Services on Own Account and the Intermediary Exclusion under Section 2(13)
    Case Laws Customs
    Classification of Two-Ton Ductless Split Air Conditioners under Tariff Item 8415 82 10
    Case Laws Income Tax
    Transfer Pricing of Pre-Conversion Interest on Compulsorily Convertible Debentures
    Case Laws Customs
    Clubbing of Contrived Split Consignments under Rule 2(a) and Valuation of a Dismantled Motorcycle
    GST on Corporate Guarantees: Substantive Liability, Deemed Valuation and Judicial Relief
    Case Laws Income Tax
    Employee Secondment under the India-USA DTAA: Employment Rights, Reimbursements and Included Service...
    Pre-deposit Under Section 112 and Independent Compliance with Tribunal Filing Fees
    Case Laws Income Tax
    TDS on Interest Paid by Co-operative Banks to Non-Member Co-operative Societies under Section 194A(3...
    Input Tax Credit and Supplier Non-Payment: Statutory Limits on Mechanical Reversal Under Section 16(...
    Case Laws Customs
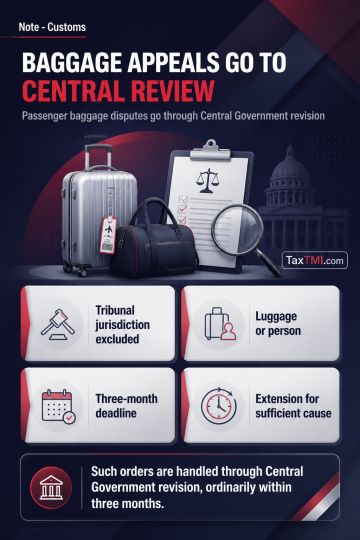
    Appellate Jurisdiction over Goods Imported as Baggage under Sections 129A and 129DD of the Customs A...
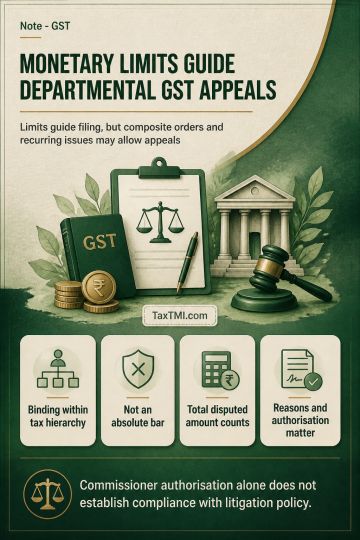
    Monetary Limits for Departmental GST Appeals under Section 120 and Circular No. 207/1/2024-GST
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
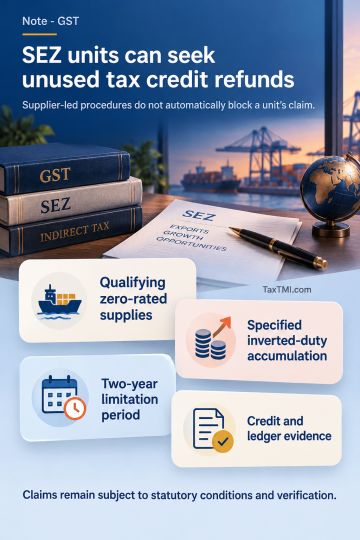
SEZ refund eligibility extends to unutilised input tax credit despite supplier-specific procedures, subject to statutory conditions and verification.
SEZ units are not categorically excluded from claiming refunds of unutilised input tax credit merely because Rule 89 prescribes a supplier-led procedure for supplies to SEZs. That procedure governs the supplier's claim for the relevant inward supply; it does not exclude a unit's own claim under the statutory refund framework. Section 54 of the CGST Act permits registered persons to claim refunds of unutilised credit subject to substantive conditions, including those governing zero-rated supplies made without payment of tax and specified inverted-duty accumulation. Refund applications must identify the applicable statutory basis, relevant date and two-year limitation period, and support the claim with evidence of qualifying supplies, credit sources, ledger balances and computation.
Case Laws Customs
Show AI Summary
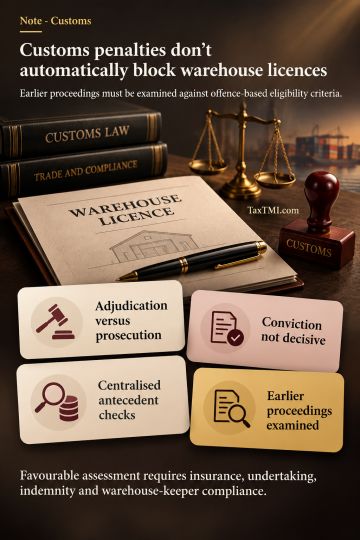
Warehouse licensing disqualification requires more than a prior customs monetary penalty and depends on offence-based eligibility criteria.
Penalisation for an offence under Regulation 3(2)(c) is not established merely by the existence of a customs monetary penalty. The legal basis and character of the earlier proceedings must be examined against the distinction between adjudicatory penalties and the offences-and-prosecutions framework. The absence of conviction alone does not resolve every disqualification ground. Antecedent verification follows a centralised process, while a favourable eligibility assessment must be followed by the insurance, undertaking, indemnity and warehouse-keeper requirements under Regulation 4.
Case Laws GST
Show AI Summary
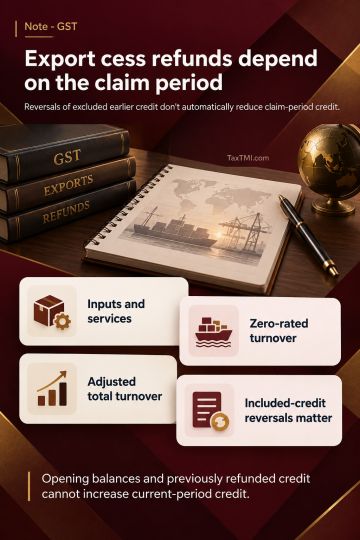
Compensation cess refunds on exports depend on period-specific credit attribution, not automatic deductions for unrelated earlier-period reversals.
Under Rule 89(4), the refund formula applies Net ITC to zero-rated turnover and adjusted total turnover. Period-specific Net ITC depends on credit availed on inputs and input services during the period for which the claim is filed. A reversal reported during that period does not automatically reduce Net ITC if it relates to residual earlier-period credit excluded from the current computation. Reversals affecting credit included in the computation remain relevant, and opening balances or previously refunded credit cannot be added to current-period Net ITC.
Case Laws GST
Show AI Summary
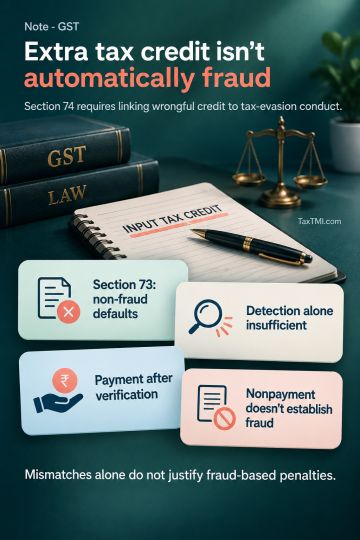
Input tax credit mismatches alone do not justify fraud-based penalties, even when excess credit is paid after verification.
Section 74 requires a factual connection between the wrongful credit and fraud, wilful misstatement or suppression of facts to evade tax; a mismatch or eligibility failure alone does not establish that connection. Section 73 covers defaults without those elements. Departmental detection, an admission of excess credit and payment after verification do not by themselves establish why the excess arose or prove the conduct necessary for Section 74. Failure to pay the pre-notice penalty cannot itself establish the fraud-related basis for Section 74.
Case Laws GST
Show AI Summary
Resort construction credit depends on immovability, own-account use, and the statutory distinction between buildings and plant and machinery.
Input tax credit on resort construction is subject to the blocked-credit restriction for goods and services received to construct immovable property on a taxable person's own account, including property used in the course or furtherance of business. The general business-use entitlement under section 16 does not displace this restriction in section 17(5)(d). The Finance Act, 2025 retrospectively substituted plant and machinery for "plant or machinery" from 1 July 2017, with the relevant provision commencing on 1 October 2025. The defined expression covers apparatus, equipment and machinery fixed to the earth by foundation or structural support and used for making outward supplies, including those foundations and supports. It excludes land, buildings and other civil structures, telecommunication towers and pipelines laid outside factory premises.
Case Laws IBC
Show AI Summary
Shareholder standing in insolvency appeals depends on legal capacity, not merely allegations of fraudulent changes to creditor-approved plans.
Individual shareholder standing to appeal against approval of a resolution plan is distinct from the legality of the plan itself. Under Section 61(1) of the Insolvency and Bankruptcy Code, 2016, an appellant must qualify as a person aggrieved. The applicable judicial interpretation restricts an appeal pursued exclusively in an individual shareholder capacity, even where equity interests are affected. Section 61(3) separately specifies permissible grounds of challenge: a plan's contravention of law and material irregularity in the resolution professional's exercise of powers are distinct grounds. Pleading either ground does not itself establish standing.
Case Laws GST
Show AI Summary
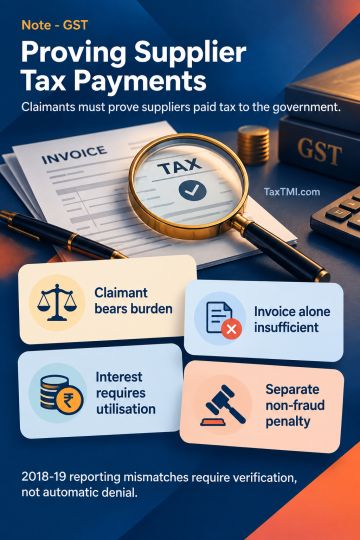
Input tax credit requires proof of supplier tax payment; reporting mismatches call for verification rather than automatic denial.
Supplier payment of tax to the Government is a condition of input tax credit eligibility under section 16(2)(c), and the claimant bears the burden of proving eligibility under section 155. Payment of the invoice and tax to the supplier, receipt of the supply and possession of an invoice do not themselves establish the supplier's remittance. For 2018-19, a GSTR-2A mismatch calls for verification and does not alone prove ineligibility. Interest under section 50(3) requires credit to have been both wrongly availed and utilised; its calculation follows Rule 88B(3). Non-fraud penalty operates under a separate statutory trigger and is not automatically excluded by the absence of fraud or utilisation.
Case Laws GST
Show AI Summary
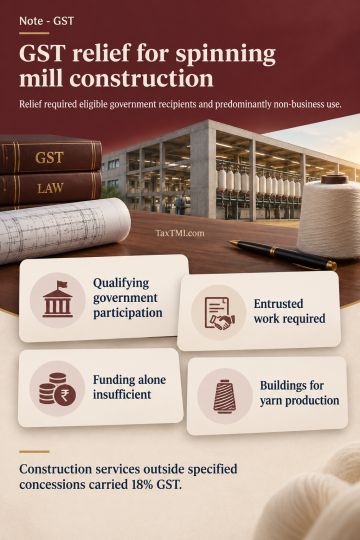
Non-business construction concessions for spinning mills require eligible recipient status and predominantly non-industrial use of the constructed buildings.
For the disputed period, the works-contract concession required both an eligible governmental recipient and structures predominantly meant for use other than commerce, industry, business or profession. Government Entity status required evidence of the recipient's constitution and qualifying governmental participation, while procurement had to relate to entrusted work. Project funding, tender approval and supervision did not by themselves establish governmental constitution or control. The spinning-mill factory buildings and allied works were intended for yarn production and related commercial activities. The residual construction-services entry carried aggregate GST of 18% for services outside the specified concessional entries.
Case Laws Customs
Show AI Summary
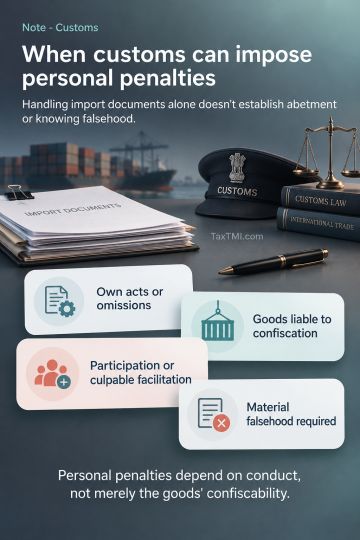
Import document handling alone does not establish customs abetment or knowing use of materially false declarations.
Personal customs penalties depend on the person's own conduct, not merely on the confiscability of imported goods. Under Section 112(a) of the Customs Act, 1962, liability may arise from a person's own act or omission rendering goods liable to confiscation or from abetment of such conduct. The direct limb can operate on a strict-liability basis where a person's own act or omission renders goods confiscable; an allegation of abetment instead requires evidence of participation or culpable facilitation. Section 114AA requires knowing or intentional making, signing or use, or causing the making, signing or use, of a declaration, statement or document that is materially false or incorrect in customs business.
Case Laws GST
Show AI Summary
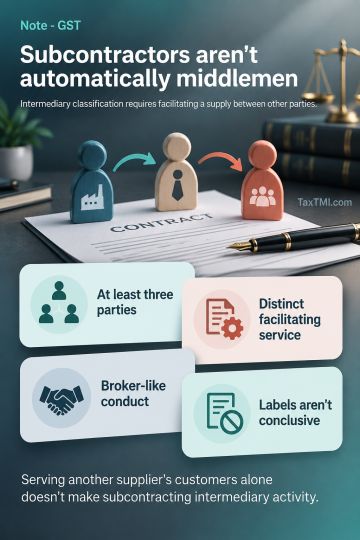
Subcontracted services performed on own account are not intermediary services merely because they support overseas recruitment and customer-facing activities.
Intermediary classification under Section 2(13) of the IGST Act distinguishes arranging or facilitating supplies between other persons from supplying services on one's own account. The intermediary framework requires at least three parties, a main supply and a distinct ancillary facilitating supply, with conduct resembling that of a broker or agent. Subcontracting the whole or part of a service is not intermediary activity merely because performance supports another supplier's business or involves its customers. Neither a bilateral agreement, contractual label nor remuneration method is conclusive.
Case Laws Customs
Show AI Summary
Split air conditioner classification requires capacity and refrigeration features to be assessed against the applicable tariff hierarchy.
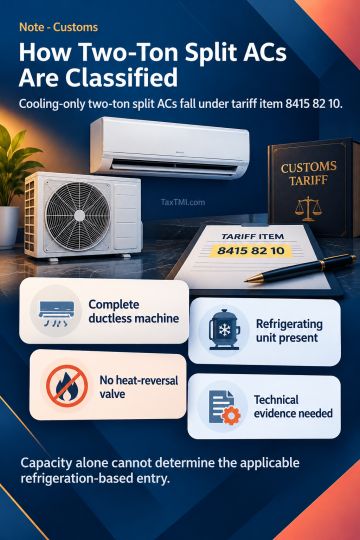
Classification of ductless split air conditioners depends on the complete tariff description and the machine's technical characteristics. A complete, cooling-only, two-ton split air conditioner incorporating a refrigerating unit and lacking a heat-reversal valve falls within tariff item 8415 82 10 rather than the general split-system item 8415 10 10. Item 8415 82 10 inherits its parent subheading's refrigerating-unit requirement, while item 8415 83 10 requires the absence of such a unit. Capacity alone does not establish the applicable refrigeration-based entry. Technical evidence should establish whether the goods are a complete machine and identify their capacity and operating features.
Case Laws Income Tax
Show AI Summary
Convertible debenture interest requires evidence-based pricing before conversion; future equity conversion alone cannot establish a nil arm's length price.
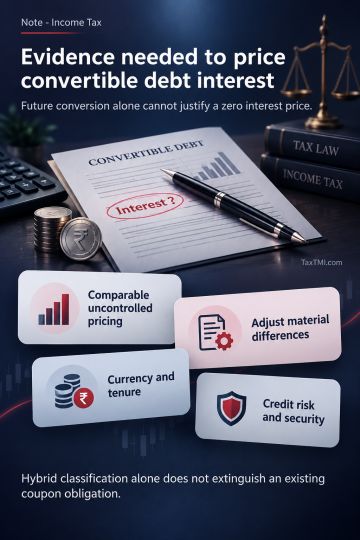
Pre-conversion interest on compulsorily convertible debentures (CCDs) issued to a non-resident associated enterprise requires arm's length pricing. Compulsory future conversion and hybrid classification do not, by themselves, establish a nil price or extinguish an existing coupon obligation. Rule 10AB's Other Method requires a price charged, paid or expected in comparable uncontrolled circumstances, with reasonably accurate adjustments for material differences under Rule 10B. Currency, benchmark date, tenure, credit risk, security, non-redemption and conversion benefits affect comparability; a conventional bank lending rate is not automatically comparable to a long-tenor CCD.
Case Laws Customs
Show AI Summary
Split motorcycle consignments require evidence of deliberate fragmentation for composite classification, with valuation assessed independently of classification.
Clubbing of split consignments for customs classification depends on proof that apparently separate imports form one deliberately fragmented transaction, not merely on the possibility of assembly. Rule 2(a) extends a tariff heading to an incomplete article possessing the essential character of the complete article and also covers a complete article presented disassembled. A change of tariff heading alone does not establish that the transaction value is inaccurate; substantive misdescription of the goods requires separate evidentiary consideration. Replacement value must follow the prescribed sequence of methods.
Case Laws GST
Show AI Summary
Corporate guarantee taxation depends on distinguishing taxable supply from valuation, particularly for unpaid support between related businesses.
GST on corporate guarantees requires separate consideration of whether a taxable supply exists and how that supply is valued. Section 7(1)(c) and Schedule I encompass qualifying supplies between related or distinct persons without consideration when made in the course or furtherance of business. Rule 28(2) deems the value of a guarantee furnished to a banking company or financial institution for a related recipient in India to be one per cent of the guaranteed amount per annum or actual consideration, whichever is higher. Where the recipient is eligible for full input tax credit, the proviso treats the value declared in the invoice as the value of the supply.
Case Laws Income Tax
Show AI Summary
Employee secondment taxation depends on employment rights, service consideration and demonstrable transfer of technical capability to host entities.
Local operational control and a stated suspension of foreign employment do not, by themselves, resolve whether underlying foreign employment rights survive. Under Article 12(4)(b) of the India-USA DTAA, technical or consultancy services must make technical knowledge, experience, skill, know-how or processes available, or involve development and transfer of a technical plan or design. Under the knowledge-transfer limb, the recipient must acquire a capability it can use independently; the mere application of expertise or presence of qualified personnel is insufficient. Recovery at actual cost and absence of markup do not, by themselves, establish that a foreign enterprise's receipt is non-taxable.
Case Laws GST
Show AI Summary
GST appellate pre-deposits may be satisfied by verified earlier payments after demand reduction, but filing fees remain independently payable.
When the first appellate authority substantially reduces the disputed tax demand, an earlier deposit may be sufficient to satisfy the Tribunal-stage requirement, subject to verification. Sufficiency depends on the reduced liability, the applicable appellate requirements and the amount actually deposited; a first appellate payment does not automatically eliminate the additional obligation. Tribunal filing fees under Section 112(7) operate independently of pre-deposit. Where a fee shortfall and earlier deposit require verification, proof of fee payment and verification of the deposit precede consideration of admission.
Case Laws Income Tax
Show AI Summary
Inter-co-operative society interest exemption preserves non-deduction by co-operative banks when depositors are co-operative societies under the statutory withholding framework.
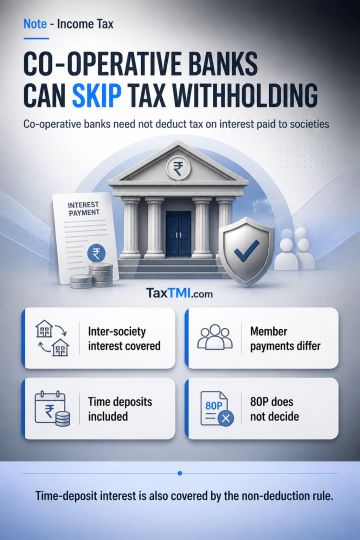
Section 194A(3)(v) separately addresses interest paid by a co-operative bank to a member and interest paid by a co-operative society to another co-operative society. The exclusion of co-operative banks is confined to the member-payment limb; a co-operative bank remains a co-operative society for the inter-co-operative society limb. Paragraph 42.7 of Circular No. 19/2015 preserves non-deduction, including time-deposit interest, where the depositor is a co-operative society. Section 80P does not determine this withholding obligation.
Case Laws GST
Show AI Summary
Input tax credit reversal requires evidence linking supplier non-payment to recipient ineligibility and a reasoned statutory inquiry.
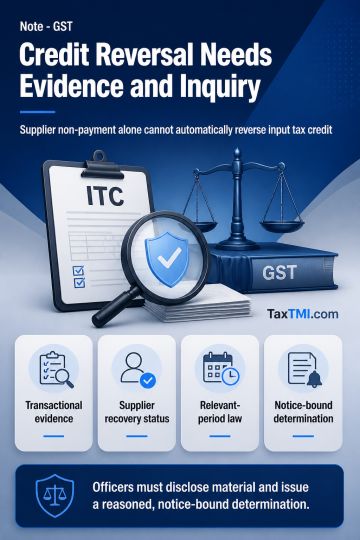
Input tax credit under Section 16(2)(c) remains conditional on actual payment of tax to Government, but supplier non-payment or retrospective cancellation cannot by itself justify reversal. The recipient must establish eligibility through transactional evidence, while the proper officer must investigate the particular supply, disclose supplier-default and recovery material, apply the law applicable to the relevant period, and issue a reasoned, notice-bound determination. Supplier recovery status and protection against duplicate collection are material considerations.
Case Laws Customs
Show AI Summary
Baggage-related customs appeals proceed through statutory revision when the jurisdictional exclusion applies to passenger imports.
The first proviso to section 129A(1) excludes Appellate Tribunal jurisdiction over an order under section 128A relating to goods imported or exported as baggage. The decisive issue is the order's connection with baggage, not disputes concerning confiscation, declaration, duty, personal effects, concealment, concession, or penalty. Articles carried by an international passenger in luggage or on the person may constitute baggage. Section 129DD provides revision before the Central Government, ordinarily within three months, subject to a further period on sufficient cause.
Case Laws GST
Show AI Summary
Departmental GST appeal monetary limits regulate officers, while composite orders and proven recurring issues may permit appeals.
Sections 120 and 168 of the Central Goods and Services Tax Act, 2017 make monetary-limit directions binding within the Central tax hierarchy, while they regulate the executive decision to file rather than create an inflexible jurisdictional bar before the Tribunal. In a composite order disposing of multiple appeals or demand notices, the relevant amount is the total disputed tax, interest, penalty or late fee, as applicable. The recurring or interpretative-issue exclusion requires a reasoned, case-specific basis, and Commissioner authorisation does not itself establish compliance with the litigation policy.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Back

All TMI Notes

Transitional Powers and Executive Discretion in Indian Tax Statutes : Clause 535 of the Income Tax Bill, 2025 Vs. Section 298 of the Income-tax Act, 1961

19 July, 2025

Contents
Acts
Rules & Regulations
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Clause 535 Removal of difficulties.

Income Tax Bill, 2025

Introduction

The power to remove difficulties (commonly known as a "removal of difficulties" or "ROD" clause) is a standard provision in Indian statutes, particularly in complex regulatory enactments such as tax laws. Clause 535 of the Income Tax Bill, 2025, and Section 298 of the Income-tax Act, 1961, both grant the Central Government the authority to address practical or unforeseen implementation issues that arise in giving effect to the respective statutes. These provisions ensure the smooth transition and operation of the law, especially during periods of legislative change or when ambiguities and operational difficulties surface. This commentary provides a detailed analysis of Clause 535, its legislative intent, operational mechanism, and practical implications, followed by a comparative evaluation with Section 298 of the 1961 Act.

Objective and Purpose

The primary objective of a removal of difficulties clause is to provide an administrative mechanism to address and resolve any practical or interpretational issues that may arise during the implementation of a statute. The rationale is to avoid unnecessary litigation, ensure continuity, and facilitate the effective administration of the law. The clause acts as a safety valve, empowering the executive to make necessary adaptations or modifications, provided they are not inconsistent with the parent statute. In the context of the Income Tax Bill, 2025, Clause 535 is particularly significant because it is designed to facilitate the transition from the Income-tax Act, 1961, to the new legislative regime. The transition involves not only substantive changes in the law but also procedural and administrative adjustments, especially in relation to assessments for tax years that straddle the period of legislative change. Similarly, Section 298 of the Income-tax Act, 1961, was inserted to address the transition from the Indian Income-tax Act, 1922, to the 1961 Act, and later adapted to address amendments introduced by the Direct Tax Laws (Amendment) Act, 1987. Both provisions are thus rooted in the need to provide legislative flexibility during periods of significant statutory overhaul.

Detailed Analysis of Clause 535 of the Income Tax Bill, 2025

Clause 535 comprises four sub-clauses, which are analyzed below:

Sub-clause (1): General Power to Remove Difficulties

"If any difficulty arises in giving effect to the provisions of this Act, the Central Government may, by general or special order, do anything not inconsistent with the provisions which appears to it to be necessary or expedient for the purpose of removing the difficulty."

This sub-clause confers upon the Central Government a broad, yet circumscribed, power to issue orders-either of general or specific application-to resolve any difficulties encountered in implementing the Act. The power is not unfettered; any action taken must not be inconsistent with the substantive provisions of the Act. The phrase "not inconsistent with the provisions" serves as a critical safeguard, ensuring that the executive cannot override or contravene the legislative intent. The use of "necessary or expedient" introduces an element of discretion, allowing the government to determine the most appropriate course of action to address the issue at hand. However, the subjective satisfaction of the government is subject to judicial review to ensure that the power is exercised within the boundaries of the statute and does not amount to legislative overreach.

Sub-clause (2): Adaptations and Modifications for Transitional Assessment Years

"In particular, and without prejudice to the generality of the foregoing power, any order referred to in sub-section (1) may provide for the adaptations or modifications subject to which the Income-tax Act, 1961 (43 of 1961) shall apply in relation to the assessments for the tax year ending on the 31st March, 2026, or any earlier tax year."

This sub-clause clarifies that the power under sub-clause (1) specifically extends to making adaptations or modifications necessary for the application of the old law (the Income-tax Act, 1961) to assessments for tax years up to and including the year ending 31st March, 2026. This is a crucial transitional provision, as it ensures that ongoing or pending assessments under the old regime can be completed without legal vacuum or procedural confusion. The provision is "without prejudice to the generality" of the power in sub-clause (1), meaning that the general power is not limited by this specific application, but this sub-clause highlights a key area where the power is likely to be exercised. The ability to adapt or modify the old law's application is essential to prevent hardship to taxpayers and the administration during the transition.

Sub-clause (3): Temporal Limitation

"No order under sub-section (1) shall be made after the expiration of three years from the 1st April, 2026."

This sub-clause imposes a sunset clause on the government's power to issue removal of difficulties orders. The power is available only for three years from 1st April, 2026. This temporal limitation is a critical check, ensuring that the extraordinary power to modify or adapt the law is used only during the initial period of transition when difficulties are most likely to arise. It prevents the indefinite extension of executive discretion and preserves the primacy of the legislative process for future amendments.

Sub-clause (4): Parliamentary Oversight

"Every order made under this section shall be laid, as soon as may be, after it is made, before each House of Parliament."

This sub-clause mandates that all orders issued under Clause 535 must be placed before both Houses of Parliament. This procedural requirement ensures transparency and accountability. Parliamentary scrutiny acts as a democratic check on the exercise of executive power, allowing legislators to review, debate, and, if necessary, object to or annul any order that exceeds the permissible limits.

Practical Implications

The inclusion of Clause 535 has several practical implications for stakeholders:

  • Taxpayers: The provision offers reassurance that transitional issues, ambiguities, or procedural uncertainties will be addressed promptly, minimizing litigation and compliance risks.
  • Tax Administration: The tax authorities are empowered to complete assessments and administer the law without being hamstrung by unforeseen procedural or interpretational difficulties.
  • Legislative Process: The clause avoids the need for frequent legislative amendments to address operational issues, thereby streamlining the implementation of the new law.
  • Checks and Balances: The requirements of non-inconsistency, temporal limitation, and parliamentary oversight act as safeguards against misuse or overreach.

Comparative Analysis with Section 298 of the Income-tax Act, 1961

Section 298 of the Income-tax Act, 1961, is the predecessor to Clause 535 and shares several structural and substantive similarities. However, there are notable differences in scope, context, and application, which are analyzed below.

Textual and Structural Parallels

Both provisions grant the Central Government the power to issue general or special orders to remove difficulties, provided such orders are not inconsistent with the Act's provisions. Both include a specific sub-clause allowing for adaptations or modifications to facilitate the application of the old law to certain transitional assessment years.

Key Differences

  1. Scope of Transitional Assessments:
    - Section 298(2): Refers to adaptations or modifications for the application of the "repealed Act" (i.e., the Income-tax Act, 1922) in relation to assessments for the year ending 31st March, 1962, or earlier.
    - Clause 535(2): Refers to the application of the Income-tax Act, 1961, for assessments for the tax year ending 31st March, 2026, or earlier.
    Analysis: The shift in reference reflects the respective statutes' roles in facilitating the transition from the 1922 Act to the 1961 Act (in Section 298), and from the 1961 Act to the new regime under the Income Tax Bill, 2025 (in Clause 535). In both cases, the transitional provision ensures that assessments under the old regime can be completed smoothly.
  2. Temporal Limitation:
    - Section 298(3): As inserted by the Direct Tax Laws (Amendment) Act, 1987, the power to issue removal of difficulties orders in relation to amendments made by that Act was limited to three years from 1st April, 1988.
    - Clause 535(3): Limits the power to three years from 1st April, 2026.
    Analysis: Both provisions impose a three-year sunset clause, reflecting a legislative consensus that extraordinary powers should be time-bound and only available during the initial period of statutory transition.
  3. Parliamentary Oversight:
    - Section 298(4): Requires that every order made under sub-section (3) be laid before each House of Parliament.
    - Clause 535(4): Requires that every order made under the section be laid before each House of Parliament.
    Analysis: The oversight mechanism is broadly similar, ensuring transparency and legislative scrutiny in both regimes.
  4. Contextual Application:
    - Section 298: Was primarily concerned with the transition from the 1922 Act to the 1961 Act and, later, the amendments introduced by the Direct Tax Laws (Amendment) Act, 1987.
    - Clause 535: Is designed to facilitate the transition from the 1961 Act to the new Income Tax Bill, 2025.
    Analysis: The context and the nature of difficulties anticipated have evolved with the complexity and scale of the tax system.
  5. Specificity of Power:
    Section 298(3) was inserted to address difficulties arising specifically from the Direct Tax Laws (Amendment) Act, 1987, and contained its own sunset clause and parliamentary oversight requirement. Clause 535, by contrast, applies generally to the entire new Act and its transition.

Interpretational Issues and Judicial Approach

Indian courts have consistently held that removal of difficulties clauses cannot be used to override or amend the substantive provisions of the parent Act. The power is administrative and facilitative, not legislative. Orders issued under such clauses are subject to judicial review, particularly on grounds of inconsistency with the parent statute or violation of constitutional principles. In the context of Section 298, courts have upheld the validity of orders issued to resolve genuine transitional issues but have cautioned against the use of such powers to introduce substantive changes or new obligations not contemplated by the Act. These interpretational principles will be equally applicable to Clause 535.

Practical and Policy Considerations

The inclusion of a removal of difficulties clause is a pragmatic legislative tool. However, it raises concerns about the potential for executive overreach and the dilution of parliamentary supremacy. The safeguards built into both Section 298 and Clause 535-namely, the requirement of consistency with the Act, temporal limitation, and parliamentary oversight-are designed to address these concerns. From a policy perspective, the clause strikes a balance between administrative flexibility and legal certainty. It allows the government to respond swiftly to operational challenges without being constrained by the slow pace of legislative amendments, while ensuring that such power is not misused.

Potential Ambiguities and Issues

a) Subjectivity of "Necessity or Expediency"

  • The determination of what is "necessary or expedient" is left to the subjective satisfaction of the executive. While this is mitigated by the requirement of consistency and judicial review, there remains a risk of overbroad or controversial orders.

b) Breadth of "Adaptations or Modifications"

  • The authority to adapt or modify the application of the repealed Act is broad, and could, in theory, be used to effect significant changes. The phrase "not inconsistent with the provisions" is intended as a safeguard, but its interpretation may itself become a matter of litigation.

c) Timeliness and Parliamentary Oversight

  • The requirement to lay orders before Parliament is subject to the vague standard of "as soon as may be." Delays in laying orders could undermine oversight and accountability. Best practices would suggest a more precise timeline.

d) Impact on Vested Rights

  • There is a potential for conflict if an order made under Clause 535 affects vested or accrued rights of taxpayers. The courts have generally protected such rights, but the possibility of litigation remains.

Practical Guidance for Stakeholders

a) Taxpayers and Advisors

Taxpayers and their advisors should closely monitor orders issued under Clause 535, especially during the first three years of the new Act's operation. Any order that appears to alter substantive rights or obligations, or that seems inconsistent with the Act, should be scrutinized and, if necessary, challenged through appropriate legal channels.

b) Tax Administrators

Tax administrators should ensure that orders made under Clause 535 are carefully drafted, justified by clear records of the difficulties encountered, and strictly limited to what is necessary to resolve those difficulties. They should also ensure timely compliance with the requirement to lay orders before Parliament.

c) Legislature

Parliament should exercise diligent oversight of orders made under Clause 535, especially those with significant policy or financial implications.

Conclusion

Clause 535 of the Income Tax Bill, 2025, is a critical transitional provision designed to facilitate the effective implementation of the new tax regime and ensure continuity during the handover from the Income-tax Act, 1961. Its structure, safeguards, and operational mechanism closely mirror those of Section 298 of the Income-tax Act, 1961, reflecting legislative continuity and the practical necessity of such a clause in complex regulatory statutes. While the power conferred is broad, it is circumscribed by requirements of consistency with the parent Act, temporal limitation, and parliamentary oversight. These safeguards are essential to maintain the balance between administrative flexibility and legal certainty, and to prevent executive overreach. The effectiveness of Clause 535 will ultimately depend on the judicious exercise of power by the executive and vigilant scrutiny by Parliament and the judiciary.


Full Text:

Clause 535 Removal of difficulties.

Topics

Acts Income Tax