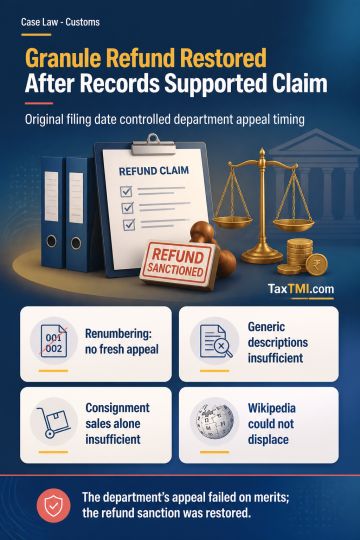
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
HC quashed reassessment where the reopening was founded on a GST cancellation order that had already been reversed in appeal. The Court noted that the appellate GST order found no fraudulent ITC claim, no violation attracting adjudication, and no basis for the cancellation. The income-tax authority also failed to consider that appellate material, despite its direct relevance to the alleged escapement of income. With no independent material beyond the set-aside GST action, the initiation of reassessment was unwarranted. The order under Section 148A(3) and the consequential notice under Section 148 were set aside.
HC quashed reassessment where the reopening was founded on a GST cancellation order that had already been reversed in appeal. The Court noted that the appellate GST order found no fraudulent ITC claim, no violation attracting adjudication, and no basis for the cancellation. The income-tax authority also failed to consider that appellate material, despite its direct relevance to the alleged escapement of income. With no independent material beyond the set-aside GST action, the initiation of reassessment was unwarranted. The order under Section 148A(3) and the consequential notice under Section 148 were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI



 Join Channel


