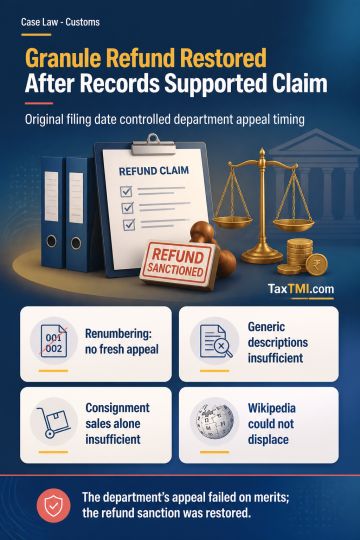
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
The HC set aside the impugned assessment order issued under Section 74 of the CGST Act due to the petitioner's submission of a Chartered Accountant's certificate confirming supplies, receipt of goods, and payment including GST, despite the supplier's liquidation. The Court noted that initiation of proceedings solely for non-furnishing of the certificate was unwarranted, especially given Circular No.183/15/2022-GST allowing transaction verification by the respondent. The matter was remanded with directions to treat the proceedings as initiated under Section 73 of the CGST Act and to decide afresh in accordance with law. The petition was disposed of by way of remand, requiring the respondent to reconsider the case and pass appropriate orders under Section 73.
The HC set aside the impugned assessment order issued under Section 74 of the CGST Act due to the petitioner's submission of a Chartered Accountant's certificate confirming supplies, receipt of goods, and payment including GST, despite the supplier's liquidation. The Court noted that initiation of proceedings solely for non-furnishing of the certificate was unwarranted, especially given Circular No.183/15/2022-GST allowing transaction verification by the respondent. The matter was remanded with directions to treat the proceedings as initiated under Section 73 of the CGST Act and to decide afresh in accordance with law. The petition was disposed of by way of remand, requiring the respondent to reconsider the case and pass appropriate orders under Section 73.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI



 Join Channel


