Loading...

⚠ โœ•
❮ Top
☎ Help
Draft upto 3 replies to a
tax notice โ€” FREE ๐ŸŽ‰ โœ•

150 credits ยท 30 days

โ€ข Basic Search โ†’ 1 Credit
โ€ข Advanced Search โ†’ 3 Credits
โ€ข Drafter โ†’ 20 to extract + 25 per issue
(โ‰ˆ upto 2-3 drafts on us)

Already used our earlier 20-Credit Demo?
You are still eligible for this new 150-Credit Demo.

Activate your FREE Demo โ†’
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedbackโœ•

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search โœ•
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
โ•ณ
Add to...
You have not created any category. Kindly create one to bookmark this item!
โœ•
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close โœ•
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
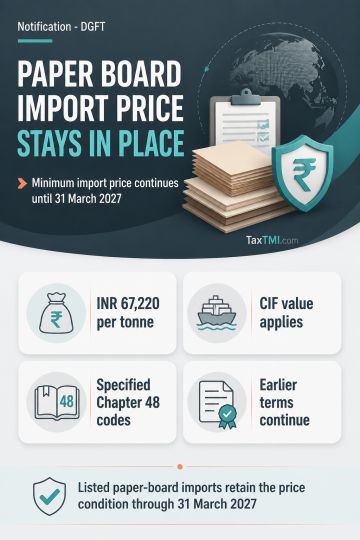
    Minimum import price condition for Virgin Multi-layer Paper Board imports remains extended under existing terms.
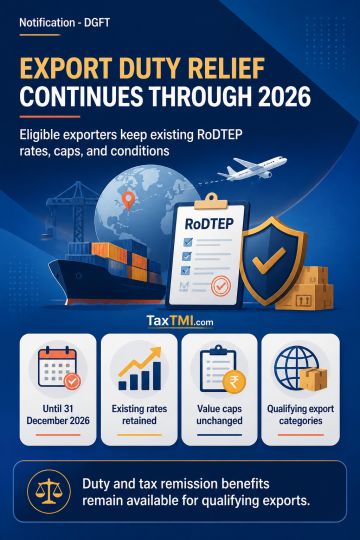
    RoDTEP Scheme continuation preserves export duty remission eligibility and existing rates, caps, and conditions for eligible exporters.
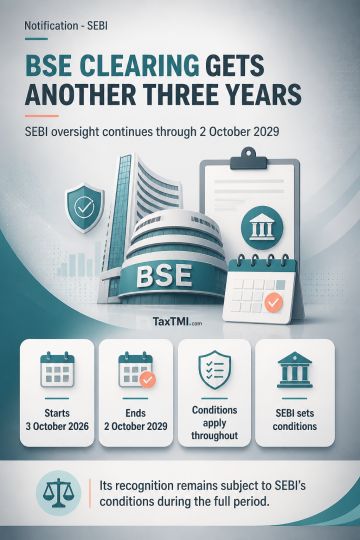
    Clearing corporation recognition renewed subject to ongoing regulatory conditions throughout the three-year recognition period.
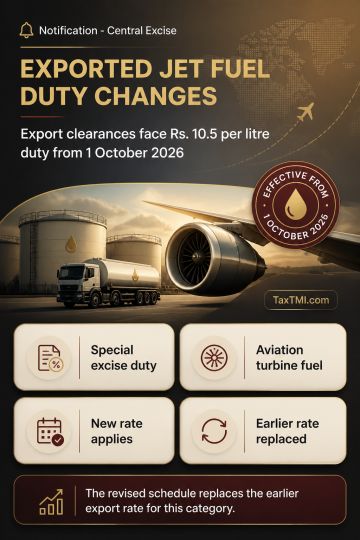
    Special additional excise duty on exported aviation turbine fuel is revised under the amended central excise rate framework.
    Customs tariff values for edible oils, brass scrap, gold, silver and areca nuts take effect prospectively.
    Special additional excise duty on fuel exports is revised through a substituted rate with prospective effect.
    Revised wage ceiling extends pension scheme membership to eligible provident fund members previously outside the scheme.
    ESIC coverage expands across designated Madhya Pradesh districts, making employer-employee contributions payable and extending statutory insurance ben...
    Minimum import price for Sulfadiazine API continues, preserving existing CIF-based import conditions for a further prescribed period.
    Research institution approval enables donation-linked tax treatment subject to SIRO status, annual reporting, donor certification, and rule compliance...
    Scientific research institution approval enables donation-related tax treatment subject to ongoing SIRO status and annual reporting compliance.
    Research institution approval grants tax-law recognition, subject to continuing SIRO status and annual donor-reporting compliance.
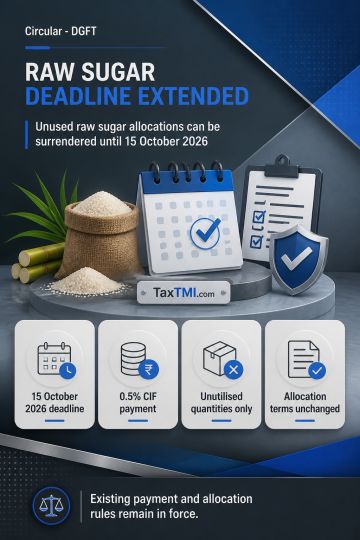
    Raw sugar tariff-rate quota surrender deadline extended, with existing CIF-value payment condition and allocation terms unchanged.
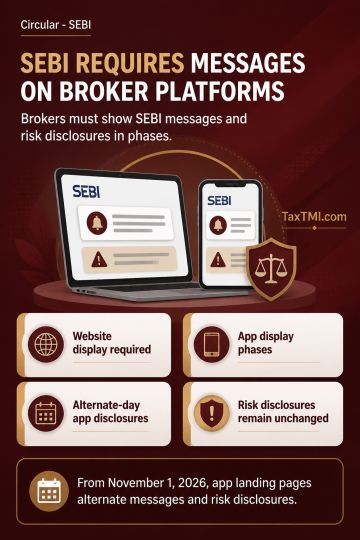
    Investor awareness messaging becomes mandatory on broker websites and trading apps, alongside risk disclosures under phased implementation.
    Control of appellate income-tax commissioners now rests with jurisdictional Principal Chief Commissioners or Chief Commissioners.
    Minimum import price conditions for ATS-8 imports are extended, preserving existing CIF valuation requirements until late November.
    RELIEF Component II eligibility timelines extend for delivery and transshipment shipments, supporting exporters facing continuing logistics disruption...
    Scientific research approval requires continuing SIRO status, annual donation reporting, and donor certification for tax compliance purposes.
    Scientific research approval requires continuing SIRO status, annual donation reporting, and donor certificates throughout its effective tax years.
    Scientific research approval requires continuing SIRO status, annual donation reporting, and donor certification for tax-recognised contributions.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

The Appellate Tribunal addressed the disallowance of...

ITAT ruled in favor of the taxpayer, allowing depreciation claimed on software & network equipment purchases.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax June 20, 2024 Case Laws AT
The Appellate Tribunal addressed the disallowance of depreciation claimed on software purchases u/s 40(a)(i)/(ia) due to non-deduction of tax at source. The AO contended that the software purchased were copyrights, hence payments were royalty. However, depreciation is a statutory deduction u/s 32, irrespective of TDS. The Tribunal cited a Supreme Court ruling emphasizing that for a payment to be royalty, there must be a right to use without commercially exploiting intellectual property. The Tribunal allowed the assessee's appeal on this issue. Regarding depreciation on servers/network equipment, the Tribunal relied on precedent and granted depreciation at 60%. The revenue's arguments were rejected.

Topics

Acts Income Tax