Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
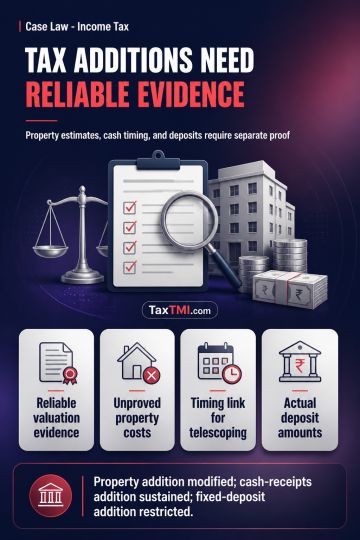
Unexplained investment in residential property is to be assessed on reliable evidence: an insurance proposal is only an estimate, while the taxpayer's disclosed estimate may be accepted where supported by statements and accounts. Expenditure claimed for old land and building requires evidence and remains unexplained if unproved. Telescoping of undisclosed cash receipts against property investment is unavailable without material showing that both relate to the same period. Unaccounted fixed-deposit additions should be confined to the actual amounts invested, not their maturity values. The discussion describes modification of the property-investment addition, sustenance of the cash-receipts addition, and restriction of the fixed-deposit addition to actual investment.
Unexplained investment in residential property is to be assessed on reliable evidence: an insurance proposal is only an estimate, while the taxpayer's disclosed estimate may be accepted where supported by statements and accounts. Expenditure claimed for old land and building requires evidence and remains unexplained if unproved. Telescoping of undisclosed cash receipts against property investment is unavailable without material showing that both relate to the same period. Unaccounted fixed-deposit additions should be confined to the actual amounts invested, not their maturity values. The discussion describes modification of the property-investment addition, sustenance of the cash-receipts addition, and restriction of the fixed-deposit addition to actual investment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI