Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
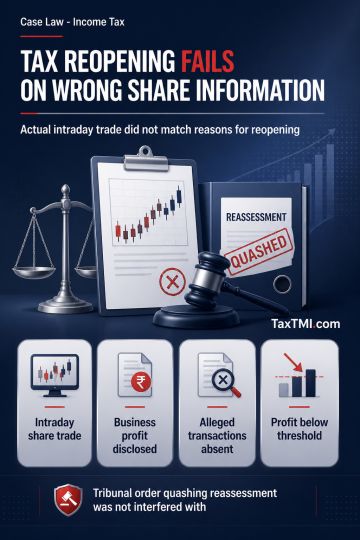
Reassessment based on inapplicable information is examined where recorded reasons allege manipulated share transactions involving capital gains or losses, but the taxpayer's actual transaction was an intraday share trade with disclosed business profit. The notes state that, where the alleged transactions do not exist in the taxpayer's case and the disclosed profit remains below the reopening threshold cited in the reasons, the factual foundation for reopening fails. They further note that a Tribunal order quashing such reassessment was not interfered with because no substantial question of law arose from those factual findings.
Reassessment based on inapplicable information is examined where recorded reasons allege manipulated share transactions involving capital gains or losses, but the taxpayer's actual transaction was an intraday share trade with disclosed business profit. The notes state that, where the alleged transactions do not exist in the taxpayer's case and the disclosed profit remains below the reopening threshold cited in the reasons, the factual foundation for reopening fails. They further note that a Tribunal order quashing such reassessment was not interfered with because no substantial question of law arose from those factual findings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI