Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Advertisement, marketing and brand-promotion expenditure...
Business expenditure deductibility covers independent brand promotion and unreimbursed inventory price-drop margin losses where commercially genuine and verifiable.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
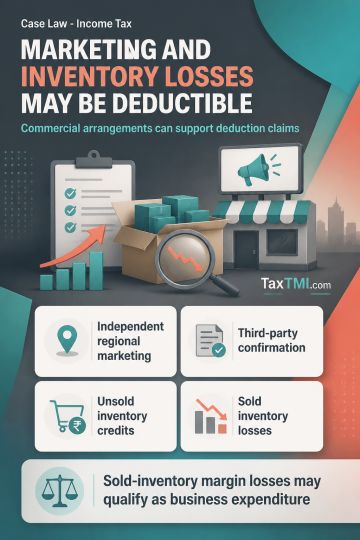
Advertisement, marketing and brand-promotion expenditure incurred by a super authorised mobile-phone distributor is discussed as deductible business expenditure where a lower purchase price reflects a commercial arrangement for independent regional marketing, rather than reimbursement by the brand owner. Third-party confirmation and the absence of evidence that expenditure was fictitious, inflated or unincurred support its business necessity. The notes also address price-drop credits to downstream dealers: brand-owner reimbursement is limited to unsold inventory and its invoice price, while the distributor's unreimbursed margin reversal on sold inventory may constitute a genuine, verifiable commercial loss deductible as business expenditure.
Advertisement, marketing and brand-promotion expenditure incurred by a super authorised mobile-phone distributor is discussed as deductible business expenditure where a lower purchase price reflects a commercial arrangement for independent regional marketing, rather than reimbursement by the brand owner. Third-party confirmation and the absence of evidence that expenditure was fictitious, inflated or unincurred support its business necessity. The notes also address price-drop credits to downstream dealers: brand-owner reimbursement is limited to unsold inventory and its invoice price, while the distributor's unreimbursed margin reversal on sold inventory may constitute a genuine, verifiable commercial loss deductible as business expenditure.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI