Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
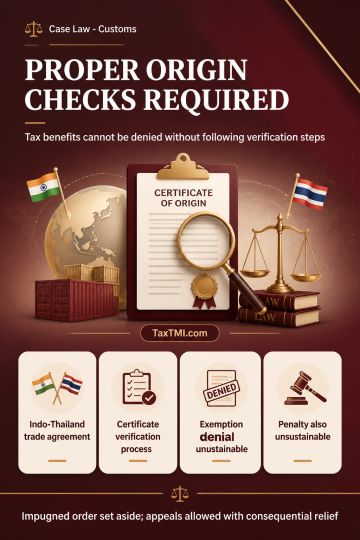
Preferential customs-duty exemption under the Indo-Thailand Free Trade Agreement depends on compliance with the prescribed process for verifying a Certificate of Origin under the Interim Rules of Origin. The text states that Revenue did not follow the procedure in Notification No. 101/2004-Cus. (N.T.) before challenging the certificate's credibility. It therefore records that denial of exemption under Notification No. 85/2004-Cus. was unsustainable, as was the consequential penalty for alleged improper import. The impugned order was set aside and the appeals were allowed with consequential relief.
Preferential customs-duty exemption under the Indo-Thailand Free Trade Agreement depends on compliance with the prescribed process for verifying a Certificate of Origin under the Interim Rules of Origin. The text states that Revenue did not follow the procedure in Notification No. 101/2004-Cus. (N.T.) before challenging the certificate's credibility. It therefore records that denial of exemption under Notification No. 85/2004-Cus. was unsustainable, as was the consequential penalty for alleged improper import. The impugned order was set aside and the appeals were allowed with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI