Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
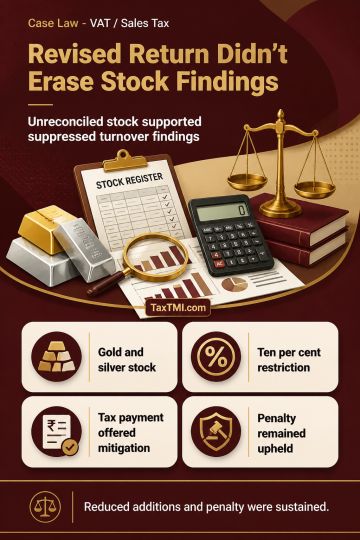
Unaccounted gold and silver stock detected during income-tax inspection supported findings of suppressed purchases and consequential sales, notwithstanding a revised return filed after inspection. The article distinguishes cases where equal additions rested only on conjectural probable suppression or disclosures preceded audit, stating that inspection-based unreconciled stock differences provide material for assessment. It notes that tax paid on revised disclosure may mitigate an equal addition, but does not protect a dealer unless the failure to maintain true accounts was neither wilful nor intentional. The Tribunal's restriction of equal additions to 10 per cent was sustained. Penalty was also upheld because the dealer did not justify omissions in full and true disclosure, and the statutory penalty provision applied to established suppressed turnover.
Unaccounted gold and silver stock detected during income-tax inspection supported findings of suppressed purchases and consequential sales, notwithstanding a revised return filed after inspection. The article distinguishes cases where equal additions rested only on conjectural probable suppression or disclosures preceded audit, stating that inspection-based unreconciled stock differences provide material for assessment. It notes that tax paid on revised disclosure may mitigate an equal addition, but does not protect a dealer unless the failure to maintain true accounts was neither wilful nor intentional. The Tribunal's restriction of equal additions to 10 per cent was sustained. Penalty was also upheld because the dealer did not justify omissions in full and true disclosure, and the statutory penalty provision applied to established suppressed turnover.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI