Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
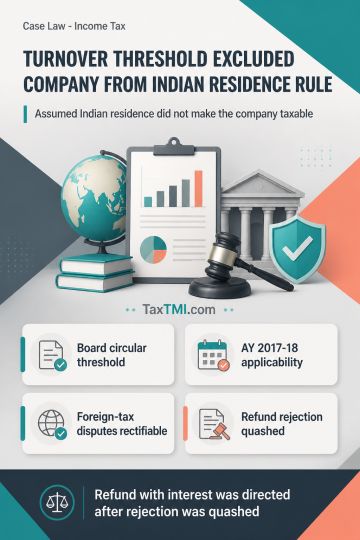
Place of effective management residence rules do not apply to a company whose turnover or gross receipts fall within the stipulated threshold under the Board circular, effective from Assessment Year 2017-18. The notes state that a New Zealand-incorporated company was therefore not liable to Indian tax merely because it had assumed Indian residence and filed returns on that basis, making the tax paid refundable. They further explain that rectification is available where foreign-tax payment was previously disputed but is later settled, and that procedural barriers should not deny substantive double-taxation relief. The rejection of refund was quashed and refund with interest was directed in accordance with law.
Place of effective management residence rules do not apply to a company whose turnover or gross receipts fall within the stipulated threshold under the Board circular, effective from Assessment Year 2017-18. The notes state that a New Zealand-incorporated company was therefore not liable to Indian tax merely because it had assumed Indian residence and filed returns on that basis, making the tax paid refundable. They further explain that rectification is available where foreign-tax payment was previously disputed but is later settled, and that procedural barriers should not deny substantive double-taxation relief. The rejection of refund was quashed and refund with interest was directed in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI