Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
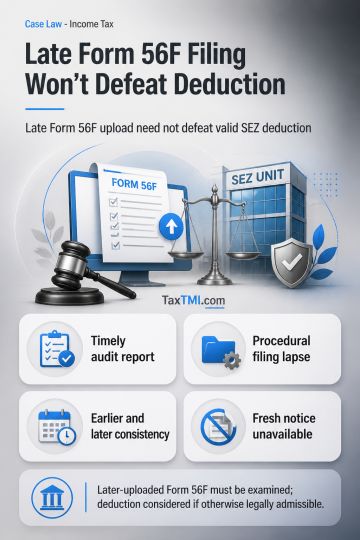
A deduction under Section 10AA should not be rejected solely because Form 56F was not attached to the return where the audit report had been obtained before the filing deadline and uploaded later. The omission is characterised as a procedural lapse, and automated return processing or the Centralized Processing Centre's inability to issue a fresh notice cannot by itself defeat an otherwise legitimate claim. The doctrine of consistency is also relevant where the deduction had been allowed in earlier and later years. The described decision required examination of the subsequently uploaded Form 56F and consideration of the deduction subject to its being otherwise admissible in law.
A deduction under Section 10AA should not be rejected solely because Form 56F was not attached to the return where the audit report had been obtained before the filing deadline and uploaded later. The omission is characterised as a procedural lapse, and automated return processing or the Centralized Processing Centre's inability to issue a fresh notice cannot by itself defeat an otherwise legitimate claim. The doctrine of consistency is also relevant where the deduction had been allowed in earlier and later years. The described decision required examination of the subsequently uploaded Form 56F and consideration of the deduction subject to its being otherwise admissible in law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI