Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
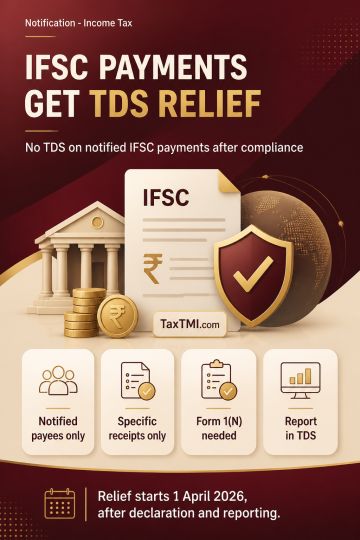
No tax deduction at source is required on specified payments made to eligible IFSC units where the payee falls within notified categories such as banking units, finance companies, finance units, fund management entities, broker dealers, investment advisers, custodians, credit rating agencies, investment bankers, debenture trustees, ITFS entities and FinTech entities, and the receipt is a notified item including interest, dividend, professional fees, advisory fees, distribution fees, commission, brokerage or insurance commission. The relief applies only if the payee remains a registered IFSC unit providing qualifying financial services, furnishes Form 1(N) for each opted tax year within the twenty consecutive tax years under section 147, and the payer receives the declaration and reports non-deducted payments in its TDS statement. The notification operates from 1 April 2026.
No tax deduction at source is required on specified payments made to eligible IFSC units where the payee falls within notified categories such as banking units, finance companies, finance units, fund management entities, broker dealers, investment advisers, custodians, credit rating agencies, investment bankers, debenture trustees, ITFS entities and FinTech entities, and the receipt is a notified item including interest, dividend, professional fees, advisory fees, distribution fees, commission, brokerage or insurance commission. The relief applies only if the payee remains a registered IFSC unit providing qualifying financial services, furnishes Form 1(N) for each opted tax year within the twenty consecutive tax years under section 147, and the payer receives the declaration and reports non-deducted payments in its TDS statement. The notification operates from 1 April 2026.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI