Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
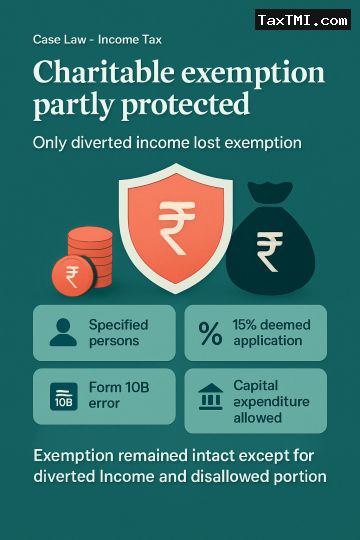
Partial denial of exemption for benefit to specified persons was confined to the income said to have been diverted; the broader exemption under sections 11 and 12 was not forfeited in full, and the 15 per cent amount treated as deemed application under section 11 was deleted. A payment to a related concern was not hit by the specified concern rule because the trustee's voting power was below the 20 per cent threshold, and a procedural error in Form 10B did not defeat the exemption claim. Capital expenditure was also allowed as application of income on an accrual basis, with supporting invoices, disclosure in the balance sheet, and replies to notices sufficient on the facts.
Partial denial of exemption for benefit to specified persons was confined to the income said to have been diverted; the broader exemption under sections 11 and 12 was not forfeited in full, and the 15 per cent amount treated as deemed application under section 11 was deleted. A payment to a related concern was not hit by the specified concern rule because the trustee's voting power was below the 20 per cent threshold, and a procedural error in Form 10B did not defeat the exemption claim. Capital expenditure was also allowed as application of income on an accrual basis, with supporting invoices, disclosure in the balance sheet, and replies to notices sufficient on the facts.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI