Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
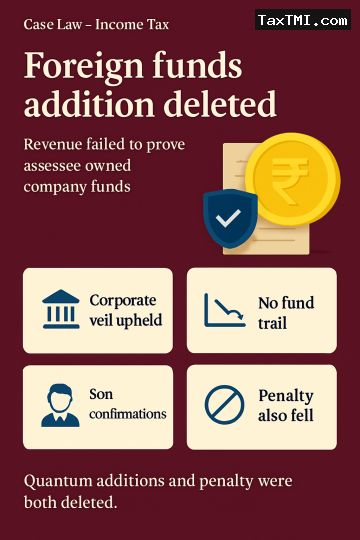
Separate corporate personality was upheld for the two foreign companies, and section 69A could not be applied because the Revenue failed to show by cogent evidence that their bank funds belonged beneficially to the assessee. Mere earlier shareholding, directorship, or authority to operate accounts was held insufficient to lift the corporate veil, especially when no material showed flow of funds from India to the companies or receipt by the assessee from those accounts. The assessee's explanation that the transactions related to his non-resident son and son-in-law was supported by confirmations, and his prior resignation and share transfer further weakened the ownership allegation. The quantum additions were deleted, and the related penalty under section 271(1)(c) also fell.
Separate corporate personality was upheld for the two foreign companies, and section 69A could not be applied because the Revenue failed to show by cogent evidence that their bank funds belonged beneficially to the assessee. Mere earlier shareholding, directorship, or authority to operate accounts was held insufficient to lift the corporate veil, especially when no material showed flow of funds from India to the companies or receipt by the assessee from those accounts. The assessee's explanation that the transactions related to his non-resident son and son-in-law was supported by confirmations, and his prior resignation and share transfer further weakened the ownership allegation. The quantum additions were deleted, and the related penalty under section 271(1)(c) also fell.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI