Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
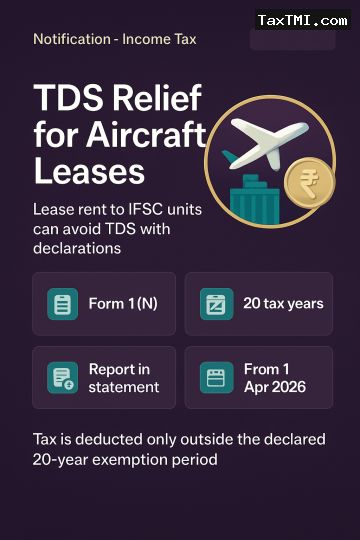
No deduction of tax is required under section 393(1) on lease rent or supplemental lease rent paid to an IFSC unit leasing aircraft, provided the lessor furnishes the prescribed statement-cum-declaration in Form 1(N) and the lessee receives it. The exemption applies only for the twenty consecutive tax years declared by the lessor for which deduction under section 147 is opted; for any other year, tax must be deducted. The lessee must report all non-deducted payments in the tax deduction statement, and the notification applies from 1 April 2026. It also sets system and data-security responsibilities for the tax systems authority and defines aircraft, IFSC, and unit by reference to the Act and SEZ law.
No deduction of tax is required under section 393(1) on lease rent or supplemental lease rent paid to an IFSC unit leasing aircraft, provided the lessor furnishes the prescribed statement-cum-declaration in Form 1(N) and the lessee receives it. The exemption applies only for the twenty consecutive tax years declared by the lessor for which deduction under section 147 is opted; for any other year, tax must be deducted. The lessee must report all non-deducted payments in the tax deduction statement, and the notification applies from 1 April 2026. It also sets system and data-security responsibilities for the tax systems authority and defines aircraft, IFSC, and unit by reference to the Act and SEZ law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI