Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
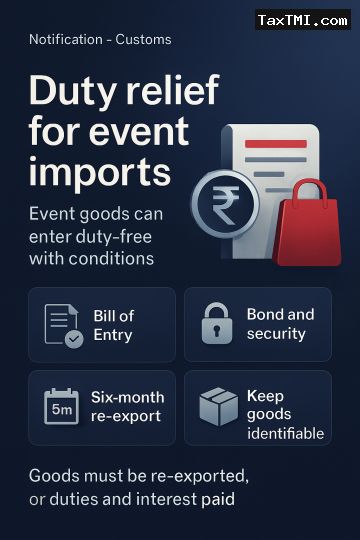
Goods imported into India for display or use at specified events under the India-UK Comprehensive Economic and Trade Agreement are exempt from basic customs duty and integrated tax, subject to re-export and specified conditions. The importer must file a declaration at Bill of Entry stage, execute a bond and security, and keep the goods identifiable and at the event location unless permitted otherwise. The goods must be re-exported within six months of clearance, though certain government and diplomatic imports may receive extensions up to two years. The goods may also be entered for home consumption before expiry on payment of applicable duties and interest.
Goods imported into India for display or use at specified events under the India-UK Comprehensive Economic and Trade Agreement are exempt from basic customs duty and integrated tax, subject to re-export and specified conditions. The importer must file a declaration at Bill of Entry stage, execute a bond and security, and keep the goods identifiable and at the event location unless permitted otherwise. The goods must be re-exported within six months of clearance, though certain government and diplomatic imports may receive extensions up to two years. The goods may also be entered for home consumption before expiry on payment of applicable duties and interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI