Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
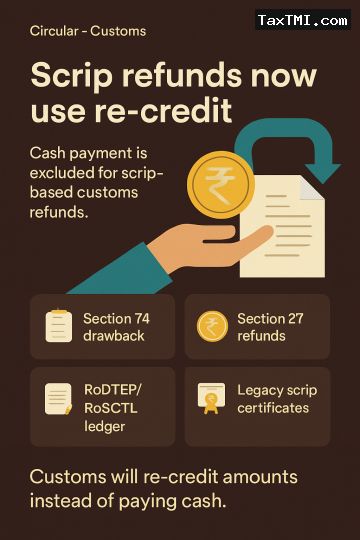
Where import duty was paid through duty credit scrips, any drawback under section 74 or refund under section 27 of the Customs Act, 1962 is to be granted by re-credit, not in cash. For RoDTEP/RoSCTL scrips, the amount is to be re-credited to the IEC holder's electronic credit ledger and may be used for generation of e-scrips under the prescribed scheme. For legacy scrips such as MEIS or SEIS, where direct re-credit is not feasible, Customs must issue a re-credit certificate containing the utilised scrip details, import date and debited amount. The circular also notes that CBIC will issue further system guidance after module development.
Where import duty was paid through duty credit scrips, any drawback under section 74 or refund under section 27 of the Customs Act, 1962 is to be granted by re-credit, not in cash. For RoDTEP/RoSCTL scrips, the amount is to be re-credited to the IEC holder's electronic credit ledger and may be used for generation of e-scrips under the prescribed scheme. For legacy scrips such as MEIS or SEIS, where direct re-credit is not feasible, Customs must issue a re-credit certificate containing the utilised scrip details, import date and debited amount. The circular also notes that CBIC will issue further system guidance after module development.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI