Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
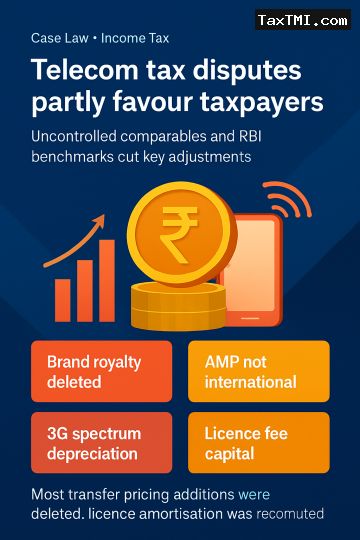
Controlled transactions cannot be used as CUP comparables for brand royalty, so that adjustment was deleted. ECB interest benchmarking accepted RBI approval as a relevant contemporaneous benchmark and deleted the adjustment. AMP expenditure was not treated as an international transaction without tangible evidence of an arrangement. Depreciation on 3G spectrum rights, DoT subscriber verification payments, prepaid distributor discount and IBM hardware lease rentals were allowed, while liabilities written back were sustained and asset restoration cost was allowed as revenue expenditure. Annual licence fee remained capital in nature with only recomputation of amortisation under the telecom licence regime, and WPC royalty charges were also allowed.
Controlled transactions cannot be used as CUP comparables for brand royalty, so that adjustment was deleted. ECB interest benchmarking accepted RBI approval as a relevant contemporaneous benchmark and deleted the adjustment. AMP expenditure was not treated as an international transaction without tangible evidence of an arrangement. Depreciation on 3G spectrum rights, DoT subscriber verification payments, prepaid distributor discount and IBM hardware lease rentals were allowed, while liabilities written back were sustained and asset restoration cost was allowed as revenue expenditure. Annual licence fee remained capital in nature with only recomputation of amortisation under the telecom licence regime, and WPC royalty charges were also allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI