Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
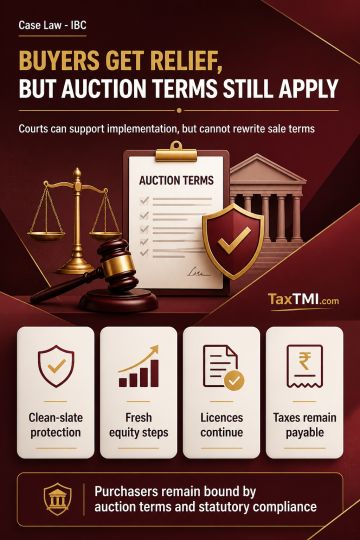
Residuary jurisdiction in liquidation permits incidental and consequential directions necessary to give commercial effect to a going-concern sale, including revised shareholding, fresh equity, listing-related steps, removal of historical encumbrances, and restoration of active corporate status, subject to applicable procedures and regulatory powers. A going-concern purchaser receives clean-slate protection from pre-sale liabilities, while pending proceedings may continue in the corporate debtor's name under new management without determining their merits. Subsisting licences, approvals and contractual rights continue subject to compliance obligations. Relief extending to all receivables or creating a fresh limitation period is unavailable where not contemplated by the sale documents. Auction terms remain binding: statutory taxes, duties, charges and fees assumed by the purchaser cannot be waived through additional relief.
Residuary jurisdiction in liquidation permits incidental and consequential directions necessary to give commercial effect to a going-concern sale, including revised shareholding, fresh equity, listing-related steps, removal of historical encumbrances, and restoration of active corporate status, subject to applicable procedures and regulatory powers. A going-concern purchaser receives clean-slate protection from pre-sale liabilities, while pending proceedings may continue in the corporate debtor's name under new management without determining their merits. Subsisting licences, approvals and contractual rights continue subject to compliance obligations. Relief extending to all receivables or creating a fresh limitation period is unavailable where not contemplated by the sale documents. Auction terms remain binding: statutory taxes, duties, charges and fees assumed by the purchaser cannot be waived through additional relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921