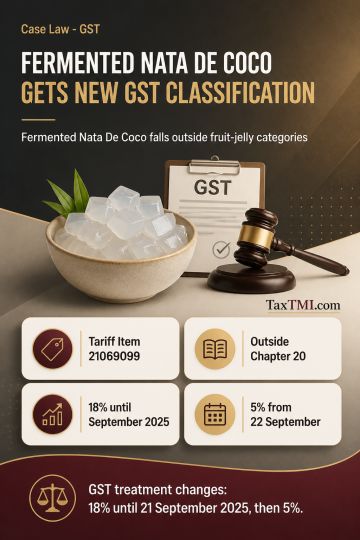
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
The search-penalty framework under section 271AAB(1) requires a finding that surrendered income meets the statutory definition of undisclosed income; surrender during search alone is insufficient. The notice and penalty order must specify the applicable statutory default or clause, because an admission in a search statement does not automatically attract the provision. Where the assessment order is appealed, search-penalty proceedings must be completed within six months of receipt of the appellate order; an order issued after that period is barred by limitation.
The search-penalty framework under section 271AAB(1) requires a finding that surrendered income meets the statutory definition of undisclosed income; surrender during search alone is insufficient. The notice and penalty order must specify the applicable statutory default or clause, because an admission in a search statement does not automatically attract the provision. Where the assessment order is appealed, search-penalty proceedings must be completed within six months of receipt of the appellate order; an order issued after that period is barred by limitation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921