Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
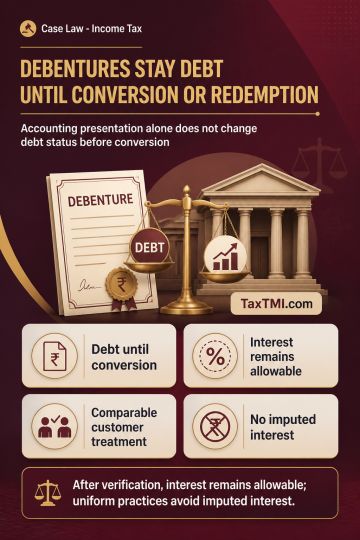
Transfer-pricing treatment of compulsorily convertible debentures turns on their legal status until actual conversion or redemption. Ind AS presentation of a component as equity within a compound financial instrument does not by itself change outstanding debentures from debt; interest remains allowable where reclassification is solely for financial-reporting purposes, subject to verification of conversion or redemption. Notional interest on delayed associated-enterprise receivables should not be imputed where comparable non-associated customers receive the same no-interest treatment and the taxpayer applies that practice consistently. The relevant principle is commercial uniformity across comparable transactions.
Transfer-pricing treatment of compulsorily convertible debentures turns on their legal status until actual conversion or redemption. Ind AS presentation of a component as equity within a compound financial instrument does not by itself change outstanding debentures from debt; interest remains allowable where reclassification is solely for financial-reporting purposes, subject to verification of conversion or redemption. Notional interest on delayed associated-enterprise receivables should not be imputed where comparable non-associated customers receive the same no-interest treatment and the taxpayer applies that practice consistently. The relevant principle is commercial uniformity across comparable transactions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI