Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
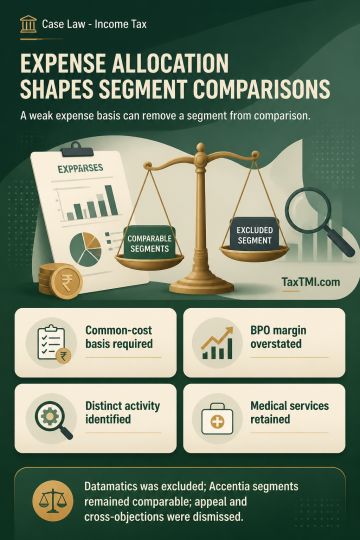
TNMM segmental comparability requires a reliable allocation of common operating expenses when OP/OC is used as the profit-level indicator. Information obtained from a proposed comparable does not itself establish the reliability of its segmental data. Because material entity-level expenses were not allocated to Datamatics Financial Services Ltd.'s BPO segment and no verifiable allocation basis was shown, its margin overstated profitability and the segment was excluded as an uncontrolled benchmark. Conversely, separately reported medical transcription, billing, coding and related IT-enabled service segments of Accentia Technologies Ltd. remained comparable: its distinct software development activity was identified and excluded, and no functional dissimilarity in the retained segments was established. Revenue's appeal and the assessee's cross-objections were dismissed.
TNMM segmental comparability requires a reliable allocation of common operating expenses when OP/OC is used as the profit-level indicator. Information obtained from a proposed comparable does not itself establish the reliability of its segmental data. Because material entity-level expenses were not allocated to Datamatics Financial Services Ltd.'s BPO segment and no verifiable allocation basis was shown, its margin overstated profitability and the segment was excluded as an uncontrolled benchmark. Conversely, separately reported medical transcription, billing, coding and related IT-enabled service segments of Accentia Technologies Ltd. remained comparable: its distinct software development activity was identified and excluded, and no functional dissimilarity in the retained segments was established. Revenue's appeal and the assessee's cross-objections were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI