Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
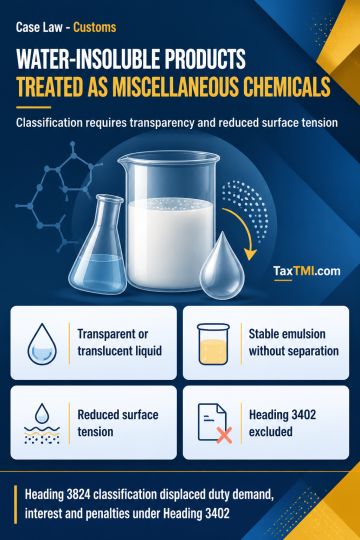
Classification of low-ethoxylated lauryl alcohol ethoxylate depends on the tariff headings and Chapter Note 3 under GIR 1. Chapter Note 3 imposes cumulative conditions: the product must form a transparent or translucent liquid or stable emulsion without separation of insoluble matter, and reduce surface tension. Chemical test reports showing a translucent liquid with separated insoluble matter fail the first condition, even where the surface-tension requirement is met. Water-insoluble surface-active products are excluded from Heading 3402 and classified as miscellaneous chemical products under Heading 3824. Classification under Heading 3824 consequently displaced the duty demand, interest and penalties founded on Heading 3402.
Classification of low-ethoxylated lauryl alcohol ethoxylate depends on the tariff headings and Chapter Note 3 under GIR 1. Chapter Note 3 imposes cumulative conditions: the product must form a transparent or translucent liquid or stable emulsion without separation of insoluble matter, and reduce surface tension. Chemical test reports showing a translucent liquid with separated insoluble matter fail the first condition, even where the surface-tension requirement is met. Water-insoluble surface-active products are excluded from Heading 3402 and classified as miscellaneous chemical products under Heading 3824. Classification under Heading 3824 consequently displaced the duty demand, interest and penalties founded on Heading 3402.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939