Loading...

Top
Help
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback

Contact Us At :

E-mail: [email protected]

Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
Add to...
You have not created any category. Kindly create one to bookmark this item!
Create New Category
Hide
Title :
Description :
❮❮ Hide
Default View
Expand ❯❯
Close ✕
🔎 Highlights - Adv. Search
TEXT SEARCH:

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In:
Main Text + AI Text
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws----
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ----
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ----
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Advocate-Client Privilege Limits: GST investigations may examine counsel conduct while preserving unrelated client data confidentiality
    Same-subject-matter bar under GST requires identical contravention, so distinct credit allegations proceed through statutory appeals.
    Statutory appellate remedy channels parallel GST proceedings and jurisdiction objections from writ review to factual appellate examination.
    Alternative statutory remedy in GST adjudication generally bars writ review after an Order-in-Original, absent patent jurisdictional error.
    GST reimbursement for post-GST works contracts requires assessment under the notification's applicable provision, not the pre-GST clause.
    GST registration cancellation beyond show-cause notice was quashed, with fresh proceedings permitted after a hearing.
    Special GST law bars general criminal prosecution where alleged tax defaults are already addressed under the CGST framework.
    Alternative statutory remedy requires appellate exhaustion before direct writ challenges to GST assessment and rectification orders proceed.
    Weekly-market fee collection rights leased by Panchayats remain public-authority functions and fall outside GST when linked to markets and fairs.
    Bovine semen sorting is taxable as a scientific and technical service, not exempt animal husbandry support.
    Input tax credit on land-survey services is unavailable for land surrendered to fulfil afforestation obligations.
    Specific condonation circular governs delayed co-operative society returns claiming Section 80P deductions amid genuine hardship.
    Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
    Section 47(xiii) succession remains exempt despite pre-conversion capital withdrawals, while section 153A fails without incriminating material.
    Venture capital fund exemption survives separate schemes, trustees' fiduciary holdings, and uncancelled regulatory registration for tax purposes.
    Section 270A penalties cannot rest on disclosed APA adjustments, precedent-supported CSR claims, or later retrospective education-cess amendments.
    Functional characterisation of spare replacement services supports TNMM over RPM where customer and resale-price control are absent.
    Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
    Information suggesting income escapement cannot support reassessment where it merely seeks verification through a roving inquiry.
    Valid reassessment information excludes demerger receipts already taxed by resulting company, defeating extended limitation for reassessment.
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Showing Results for : Reset Filters

Continuing personal guarantees are not novated by a consent...

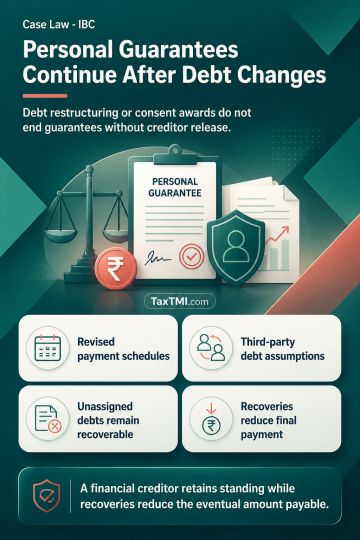
Continuing personal guarantees survive consent awards, debt restructuring and third-party assumptions unless creditors expressly release the guarantor.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

IBC September 19, 2026 Case Laws AT
Continuing personal guarantees are not novated by a consent arbitral award that merely revises the payment schedule, nor by third-party assumption of debt, absent creditor-approved substitution or express release. A financial creditor retains standing to invoke its unassigned and unpaid debt despite other consortium lenders assigning their debts or enforcing security. Surety discharge for contractual variation requires an unauthorised change between the principal debtor and that creditor; restructuring by another creditor is insufficient, particularly where the guarantee preserves liability. For an on-demand guarantee, limitation runs from the subsequent default after demand. Once debt and default are established, calculation disputes do not defeat admission, though recoveries from all sources must reduce the amount ultimately payable.

Topics

Acts Income Tax





















